
You have three or five or nine businesses under one thesis, and each one runs a different CRM. One is on Salesforce configured by a departed admin. Another lives in HubSpot. A third tracks its pipeline in a spreadsheet that one sales manager guards like a personal asset. When your operating partner asks a simple question, “what is combined new-business pipeline this quarter, and how much of it is real,” nobody can answer it in less than two weeks of manual reconciliation. That gap is the problem. It slows the board’s read on revenue, it hides deteriorating conversion until it shows up in the actuals, and it makes every add-on integration harder than it should be.
CRM consolidation for portfolio companies is the decision to reduce that sprawl to a smaller, governed set of systems so revenue becomes measurable, comparable, and integratable across the portfolio. It is not an IT project. It is a revenue-visibility and enterprise-value decision, and the person who owns it is you, the operating partner or the portfolio-company executive who has to defend a forecast. This guide walks through what you actually need to decide, in what order, and how to judge whether it is working, without pretending every portfolio company should be forced onto one instance.
1. Name the commercial problem before you name a platform
The failure mode here is starting with “should we standardize on Salesforce or HubSpot.” That is a downstream question. The question that comes first is: what commercial decision are you unable to make today because of how CRM data is organized?
In practice, the pain concentrates in a few places. You cannot compare sales efficiency across companies because each defines a “qualified opportunity” differently. You cannot roll up a portfolio-wide forecast without a finance analyst rebuilding it by hand every month. When you acquire an add-on, its pipeline data takes a quarter to become trustworthy inside the platform because nobody agreed on the fields. And when you approach exit, a buyer’s technology due diligence team finds a fragmented revenue stack and marks it down as integration risk.
Write those problems down as commercial consequences, not technical complaints. “Forecast reliability is poor” is a board problem. “We run four CRMs” is only a symptom. Bain’s annual Global Private Equity Report has documented for years that value creation has shifted decisively toward operational improvement rather than multiple expansion, and revenue visibility is one of the most direct operational levers you control. Frame the project against that, or it will read as a cost line the CFO wants to cut.
2. Decide whether you even need one CRM at all
This is the decision most vendors will not let you make honestly, because it can shrink their scope. The right answer is frequently “not one, but fewer, with a common reporting layer.”
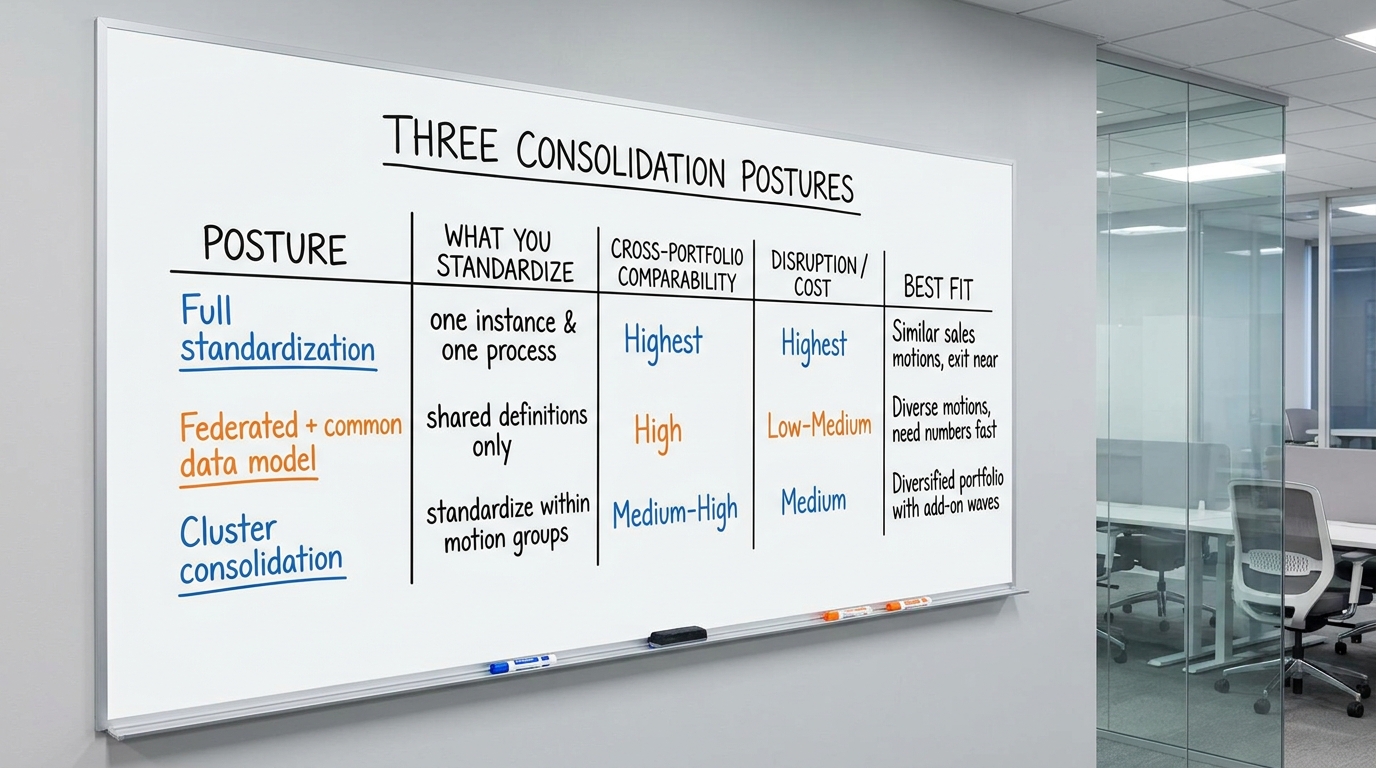
There are three consolidation postures, and they are genuinely different bets:
Full standardization
Every portfolio company migrates to a single CRM instance or a single multi-tenant setup. This gives you the cleanest cross-portfolio comparability and the strongest position at exit. It is also the most disruptive, the most expensive, and the most likely to stall if the businesses have materially different sales motions. Standardizing a transactional inside-sales business and a complex enterprise-deal business onto identical process rarely survives contact with the field.
Federated with a common data model
Companies keep their own CRM, but you enforce a shared definition of the core objects: what a lead is, what a qualified opportunity is, what a stage means, how a closed-won deal is dated. You then pull those normalized fields into a portfolio reporting layer. You lose some elegance and gain most of the value, because the thing you actually needed was comparable numbers, not one login.
Cluster consolidation
You group companies by sales motion, standardize within each cluster, and report across clusters. This tends to be the pragmatic middle for a diversified portfolio, and it matches how add-ons usually arrive, in related-business waves rather than one at a time.
Choose the posture deliberately. McKinsey’s work on private capital and operations repeatedly stresses that standardization delivers value only where the underlying processes are actually similar. Forcing a common tool onto genuinely different motions destroys adoption, and a CRM with no adoption is worse than the spreadsheet it replaced, because now the reports look official and are wrong.
3. Fix the definitions before you touch the tools
The single highest-return step in CRM consolidation for portfolio companies is not migration. It is agreeing on definitions. If a “qualified opportunity” means one thing in Company A and something looser in Company B, then any rolled-up pipeline number is fiction, no matter how many systems you merge.
Get the operating partner and the revenue leaders in a room and settle these, in writing, as portfolio standards:
- Lead, MQL, SQL, and opportunity, with the entry criteria for each.
- The sales stages, with an exit criterion per stage that is observable, not a feeling.
- How pipeline is dated and weighted, and what “commit” versus “best case” mean.
- The close date convention, and how you handle push-outs so forecast slippage is visible.
- Product or segment taxonomy, so cross-sell and mix analysis is possible later.
This is unglamorous and it is where the money is. Once definitions are common, even a federated approach with different tools produces comparable numbers. Skip it and you can spend six figures on a migration and still not be able to answer the board’s pipeline question, because the fields will be consistent and the meanings will not.
4. Sequence the work against the hold, not against the vendor’s roadmap
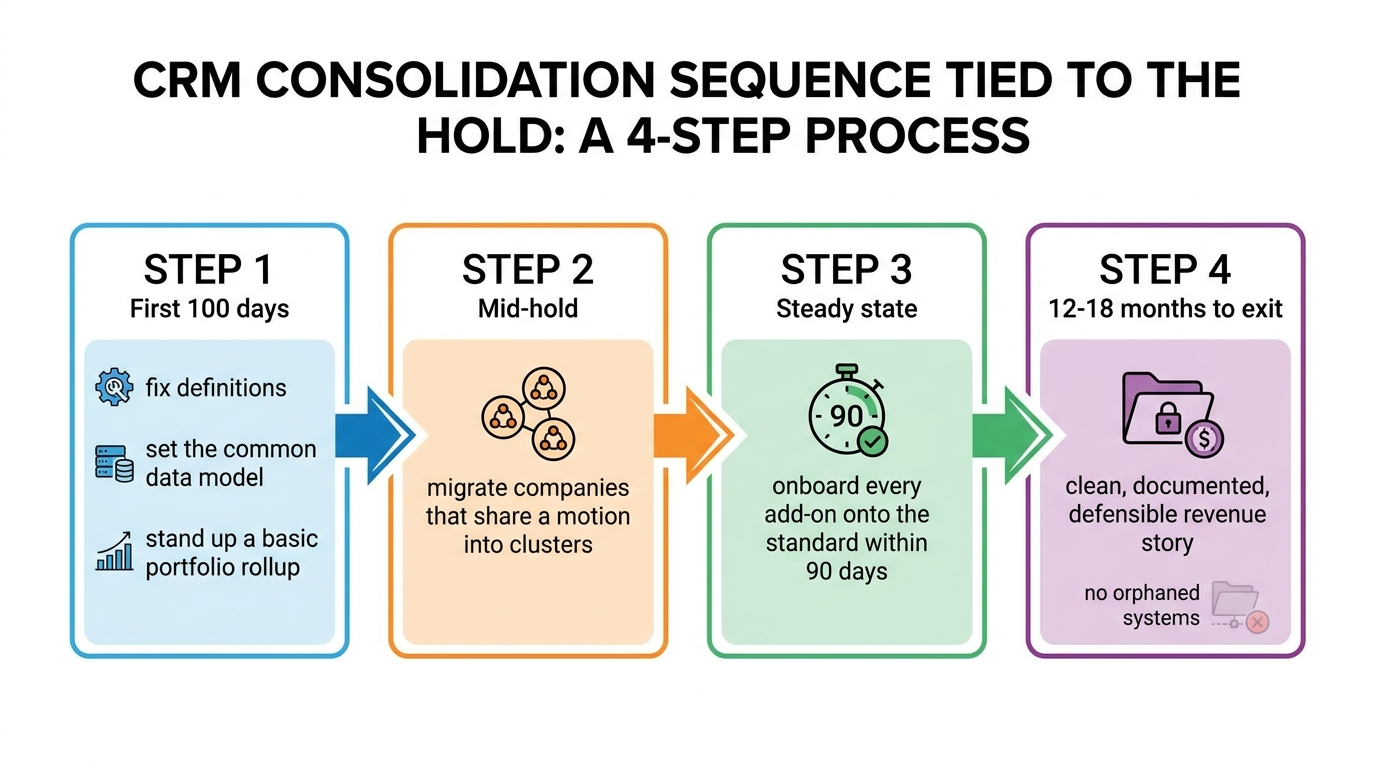
When you do this matters as much as how. Tie the sequence to real deal triggers, because that is what the board is watching.
During the first 100 days
New platform, or a newly acquired add-on, is the right moment to set the data model and reporting baseline. You will never have more license to change process than in the first 100 days. Use it to install common definitions and a basic portfolio rollup, even if migration itself comes later. Establishing the baseline early means you can measure improvement against it rather than arguing about it in month twenty.
Mid-hold
This is when full migrations belong, once you have proof the definitions hold and you know which companies share a motion. Doing a large migration in the first quarter, before you understand the businesses, is how projects overrun and management loses faith.
Approaching exit
Twelve to eighteen months out, the priority shifts to a clean, defensible revenue story. A buyer wants to see consistent pipeline reporting, a documented sales process, and no orphaned systems. As the analysis of how longer hold periods move the value creation burden to the operator lays out, the operator now owns the revenue narrative that used to be the deal team’s to tell, and a fragmented CRM stack undercuts it.
PitchBook’s research on deal activity shows how add-on-heavy strategies dominate mid-market platforms, which means most portfolios face a continuous stream of new systems arriving, not a one-time cleanup. Sequence for a repeatable onboarding, not a hero migration.
5. Judge the platform decision on the right criteria
You have budget and you are not learning the category, so I will skip the tool tour. What matters is the decision frame. Judge a target platform against these, in this order of weight:
Fit to the actual sales motion
Enterprise-deal businesses need strong opportunity and account management; high-volume transactional businesses need automation and speed. A platform that is excellent for one is often mediocre for the other. Fit beats brand.
Data portability and openness
You will migrate again. You will acquire. Judge how easily data comes out, not just how nicely it goes in. A closed system that traps your data raises your switching cost at the worst possible moment, which is exit diligence.
Total cost across the portfolio
Per-seat pricing multiplied across every company, plus the admin cost of keeping instances configured, is the real number. A cheaper per-seat tool that needs a dedicated admin per company is not cheaper.
Reporting and integration surface
Can it feed a portfolio-level rollup without heroics? Can it integrate with the finance stack so pipeline connects to actuals? This is where the operating partner’s real question gets answered.
Do not let a platform choice be made by the loudest revenue leader or by whoever’s tool happens to be incumbent. The decision right belongs to whoever owns the portfolio-wide revenue view, informed by the businesses, not captured by any one of them.
6. Get the data migration right, because this is where projects die
Most CRM consolidations do not fail on strategy. They fail on data. A dirty migration produces a shiny new system that management does not trust, and once trust is gone you will not get it back cheaply.
Insist on a disciplined sequence:
- Audit and profile the source data before migrating anything. Know your duplicate rate, your fill rate on key fields, and how much of the pipeline is stale.
- Decide the archive line. You do not need to migrate every closed deal from six years ago. Migrate what supports reporting and active relationships; archive the rest somewhere retrievable.
- Deduplicate and normalize against the common definitions from section 3, not after the fact.
- Run a parallel period where the old and new systems both hold live data, and reconcile the pipeline number between them. If they do not reconcile, you are not ready to cut over.
- Cut over on a clean date with a documented rollback, and communicate it as a hard line so nobody keeps updating the old system.
The reconciliation step is the one people skip and the one that saves you. If new-system pipeline does not match old-system pipeline within a tight tolerance, something in your mapping is wrong, and you want to find that before the board does.
7. Treat adoption as the real deliverable
A CRM is only worth what its users actually put into it. You can buy the best platform, migrate cleanly, and still end up with garbage data because the sales team routes real deals around the system. Adoption is not a training event. It is a design and incentive problem.
Design for the rep’s workflow, not the report
If updating an opportunity takes twelve fields and four clicks, reps will not do it, and the data will rot. Minimize required fields to what the forecast genuinely needs. Every field you demand is a tax on adoption, so charge it only where the return is real.
Make the system the only path
Forecasts, comp, and deal reviews all run off the CRM, or they do not. If a sales manager can still forecast from a private spreadsheet, that spreadsheet becomes the source of truth and your platform becomes decorative. Close the side doors.
Measure adoption directly
Track the percentage of closed-won revenue that had a complete opportunity record, the lag between a real-world stage change and its system update, and the share of forecast that reconciles to CRM pipeline. These are leading indicators. If adoption metrics are strong, the reporting will follow.
When you evaluate outside help for this, the questions worth asking overlap heavily with the ones in this guide on what private equity should ask a RevOps consultant. A partner who talks only about the platform and not about adoption and definitions is selling you activity, not the outcome you need.
8. Build the portfolio reporting layer that answers the board’s question
This is the payoff. Whichever consolidation posture you chose, the goal is a rollup that lets the operating partner see, on demand:
- Combined pipeline by stage, weighted and unweighted, with company-level drill-down.
- Conversion rates by stage, comparable across companies because the stages mean the same thing.
- Sales cycle length and its trend, so deceleration shows up before it hits bookings.
- New-business versus expansion versus renewal, split consistently.
- Forecast versus actual, tracked over time so you learn which management teams forecast reliably.
That last one is quietly the most valuable output. A board that can see, quarter after quarter, which companies hit their forecast and which routinely miss learns whom to trust and where to intervene. That is management visibility converted into a decision, which is exactly what the consolidation was for.
The AICPA and CIMA’s guidance on finance and reporting is a useful anchor here: the reporting layer should tie cleanly to how finance records revenue, so pipeline and actuals speak the same language. A CRM rollup that finance cannot reconcile to the P&L is a second set of books, and boards do not thank you for that.
9. Connect the CRM story to the exit narrative
Consolidated CRM data does more than run the business. It underwrites the story you tell a buyer. When you approach a sale, or a GP-led continuation vehicle that extends the hold, the quality of your revenue evidence directly affects how a buyer prices growth durability.
A buyer’s diligence team will probe: is the pipeline real or padded, how repeatable is new-business generation, how dependent is revenue on a few relationships, and can the go-to-market be integrated. Clean, consistent, well-adopted CRM data lets you answer with evidence instead of assertion. Fragmented data forces the buyer to assume the worse case and discount for the uncertainty, which is a direct hit to your multiple.
The Harvard Law School Forum on Corporate Governance regularly publishes analysis of deal diligence and disclosure that reinforces a simple point: information quality reduces perceived risk, and reduced perceived risk supports price. Your CRM is part of that information quality. Harvard Business Review’s work on integration makes the parallel case that go-to-market integration is where a lot of deal value is won or lost, and you cannot integrate what you cannot measure consistently.
10. Watch the risks that turn this into a value destroyer
CRM consolidation can absolutely destroy value if run badly. Keep these on the risk register from day one:
Business disruption during migration
If a cutover breaks how the sales team works during a critical quarter, you can lose real deals to save reporting elegance. Never cut over a healthy business at its busiest moment.
Over-standardization
Forcing genuinely different businesses onto identical process crushes the ones whose motion did not fit. The federated posture exists precisely to avoid this. Comparability of numbers does not require identical process.
Key-person data hostage situations
When one manager guards the real pipeline in a private file, consolidation threatens their leverage and they may resist. Handle it as a management issue, not a technical one, and make the system the only sanctioned source before you take anything away.
Cost creep and scope drift
These projects expand. Every integration and custom field looks reasonable in isolation. Anchor scope to the commercial problems from section 1 and refuse work that does not trace to one of them.
The stakes scale with your thesis. In a carve-out, the divested unit often arrives with no standalone CRM at all, sharing systems with the parent, and standing that up cleanly is part of the value case, not an afterthought. The BCG research on principal investors and operations underscores that integration execution, not deal thesis, is where a large share of promised synergies slip away.
11. A checklist you can take into the board meeting
Here is the decision and judgment checklist, compressed. If you can answer all of these, you have a real plan rather than a vendor’s proposal.
- Problem framed commercially? You can state the specific board-level decisions the current CRM sprawl blocks.
- Posture chosen deliberately? Full, federated, or cluster, matched to how similar the sales motions actually are.
- Definitions agreed and written? Lead, qualified opportunity, stages, close date, and taxonomy standardized across the portfolio before any migration.
- Sequenced to the hold? Baseline in the first 100 days, migrations mid-hold, clean story before exit.
- Platform judged on fit, portability, total cost, and reporting surface, with a clear decision owner.
- Migration disciplined? Audit, archive line, dedupe, parallel run, reconciled pipeline, clean cutover with rollback.
- Adoption designed and measured? Minimal required fields, no side doors, adoption tracked directly.
- Reporting layer answers the operating partner’s questions and reconciles to finance.
- Exit narrative supported? Data quality strong enough to answer diligence with evidence.
- Risks on the register? Disruption, over-standardization, key-person data, and scope creep all owned.
Two more sources worth keeping close as you build the plan: S&P Global Market Intelligence’s private markets data is useful for benchmarking where the portfolio sits on operating maturity, and Preqin’s alternative assets research helps frame how peers are treating operational value creation. Both keep the conversation grounded in enterprise value rather than tooling preference.
12. What good looks like, six months in
You should not need a year to know whether this is working. Roughly six months after you set the common data model, a healthy consolidation looks like this: the operating partner gets a combined pipeline number without a manual rebuild, conversion rates are comparable across companies because the stages mean the same thing, new add-ons onboard onto the standard within a quarter, and forecast-to-actual variance is trending down because management teams can see their own gaps sooner.
If instead you have a new platform, a big invoice, and reports nobody trusts, the failure is almost always upstream of the tool: definitions were never agreed, adoption was never designed, or the posture was wrong for the businesses. Those are fixable, but only if you name them honestly rather than blaming the software.
CRM consolidation for portfolio companies is a revenue-visibility decision wearing a systems costume. Treat it as the operating lever it is, tie every choice back to the commercial problem and the exit story, and it becomes one of the more reliable ways to convert scattered activity into a number the board can actually use. Whether you are pursuing a growth-oriented or a buyout thesis, the requirement is the same: know your revenue, prove it, and integrate it faster than the next owner could.
If you want a partner to run this as a scoped engagement, from common definitions through migration and the portfolio reporting layer, our RevOps and private equity execution team builds exactly this for portfolio companies. Bring us the sprawl and the board’s unanswered question, and we will hand back a governed revenue view you can defend at exit.