
You have a platform company performing at plan. The investment thesis calls for three to five add-on acquisitions over the hold period. Now a target surfaces: similar end-market, decent EBITDA, founder ready to exit. The deal team wants to move fast. But speed without structure is how platforms absorb margin-dilutive assets, integration chaos, and customer defection they never modeled.
An add-on acquisition looks simple on a pitch deck. In practice, every bolt-on either compounds the platform’s competitive position or drains operating capacity from the core business. The difference sits in the diligence you run before signing, not the synergy assumptions you inherit from the seller’s banker.
This guide walks through the evaluation framework SME operators and deal teams need when screening add-on acquisitions. We cover thesis alignment, commercial overlap, systems capacity, integration cost, synergy evidence, and post-close measurement. At the end, you will find a usable add-on acquisition scorecard you can apply to your next target today.
What Qualifies as an Add-On Acquisition
An add-on acquisition is a smaller company purchased to strengthen an existing portfolio company, often called the platform. The target typically shares an end-market, customer segment, geographic footprint, or capability with the platform. Unlike a standalone acquisition, an add on acquisition assumes integration into existing operations rather than parallel management.
Add-on acquisitions are the engine behind buy-and-build strategy in private equity. According to Bain & Company’s 2024 Global Private Equity Report, add-ons represented 72% of all PE-backed deals in North America, up from 40% two decades ago. The thesis is straightforward: acquire smaller targets at lower multiples, integrate them onto a scaled platform, and capture margin expansion through procurement leverage, customer cross-sell, and overhead consolidation.
The risk is equally straightforward. A poorly selected add-on consumes management attention, introduces system fragmentation, and delivers synergies that exist only in the model. For SME operators evaluating potential targets, the screening process must be rigorous before the LOI goes out, not after.
Why the Add-On Must Strengthen the Platform Thesis
Every add-on acquisition should answer one question before anything else: does this target make the platform more valuable to its customers or more defensible against competitors? If the answer requires three paragraphs of explanation, the deal probably fails the thesis test.
Thesis Alignment Is Not Product Adjacency
A common mistake is confusing product adjacency with strategic fit. The target sells software to the same buyers. The target operates in a neighboring geography. These facts describe market proximity, not thesis alignment. Thesis alignment means the combined entity creates value that neither company could create independently.
Consider the difference between two scenarios. In the first, your platform sells HVAC maintenance contracts to commercial building owners, and the target sells plumbing maintenance contracts to the same owners. The thesis: cross-sell existing relationships, consolidate field operations, and become the single-vendor solution buyers prefer. That alignment is concrete.
In the second scenario, your platform sells HVAC maintenance and the target sells HVAC equipment. Different sales cycles, different buyer personas within the same account, different margin profiles. The adjacency is obvious. The integration path is not.
Questions to Score Thesis Fit
When screening a target, score these questions on a 1-5 scale:
- Does the target serve customers the platform already serves or could serve with existing sales capacity?
- Can the platform deliver the target’s offering through existing operations without material new investment?
- Does the acquisition close a competitive gap or create a capability competitors cannot easily replicate?
- Will customers perceive the combination as more valuable, or will they see it as irrelevant bundling?
If the average score falls below 3, the deal may still make financial sense as a multiple arbitrage play. But do not call it strategic. Strategic add-ons strengthen the platform in ways that persist beyond the current ownership period.
Commercial Overlap and Customer Concentration
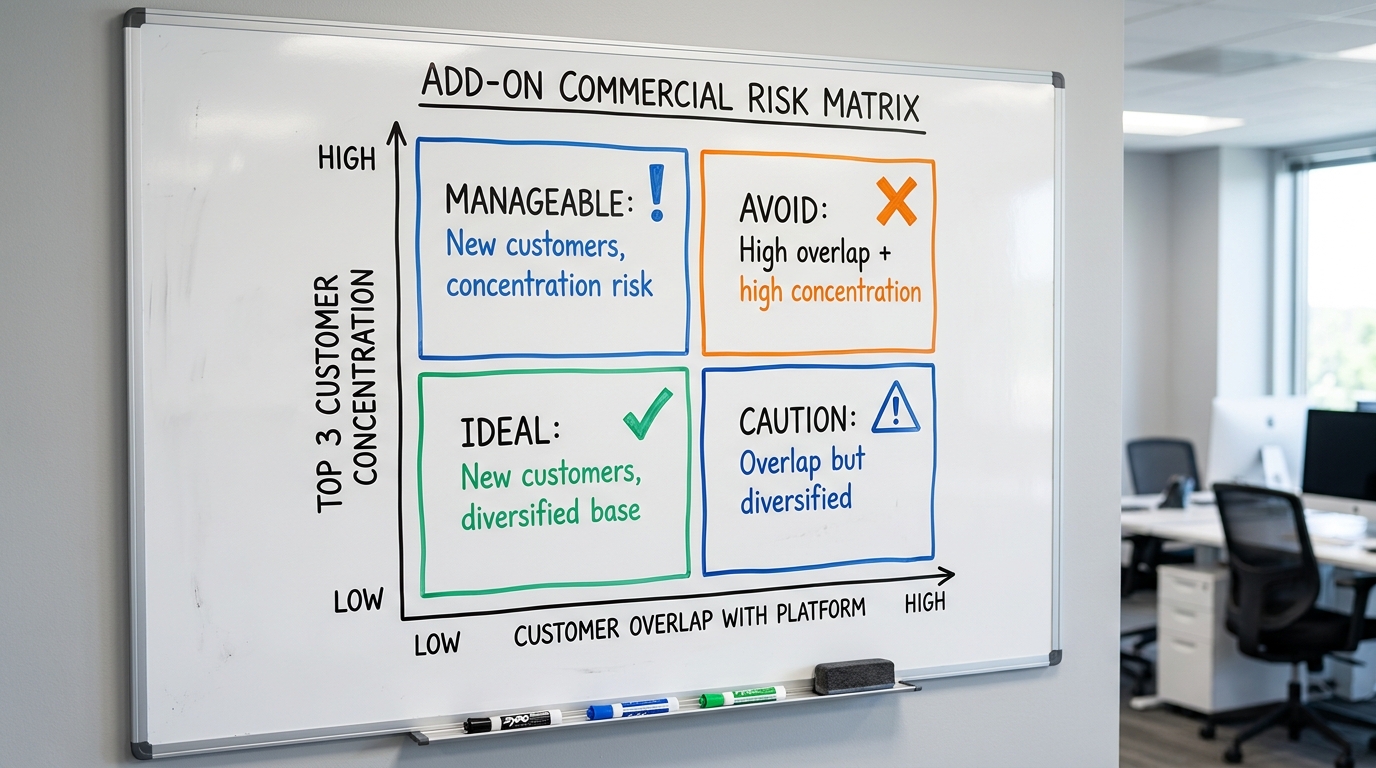
Commercial diligence on an add-on acquisition must answer two questions the seller’s CIM will not emphasize: how much revenue actually overlaps, and how concentrated is the target’s customer base?
Revenue Overlap Can Destroy the Model
If the target and platform share significant customers, you need to understand whether the revenue stacks or cannibalizes. I have seen deals where 30% of the target’s revenue came from accounts the platform already served. The cross-sell thesis evaporated because the platform was already wallet-maximized in those accounts. The deal closed anyway. The synergy model never recovered.
Request customer-level revenue data during diligence. Match it against platform accounts. Calculate overlap as a percentage of target revenue. Any overlap above 15% requires a clear theory for why combined wallet share will grow, not just redistribute.
Customer Concentration Creates Integration Risk
According to McKinsey’s M&A research, customer concentration is among the top three value-destruction risks in small-company acquisitions. A target with 40% of revenue from two accounts is not a business; it is two contracts with overhead attached.
Concentration risk compounds in add-on M&A because the platform often lacks relationships with the target’s key accounts. If those accounts leave post-close, the platform absorbs the target’s cost base without the revenue that justified it. During diligence, verify contract terms, renewal dates, and buyer sentiment for any account exceeding 10% of target revenue.
Your M&A due diligence checklist should include specific line items for overlap analysis and concentration scoring.
Systems, Reporting, and Leadership Capacity
Add-on acquisitions fail in operations more often than they fail in strategy. The target looked good on paper. The integration revealed that “paper” meant Excel files emailed monthly, a founder who was also the only salesperson, and a technology stack that cannot connect to anything.
Systems Readiness Determines Integration Speed
Before signing, inventory the target’s core systems: ERP, CRM, accounting, HR/payroll, and any industry-specific operational software. For each system, answer three questions:
- Is the system compatible with platform infrastructure, or does it require replacement?
- Is data exportable in formats the platform can ingest?
- Who owns system administration, and will that person remain post-close?
System replacement is expensive and slow. According to Gartner research, mid-market ERP implementations average 14-22 months and frequently exceed budget by 30% or more. If your integration plan assumes system consolidation in the first 100 days, you are building a fantasy. Set the expectation with the deal team early on what the first 100 days should actually produce: a single source of truth for orders and customers, 1 reporting pack, and a dated plan for the systems that will take longer. Full consolidation belongs in month 9 or later on most add-ons.
Reporting Quality Reveals Operational Maturity
Ask for the target’s last six monthly management reports during diligence. Not the board decks; the operating reports the leadership team uses to run the business. What you receive tells you more about integration complexity than any management interview.
If the reports arrive as well-structured dashboards with consistent KPIs, the target has operational discipline. If you receive PDF exports of disconnected spreadsheets with inconsistent date ranges, expect to rebuild reporting from scratch post-close. Neither outcome is disqualifying. Both must be priced into the integration budget.
Leadership Capacity Is Often Negative
Small-company founders often lack the operational skills needed in a platform subsidiary. That gap is manageable if your platform has bench strength to backfill. If the platform is already running lean, absorbing a target that requires new management means pulling attention from the core business.
Score leadership capacity honestly. Can the target’s team run their business independently for 6-12 months while integration proceeds? Or does Day 1 require platform executives to step in? The second scenario is not wrong, but it has a cost that belongs in the model.
Integration Cost and Timing
Every add-on acquisition model includes a line for integration costs. In my experience, that line is wrong by a factor of two or more roughly half the time. The error is not malicious; it results from optimistic assumptions about what integration actually requires.
The Real Categories of Integration Cost
Integration cost falls into five categories, and most models only capture two:
- Technology and systems: Software licenses, data migration, custom integrations, and the consultants who execute them.
- People and organization: Severance for redundant roles, retention bonuses for critical talent, recruiting costs for gaps.
- Facilities and operations: Lease terminations, equipment moves, facility buildouts.
- Revenue dissynergy: Customer churn during transition, sales productivity loss, price renegotiations with combined accounts.
- Management attention: The opportunity cost of platform leadership spending 30% of their time on integration instead of growth.
The fourth and fifth categories rarely appear in models. They should. Revenue dissynergy is real: Deloitte’s M&A research finds that acquirers underestimate revenue loss by an average of 25% in their integration models. Management attention has no line item but determines whether the platform misses plan while integrating.
Timing Shapes Everything
Integration timing interacts with the platform’s operating rhythm. Closing an add-on acquisition in Q4 means integrating during budget season. Closing in Q1 means the target’s team joins during the platform’s busiest selling period. Neither is automatically wrong, but both require planning.
Map the integration timeline against platform milestones: board meetings, product launches, contract renewals, audit periods. Identify conflicts early. A target that looks attractive in May may become operationally reckless if it closes in November.
For detailed guidance on technology and data integration, see the operator’s integration tools for CRM, martech, and web properties.
Synergy Evidence to Demand Before Signing
Synergy is the most abused word in M&A. Every deal model projects cost synergies from headcount consolidation and revenue synergies from cross-sell. Rarely do those projections include evidence that the synergies will actually occur.
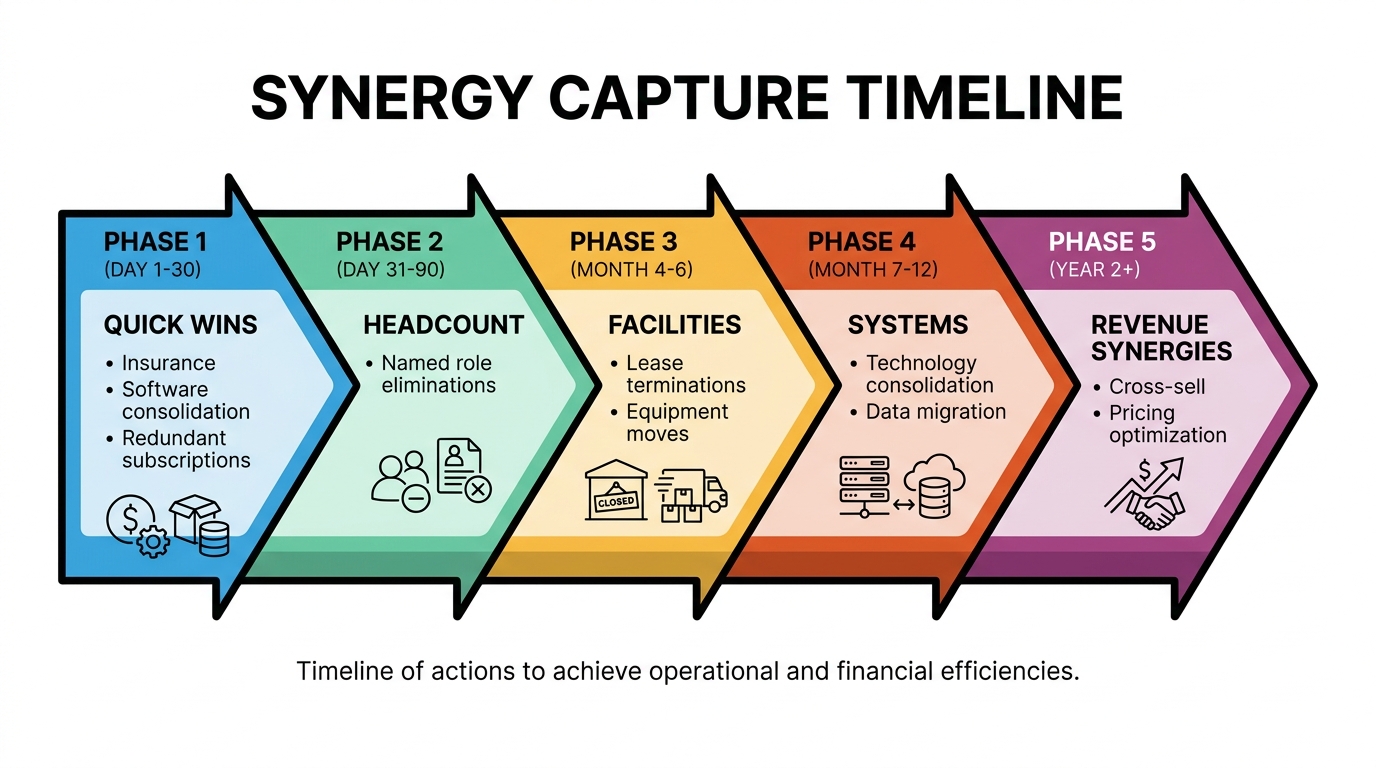
Cost Synergies Require Named Roles and Dates
A cost synergy model that says “reduce corporate overhead by $400K” is a wish. A model that says “eliminate target CFO role ($180K, Day 90), consolidate to platform accounting team ($0 incremental), terminate target office lease ($85K, Month 6), consolidate insurance policies ($45K, Day 30)” is a plan.
Before signing, require the deal team to name every cost synergy by line item, amount, owner, and target date. If a synergy cannot be named, it cannot be managed. If it cannot be managed, it probably will not happen.
Revenue Synergies Require Customer-Level Evidence
Revenue synergy models typically assume cross-sell rates that have no basis in customer behavior. “We’ll sell the target’s product to 20% of platform customers in Year 1” sounds reasonable until you ask: which customers? Have we validated demand? What is the sales motion?
Demand evidence before signing. Interview a sample of platform customers about the target’s offering. Would they buy it? At what price? Through which channel? If the cross-sell thesis depends on customers behaving differently than they do today, model it at half the assumed rate.
Harvard Business Review’s research on M&A synergies found that only 30-40% of projected synergies are captured in a typical deal. That statistic should inform your assumptions.
Post-Close Measurement
An add-on acquisition is not complete at close. The deal succeeds or fails based on execution over the following 12-24 months. Without a measurement framework established before signing, you will never know whether the deal delivered what the model promised.
Define the Metrics Before Close
Before signing, agree on the metrics that will define success. These should map directly to the deal thesis:
- Financial metrics: Revenue retention, EBITDA margin, synergy capture rate, integration cost vs. budget.
- Operational metrics: System consolidation milestones, headcount targets, facility transitions.
- Customer metrics: Retention rate for top accounts, cross-sell penetration, NPS or satisfaction scores.
- People metrics: Key talent retention, employee satisfaction, voluntary turnover.
For each metric, establish a baseline (current state), a target (expected state at Month 6, Month 12), and an owner responsible for reporting progress.
Build the Reporting Cadence Now
Post-close reporting often gets deprioritized because everyone is exhausted from diligence. Build the reporting cadence into the integration plan before close. Weekly integration standups for the first 90 days. Monthly synergy tracking thereafter. Quarterly reviews against the original deal model.
The discipline of measurement changes behavior. When integration owners know their synergy capture will be reviewed monthly, they execute differently than when the model sits in a folder until the next board meeting.
If you are building a programmatic acquisition strategy, your private equity market intelligence should include benchmarks for typical integration timelines and synergy capture rates.
How Add-On Scoring Differs from Platform Diligence
Add-on acquisitions require different diligence priorities than platform investments. The distinction matters because deal teams sometimes apply the same framework to both, missing risks specific to bolt-on deals.
Standalone Viability Matters Less
In a platform acquisition, you evaluate whether the business can succeed independently. In an add-on acquisition, standalone viability is less important than integration potential. A target that would struggle as an independent company may be highly attractive as a bolt-on if its customers, capabilities, or geography complement the platform.
This difference cuts both ways. A strong standalone business may be a poor add-on if integration complexity is high or strategic fit is weak. Score for fit, not just quality.
Integration Capability of the Platform
Platform diligence asks: can this business execute its strategy? Add-on diligence must also ask: can the platform absorb this acquisition without degrading its own performance?
If the platform has already completed two add-ons in the past 12 months and is still integrating both, a third add-on creates compounding risk. Integration capacity is finite. Score the platform’s readiness alongside the target’s attractiveness.
Understanding how add-on M&A fits within broader consolidation plays can inform your screening criteria. For context on programmatic acquisition approaches, review private equity roll-up strategy fundamentals.
The Add-On Acquisition Scorecard
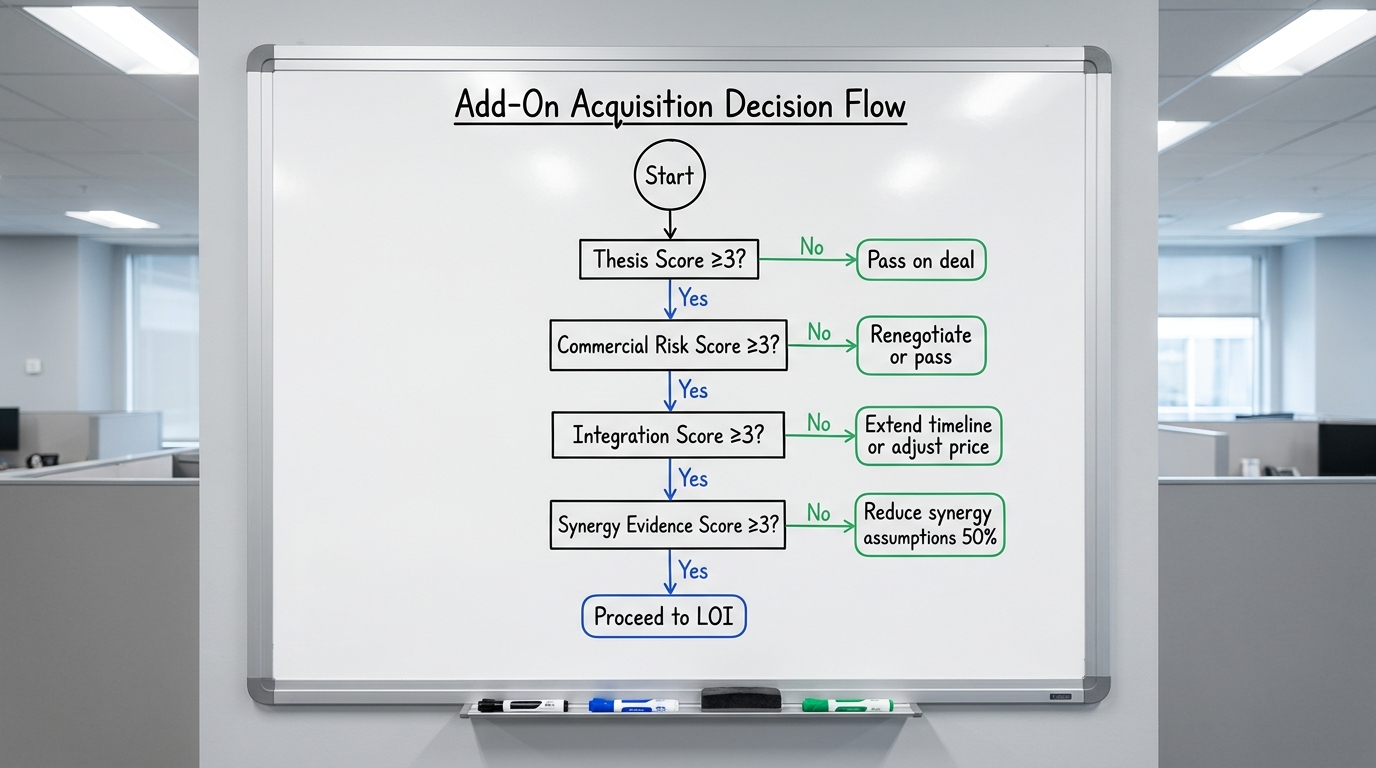
Below is a usable scorecard for evaluating add-on acquisitions. Score each criterion on a 1-5 scale, where 1 = significant concern, 3 = acceptable, and 5 = strong. Weight categories based on your platform’s priorities. A weighted average below 3.0 suggests the deal requires substantial additional diligence or restructuring before proceeding.
| Category | Criterion | Score (1-5) | Weight | Notes |
|---|---|---|---|---|
| Thesis Alignment | Target serves customers platform already serves or could serve | 1.5x | ||
| Platform can deliver target offering with existing operations | 1.5x | |||
| Acquisition closes competitive gap or creates defensible capability | 1.0x | |||
| Customers will perceive combination as more valuable | 1.0x | |||
| Commercial Risk | Customer overlap below 15% of target revenue | 1.5x | ||
| Top 3 customers represent less than 30% of target revenue | 1.5x | |||
| Key customer contracts extend beyond 12 months post-close | 1.0x | |||
| Systems & Operations | Core systems compatible or easily replaceable | 1.0x | ||
| Data exportable in usable formats | 1.0x | |||
| Management reports exist and show operational discipline | 1.0x | |||
| Leadership | Target team can operate independently for 6-12 months | 1.5x | ||
| Platform has capacity to support integration without degrading core | 1.5x | |||
| Integration | Integration costs fully scoped across all five categories | 1.0x | ||
| Timeline avoids major platform operational conflicts | 1.0x | |||
| Revenue dissynergy modeled conservatively | 1.0x | |||
| Synergy Evidence | Cost synergies named by line item, amount, owner, and date | 1.5x | ||
| Revenue synergies supported by customer-level evidence | 1.5x | |||
| Measurement | Success metrics defined with baselines and targets | 1.0x | ||
| Reporting cadence built into integration plan | 1.0x | |||
| Weighted Average Score | Calculate: (Sum of Score × Weight) / (Sum of Weights) | |||
Interpretation:
- 4.0-5.0: Strong candidate. Proceed to confirmatory diligence.
- 3.0-3.9: Acceptable with conditions. Address low-scoring areas before signing.
- 2.0-2.9: Significant concerns. Restructure deal terms or walk away.
- Below 2.0: Do not proceed.
Common Mistakes in Add-On Screening
After reviewing dozens of add-on acquisitions across multiple sectors, certain mistakes appear repeatedly. Avoiding these patterns improves screening accuracy.
Trusting the Seller’s Synergy Model
Seller advisors build models that make the deal look attractive. That is their job. Your job is to rebuild the synergy case from platform data, not seller assumptions. Every synergy should be validated independently before it enters your model.
Underweighting Integration Cost
BCG’s research on M&A execution found that 70% of deals fail to achieve expected synergies, and integration cost underestimation is a leading cause. Add 30-50% to your initial integration budget, then defend that number against pressure to reduce it.
Ignoring Platform Capacity
A great target at the wrong time is still a bad deal. If platform leadership is already stretched, adding integration workload compounds risk. Score the platform, not just the target.
Skipping Customer Validation
The cross-sell thesis is speculation until you talk to customers. Five customer interviews during diligence can save you from synergies that exist only in the model.
When to Walk Away
Not every add-on opportunity should become an add-on acquisition. Discipline in walking away from weak targets preserves capital and capacity for better opportunities.
Walk away when:
- Customer concentration exceeds 40% in the top three accounts and those customers have not been validated.
- The target’s systems require full replacement, and the platform lacks integration budget or expertise.
- The thesis requires behavior change from customers that has not been validated.
- Platform leadership cannot dedicate 20%+ of their time to integration for six months.
- The target’s management team is departing immediately, and the platform has no bench to backfill.
Walking away is not failure. It is discipline that protects the platform’s value and positions the team for the right deal when it appears.
Summary Checklist for Add-On Acquisition Screening
Before signing an LOI on any add-on acquisition, verify the following:
- ☐ Thesis alignment scored on 4 criteria; average score ≥3.0
- ☐ Customer overlap calculated as percentage of target revenue; documented
- ☐ Top customer concentration analyzed; contracts verified for renewal dates
- ☐ Core systems inventoried; compatibility assessed
- ☐ Management reports reviewed for operational maturity signals
- ☐ Target leadership capacity scored; platform bench strength confirmed
- ☐ Integration costs scoped across all five categories
- ☐ Integration timeline mapped against platform operating rhythm
- ☐ Cost synergies named by line item, amount, owner, and date
- ☐ Revenue synergies validated through customer interviews
- ☐ Success metrics defined with baselines, targets, and owners
- ☐ Post-close reporting cadence built into integration plan
- ☐ Weighted scorecard completed; average score documented
Deals that pass this checklist have a materially higher probability of achieving their modeled outcomes. Deals that skip it often become the stories told at portfolio company reviews about what went wrong.
Subscribe to the Growth Shuttle research briefing for add-on screening insights, and download the Add-On Acquisition Scorecard to apply this framework to your next target today.