
When a fund has $400 million in dry powder and twelve months before LPs start asking uncomfortable questions, the quality of inbound opportunities matters more than the volume. Yet most deal teams still measure pipeline health by counting teasers received rather than assessing whether those opportunities match their investment thesis, timing requirements, and value-creation capabilities.
Private equity deal flow is not a volume problem. According to Bain’s 2024 Global Private Equity Report, the industry held approximately $2.6 trillion in dry powder at the start of 2024. The issue is not finding deals. The issue is finding the right deals at the right price with the right sellers at the right time.
This guide breaks down what constitutes quality deal flow, where investable opportunities actually originate, how market conditions shape both supply and demand, and how to distinguish signal from noise when evaluating pipeline health. The goal is practical: a framework for assessing whether your deal flow supports your fund’s deployment timeline and return requirements.
1. Defining Deal-Flow Quality Over Volume
Deal flow, in its simplest form, refers to the stream of investment opportunities that reach a private equity firm for consideration. But this definition obscures the distinction that matters most: not all opportunities are created equal, and more is not better if the additional volume dilutes focus or consumes diligence capacity on unsuitable targets.
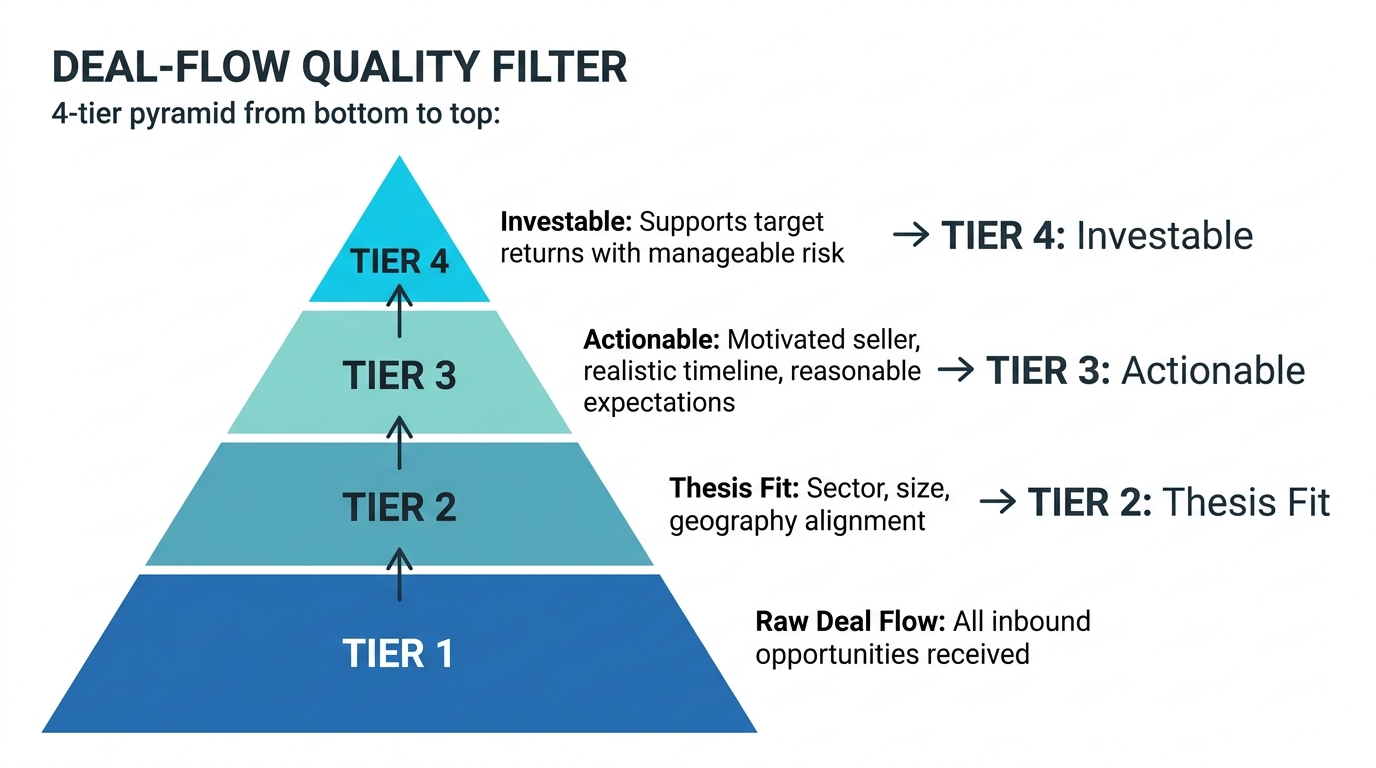
Quality deal flow has three characteristics. First, the opportunities align with the fund’s investment thesis, meaning they fit sector focus, size parameters, geographic constraints, and value-creation approach. Second, the opportunities are actionable, meaning the seller is genuinely motivated, the timeline is realistic, and the valuation expectations are within range. Third, the opportunities offer a defensible path to returns, meaning the business fundamentals, competitive position, and improvement levers support the underwriting case.
A fund receiving 200 teasers per month with a 1% conversion to LOI has worse deal flow than a fund receiving 40 teasers with a 10% conversion rate, even though the absolute numbers look similar. The first fund is spending diligence resources on opportunities that do not fit. The second fund has a pipeline that matches its criteria.
The Quality Metrics That Matter
Measuring deal-flow quality requires tracking metrics beyond volume. Useful indicators include:
- Thesis alignment rate: What percentage of inbound opportunities fit the fund’s stated investment criteria?
- Actionability rate: Of those that fit, what percentage have motivated sellers with realistic timelines?
- Conversion to LOI: What percentage of reviewed opportunities result in a letter of intent?
- Conversion to close: What percentage of LOIs result in completed transactions?
- Source yield: Which origination channels produce the highest-quality opportunities?
These metrics shift the conversation from “how busy is the deal team” to “how effective is our origination strategy.”
Where middle market private equity opportunities actually come from
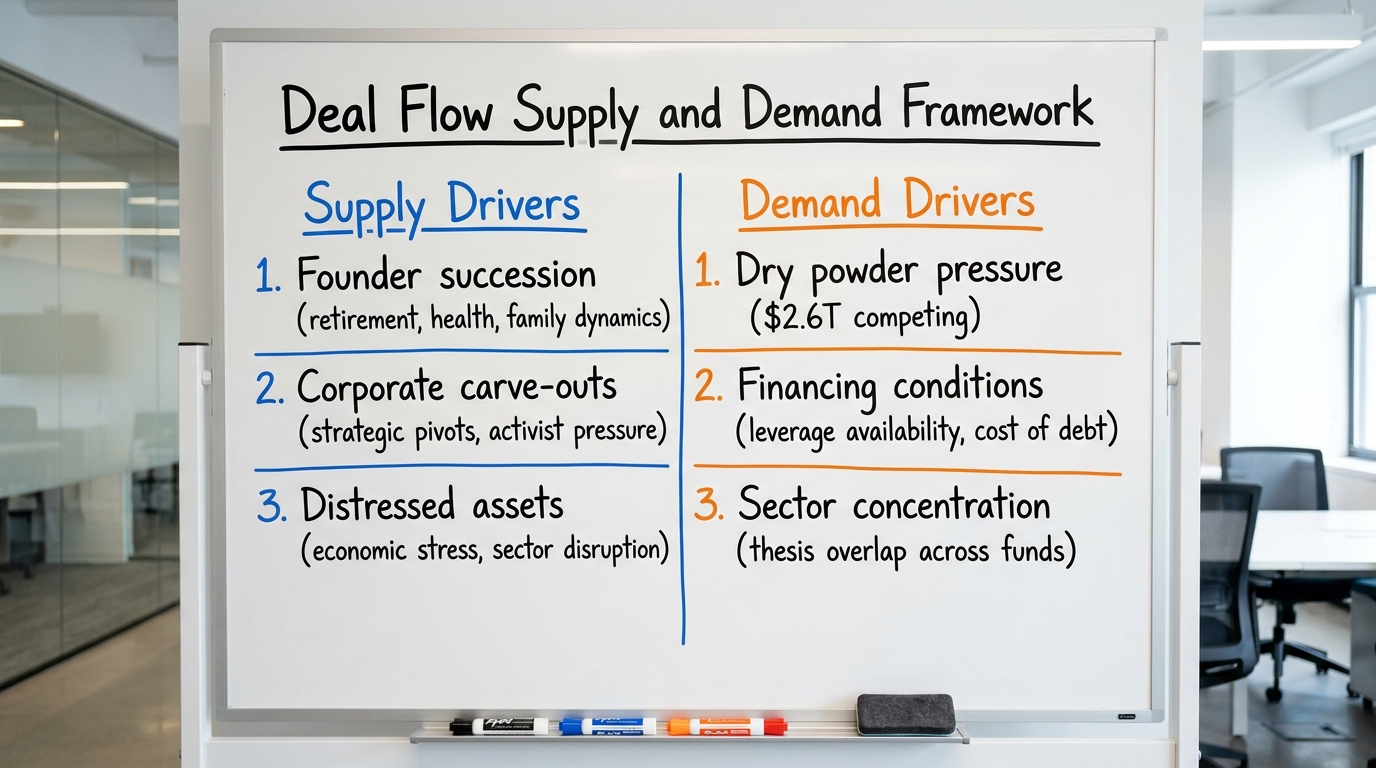
Understanding where middle market private equity opportunities come from helps explain why deal flow varies in quality and timing. Three primary sources dominate the supply of businesses available for acquisition.
Founder and Ownership Succession
The largest source of middle-market deal flow comes from founders and owners seeking liquidity or transition. According to McKinsey research on private equity value creation, ownership transition remains the primary catalyst for middle-market transactions.
These opportunities arise when founders approach retirement age, when family dynamics complicate succession, when growth requires capital beyond the owner’s risk tolerance, or when health or personal circumstances accelerate timing. The quality of these opportunities depends heavily on how well the business has been prepared for transition. Companies with documented processes, professional management teams, and clean financials present differently than founder-dependent businesses with informal operations.
Corporate Carve-Outs and Divestitures
Large corporations periodically divest business units that no longer fit their strategic focus. These carve-outs represent a distinct deal-flow category with specific characteristics. The businesses often have institutional infrastructure, established customer relationships, and predictable financials. However, they may also carry stranded costs from corporate overhead, integration dependencies on the parent company, and organizational cultures that require adjustment to stand-alone operation.
Carve-out deal flow increases when corporations face activist pressure, when conglomerate discounts become severe, or when strategic pivots require capital reallocation. The quality of these opportunities depends on how cleanly the business can be separated and how realistic the seller’s expectations are regarding transition support.
Distressed and Underperforming Assets
Economic stress creates a third category of deal flow: businesses facing financial difficulty or performance challenges. These opportunities require specialized capabilities, including turnaround expertise, restructuring knowledge, and higher risk tolerance. The supply of distressed deal flow correlates with economic cycles, interest rate environments, and sector-specific disruptions.
For funds without specific distressed mandates, these opportunities often represent noise rather than signal. A services business struggling with margin compression due to labor costs requires different value-creation capabilities than a healthy business seeking growth capital. Filtering distressed opportunities requires clarity about the fund’s actual operational capabilities.
How dry powder, financing conditions, and sector focus shape competition for deals
Deal flow does not exist in isolation. The quality and pricing of available opportunities depend heavily on demand-side factors, specifically how much capital is competing for deals and under what financing conditions.
Dry Powder Pressure
The approximately $2.6 trillion in private equity dry powder documented by Bain creates competitive pressure on attractive opportunities. When multiple funds pursue the same target, valuations rise and terms favor sellers. This dynamic means that deal-flow quality depends partly on how many other buyers are evaluating the same opportunities.
Tracking private equity market trends helps contextualize whether current deal flow reflects a buyer’s market or a seller’s market. In periods of high dry powder and limited quality deal flow, conversion rates decline and pricing pressure increases.
Financing Conditions
Leverage availability directly affects deal economics and, by extension, which opportunities are investable. According to S&P Global data, leverage ratios on leveraged buyouts fluctuate with credit market conditions. When debt is expensive or scarce, deals that rely on financial engineering become less attractive, shifting demand toward opportunities with clear operational improvement potential.
Monitoring private credit trends provides context for which deal structures remain viable. A business that pencils at 6x EBITDA with cheap leverage may not work at 5x with expensive debt, meaning financing conditions filter what counts as quality deal flow.
Sector Focus and Thesis Alignment
Demand clusters around sectors perceived as resilient, growing, or undergoing consolidation. Technology-enabled services, healthcare services, and business services have attracted concentrated private equity interest, while retail, hospitality, and energy have seen more selective approaches.
When multiple funds target the same sectors, deal flow in those areas becomes simultaneously more abundant and more competitive. This dynamic rewards funds with differentiated sector expertise or proprietary origination channels that access opportunities before broad marketing.
What changes in proprietary versus brokered deal processes
One of the most consequential distinctions in deal flow is whether opportunities arrive through intermediaries or through direct origination. This distinction affects pricing, competition, timeline, and information quality.
Brokered Processes
Most middle-market private equity deals involve intermediaries, typically investment banks or M&A advisors who run structured sale processes. According to PwC’s Global M&A Industry Trends, intermediated processes remain the dominant channel for middle-market transactions.
Brokered processes have predictable characteristics. Multiple buyers receive the same information simultaneously. Timelines follow the intermediary’s schedule. Valuation expectations reflect competitive bidding. Information quality is controlled by the seller’s advisor. These processes favor buyers with efficient diligence capabilities and competitive financing.
The advantage of brokered deal flow is access to deal volume and market coverage without building extensive origination infrastructure. The disadvantage is competition, as every other fund with similar criteria receives the same materials.
Proprietary Origination
Proprietary deal flow refers to opportunities that reach a fund outside of competitive processes. This includes direct outreach to business owners, relationships with industry executives, referrals from portfolio company networks, and thematic research that identifies targets before they consider selling.
Funds pursuing a buy-and-build strategy often develop proprietary origination in specific verticals, using sector knowledge to identify and approach potential targets directly. This approach requires more investment in origination but can produce better pricing and less competition.
The distinction matters for deal-flow assessment. A pipeline heavily weighted toward brokered processes faces different dynamics than one with significant proprietary origination. Neither is inherently superior, but understanding the mix informs expectations about conversion rates and pricing.
5. Signals That an Opportunity Is Investable
Beyond source and sector, specific signals help distinguish investable opportunities from those that will consume diligence resources without reaching close. These signals span seller motivation, business fundamentals, and market positioning.
Seller Motivation and Timeline
An opportunity is only actionable if the seller genuinely intends to transact within a timeframe that works for the buyer. Signals of real motivation include:
- Clear articulation of why the seller is pursuing a transaction now
- Willingness to provide substantive information during initial evaluation
- Alignment between stated valuation expectations and recent comparable transactions
- Advisor engagement (if intermediated) with a defined process timeline
- Decision-maker availability for management presentations and diligence
Conversely, warning signs include exploratory conversations without committed timelines, valuation expectations far above market comparables, reluctance to share basic financial information, and unclear decision-making authority.
Business Fundamentals
Certain business characteristics indicate higher investability, meaning the opportunity can likely be underwritten to target returns with manageable risk. According to Harvard Business Review’s analysis of private equity success factors, consistent cash flow generation and identifiable value-creation levers distinguish successful investments.
Fundamental signals include:
- Recurring or predictable revenue with demonstrated retention
- Defensible market position with identifiable competitive advantages
- Management depth beyond a single founder or key person
- Clean financials with audited or auditable records
- Identifiable improvement opportunities that match the buyer’s capabilities
Market Position and Trajectory
A business operating in a growing market with secular tailwinds presents differently than one fighting headwinds. This does not mean cyclical or challenged businesses are never investable, but the underwriting case differs materially.
Signals of favorable positioning include market share gains, pricing power demonstrated through maintained or expanding margins, customer concentration below concerning thresholds, and competitive barriers that protect against commoditization.
5.5. Deal Flow Is Only Valuable If It Supports the Value Creation Plan
High-quality deal flow is not simply about finding businesses that can be acquired. It is about finding businesses where the fund has a credible path to creating value after closing.
Every attractive opportunity should be evaluated against the same question:
Can this company realistically deliver the operational improvements assumed in the investment thesis?
That requires looking beyond valuation and financial performance.
Investment teams increasingly assess whether the business already contains identifiable value-creation levers, including:
- pricing opportunities
- procurement improvements
- digital transformation
- operational efficiency
- commercial expansion
- bolt-on acquisition potential
A business with moderate current performance but several executable value-creation initiatives may represent a stronger investment than a high-performing company with little remaining upside.
This is why sophisticated deal sourcing increasingly incorporates operating perspectives before exclusivity. The objective is not simply to win the auction, but to identify companies where operational capabilities match the fund’s execution strengths.
In practice, the best deal flow is not the largest pipeline. It is the pipeline with the highest proportion of businesses that fit both the investment thesis and the fund’s value creation playbook. Judging that fit at screening requires someone who knows what the fund can actually execute. That knowledge sits in the portfolio operations function, which sees which levers landed in the last 5 deals and how long each took, and pulling it into the screen 2 weeks earlier changes which opportunities get diligence budget.
6. Countercase: Deal-Flow Abundance With Unattractive Underwriting
High deal-flow volume can coexist with poor investment conditions. This happens when the supply of opportunities expands without corresponding improvement in quality or when demand dynamics push pricing beyond reasonable levels.
When Volume Masks Quality Problems
Several scenarios produce high deal-flow volume with limited investable opportunities:
Valuation disconnects: Sellers anchor to peak-market multiples while buyers adjust expectations to current financing conditions. The result is high activity with low conversion, as deals fail to close on price.
Quality degradation: When owners who would not normally sell enter the market due to financial pressure, the average quality of opportunities declines even as volume increases. These businesses may have deferred maintenance, customer attrition, or management gaps that complicate underwriting.
Sector crowding: When multiple funds pursue the same thesis, competition compresses returns even on quality businesses. A 12x EBITDA multiple on a healthcare services business may not be “wrong” given competitive dynamics, but it may not support the fund’s target returns.
Distinguishing Opportunity From Noise
The abundance-with-unattractive-underwriting scenario requires discipline. Tracking conversion rates, declined-opportunity reasons, and pricing trends helps distinguish whether low activity reflects market conditions or origination problems.
If the pipeline contains many thesis-aligned opportunities but few convert due to pricing, the issue is market dynamics. If the pipeline contains few thesis-aligned opportunities regardless of pricing, the issue is origination. The responses differ materially.
7. Building a Deal-Flow Assessment Framework
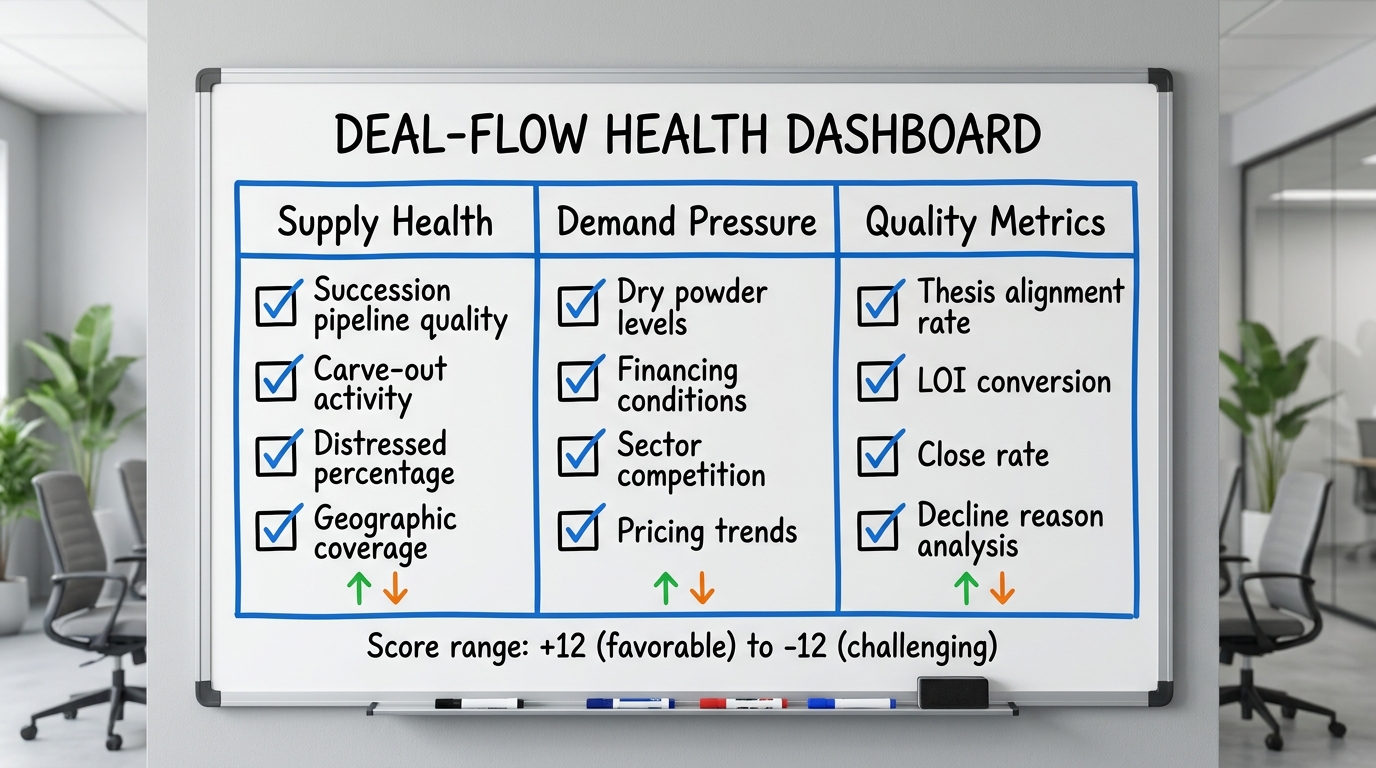
Systematic deal-flow assessment requires tracking both quantitative metrics and qualitative signals. The following framework provides a structure for evaluating pipeline health beyond simple volume counts.
Supply-Side Assessment
Understanding supply requires monitoring the sources of deal flow and their characteristics:
- What percentage of opportunities come from succession situations versus carve-outs versus distressed assets?
- Are succession opportunities showing signs of preparation (professional management, documented processes, clean financials)?
- Is carve-out activity increasing in target sectors, signaling potential opportunities?
- Is distressed deal flow rising, indicating potential quality degradation?
Demand-Side Assessment
Demand-side monitoring contextualizes competitive dynamics:
- How is dry powder trending relative to deployment activity?
- Are financing conditions supporting or constraining deal structures?
- Which sectors are experiencing the most concentrated buyer interest?
- Are pricing trends in recent transactions moving toward or away from target return support?
Quality Assessment
Quality metrics track the actionability and investability of the pipeline:
- What is the thesis-alignment rate on inbound opportunities?
- What is the conversion rate from initial review to LOI?
- What is the conversion rate from LOI to close?
- What are the primary reasons for declined opportunities?
Integrating these assessments with broader private equity market intelligence provides the context needed to distinguish fund-specific issues from market-wide conditions.
8. Deal-Flow Signal Scorecard
The following scorecard provides a structured approach to assessing deal-flow health across supply, demand, and quality dimensions. Each signal includes scoring criteria that help translate qualitative observations into actionable assessments.
| Category | Signal | Positive Indicator (Score +1) | Neutral (Score 0) | Negative Indicator (Score -1) |
|---|---|---|---|---|
| Supply | Succession pipeline | Rising volume of prepared businesses with professional management | Stable volume, mixed preparation levels | Declining volume or predominantly unprepared businesses |
| Carve-out activity | Increasing corporate divestitures in target sectors | Stable carve-out activity | Limited carve-out opportunities | |
| Distressed composition | Low percentage of distressed opportunities (unless fund focus) | Modest distressed volume | High percentage of distressed or challenged businesses | |
| Geographic coverage | Strong coverage in target geographies | Adequate coverage with gaps | Limited coverage in priority markets | |
| Demand | Dry powder pressure | Moderate dry powder, balanced deployment pace | Elevated dry powder, active deployment | Extreme dry powder overhang, aggressive competition |
| Financing availability | Accessible debt at reasonable terms | Constrained but available financing | Severely limited or expensive financing | |
| Sector competition | Differentiated positioning in target sectors | Moderate competition with some differentiation | Intense competition without clear differentiation | |
| Pricing trends | Multiples supporting target returns | Elevated multiples with selective opportunities | Multiples consistently above return support thresholds | |
| Quality | Thesis alignment rate | >40% of inbound opportunities fit criteria | 20-40% alignment rate | <20% alignment rate |
| Conversion to LOI | >10% of reviewed opportunities reach LOI | 5-10% conversion rate | <5% conversion rate | |
| Close rate | >50% of LOIs close | 30-50% close rate | <30% close rate | |
| Decline reasons | Declines primarily due to pricing (market issue) | Mixed decline reasons | Declines primarily due to fit (origination issue) |
Interpreting the scorecard: Sum the scores across all twelve signals. A total score of +6 or higher indicates favorable deal-flow conditions. A score between +2 and +5 suggests mixed conditions requiring selective focus. A score of +1 or below indicates challenging conditions that may require origination strategy adjustments or patience.
9. Applying the Framework to Current Market Conditions
The scorecard becomes most useful when applied to specific market conditions. As of 2024, several dynamics shape deal-flow quality for middle-market private equity.
Current Supply Dynamics
The aging of business owners continues to drive succession-motivated deal flow. According to U.S. Chamber of Commerce data, a significant percentage of small business owners are approaching retirement age, suggesting sustained succession-driven supply.
However, the quality of this supply varies. Businesses that weathered pandemic disruption with strong performance represent different opportunities than those still recovering. The scorecard’s succession pipeline signal should account for preparation levels, not just volume.
Current Demand Dynamics
The elevated dry powder levels documented by Bain create competitive pressure, but deployment has slowed relative to capital raised. This creates a complex dynamic: abundant capital chasing fewer transactions, with sellers maintaining price expectations while buyers exercise caution.
Financing conditions have tightened relative to 2021, though BCG’s 2024 private equity outlook notes that private credit has partially filled gaps left by reduced bank lending. The scorecard’s financing signals should reflect both availability and cost.
Implications for Deal-Flow Strategy
In the current environment, deal-flow quality likely matters more than volume. Funds with differentiated origination, sector expertise that supports higher valuations, or operational capabilities that create value independent of financial engineering may find more investable opportunities than generalist buyers competing on price alone.
10. Summary and Implementation Checklist
Private equity deal flow quality depends on the intersection of supply conditions, demand dynamics, and the specific characteristics that make opportunities actionable and investable. Volume metrics alone provide insufficient insight into pipeline health.
Key Takeaways
- Deal-flow quality, not volume, determines deployment effectiveness. Measure thesis alignment, actionability, and conversion rates.
- Supply originates from succession, carve-outs, and distressed situations, each with distinct characteristics and requirements.
- Demand-side factors, including dry powder levels, financing conditions, and sector concentration, shape competitive dynamics and pricing.
- Proprietary versus brokered processes affect pricing, competition, and timeline in predictable ways.
- Investability signals span seller motivation, business fundamentals, and market positioning.
- High volume can coexist with poor underwriting conditions when valuations disconnect or quality degrades.
Implementation Checklist
Use this checklist to assess and improve deal-flow effectiveness:
- ☐ Define explicit thesis criteria (sector, size, geography, value-creation approach) to measure alignment
- ☐ Track conversion metrics at each stage (review to LOI, LOI to close) by source
- ☐ Document decline reasons to distinguish market issues from origination issues
- ☐ Monitor supply-side indicators in target sectors (succession activity, carve-out announcements, distressed trends)
- ☐ Track demand-side context (dry powder trends, financing conditions, sector pricing)
- ☐ Assess proprietary versus brokered mix and its implications for competition and pricing
- ☐ Score the pipeline quarterly using the deal-flow signal scorecard
- ☐ Adjust origination strategy based on scorecard trends, not just volume metrics
For ongoing monitoring of the market factors that shape deal-flow quality and investment timing, subscribe to the Growth Shuttle research briefing for monthly deal-flow signals, and download the Deal Flow Signal Tracker.