
By Mario Peshev
You closed the deal eight weeks ago. The investment thesis promised 2.5x returns through operational improvements, strategic add-ons, and commercial acceleration. Now the portfolio company CEO is asking which initiatives take priority, the operating partner wants to know why EBITDA is flat, and the board expects a detailed roadmap at next month’s meeting. The value creation plan you sketched during diligence suddenly needs to become an executable operating document.
This is where most value creation plans fail. According to Bain’s 2023 Global Private Equity Report, roughly 40% of deals fail to meet their original investment thesis targets, and the gap often traces back to a disconnect between what the deal team envisioned and what operators can actually deliver. The problem is rarely the thesis itself. The problem is translation: turning a financial model into workstreams with owners, evidence gates, and resource requirements that match reality.
I have seen this pattern repeatedly when working with private equity market intelligence teams and portfolio operators. The plans that succeed share common structural elements. They treat value creation as a hypothesis-testing exercise rather than a project list. They build in explicit decision points for stopping or pivoting. And they match ambition to the actual capital and capability constraints of the business.
This guide walks through how to build a value creation plan that survives contact with operational reality, complete with evidence maps and implementation trackers you can adapt for your own portfolio companies.
1. What Belongs in an Investable Value Creation Plan
A value creation plan that earns board confidence and operator commitment needs to answer five questions simultaneously. Miss any one, and you create gaps that surface as execution failures six months later. The five questions below are the minimum bar. For the commercial, GTM and digital workstreams specifically, I keep a longer breakdown of [what belongs in a value creation plan], since those are the initiatives most often written as a single line in the model and then stalled by month 4.
The Five Questions Every VCP Must Answer
First: What specific outcomes justify the investment thesis? Not “improve margins” but “expand gross margin from 42% to 48% within 24 months through procurement consolidation and pricing optimization.” The specificity matters because it sets the evidence bar for success.
Second: What levers produce those outcomes, and in what sequence? McKinsey’s research on value creation identifies four primary lever categories: revenue growth, margin improvement, capital efficiency, and multiple expansion. Each lever decomposes into specific initiatives. Your VCP needs to map initiatives to levers to thesis outcomes.
Third: Who owns each workstream, and what authority do they have? Ownership without decision rights produces status meetings, not results. Every initiative needs a named owner with clear boundaries on what they can decide alone versus what requires escalation.
Fourth: What evidence demonstrates progress, and at what thresholds? This is where most plans fail. They track activity (meetings held, reports delivered) rather than outcomes (pipeline conversion improved, procurement savings realized). Define the leading and lagging indicators that prove the initiative is working.
Fifth: What resources does each initiative require, and where do constraints bind? Capital is one constraint. Management attention is another. Integration bandwidth is a third. Your VCP needs to acknowledge these limits explicitly and sequence accordingly.
The Difference Between a Deal Model and an Operating Plan
Deal models project outcomes. Operating plans create them. A deal model might assume $3M in procurement savings based on supplier consolidation benchmarks. An operating plan specifies which suppliers, which categories, what timeline, who negotiates, what systems changes are required, and what evidence confirms the savings are real rather than accounting artifacts.
The VCP bridges these two documents. It takes the deal model’s assumptions and converts them into testable hypotheses with implementation paths. When I work on private equity value creation engagements, the first exercise is always mapping deal model assumptions to specific operational requirements. That mapping exposes which assumptions are executable and which need revision.
2. Translating Investment Thesis to Workstreams
Every investment thesis rests on a set of beliefs about what will create value. The translation problem is converting those beliefs into workstreams that operators can execute.
Start with Thesis Decomposition
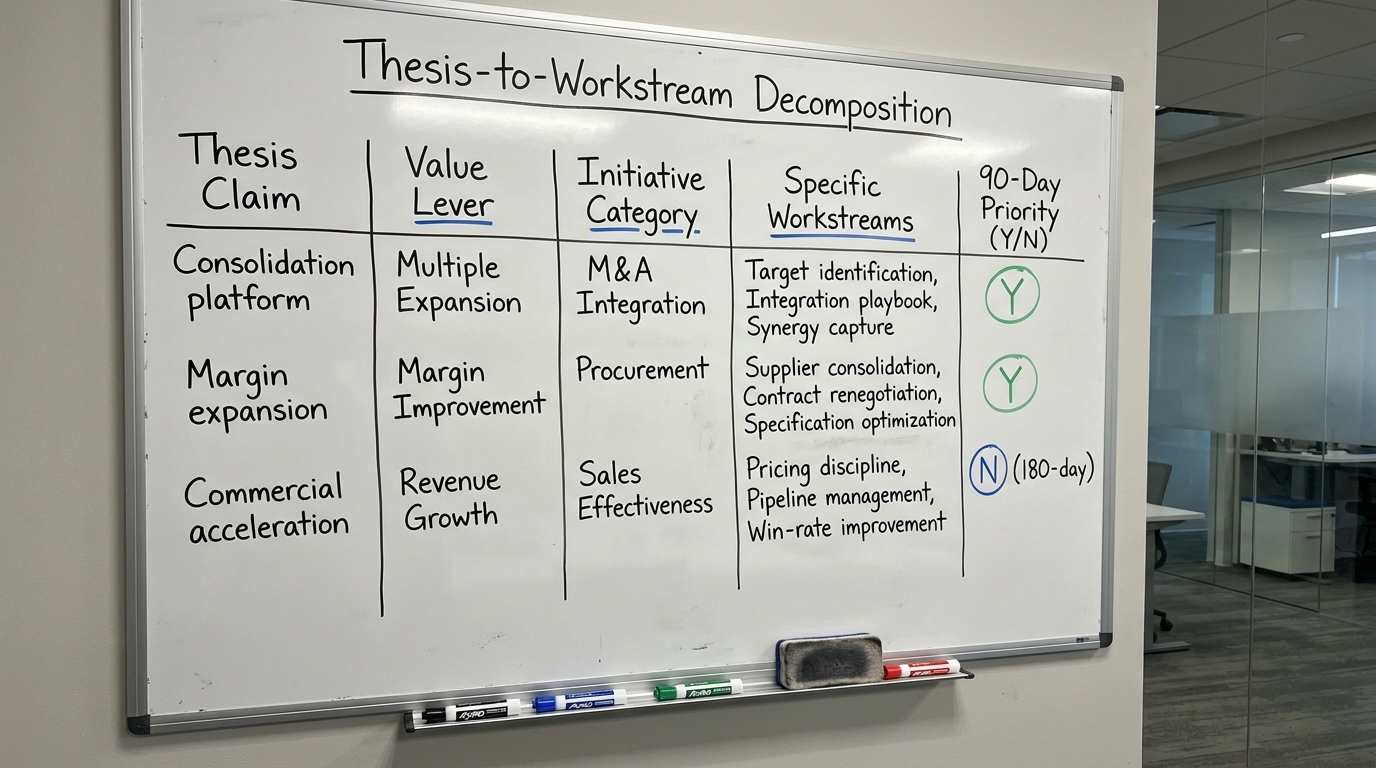
Take your thesis statement and break it into component claims. A thesis like “consolidation platform with margin expansion opportunity” contains at least three distinct claims: (1) add-on targets exist and are acquirable at reasonable multiples, (2) operational synergies are achievable post-acquisition, and (3) standalone margin improvement is possible independent of acquisitions.
Each claim becomes a workstream category. Each category contains specific initiatives. Each initiative has an owner, evidence requirements, and resource needs.
The Lever-to-Initiative Mapping
According to BCG’s 2023 analysis of private equity value creation, the most successful sponsors achieve returns through multiple levers simultaneously rather than betting on a single driver. Your VCP should reflect this by mapping initiatives across lever categories:
Revenue growth initiatives might include pricing optimization, sales force effectiveness, new market entry, or product line extension. Each requires different capabilities and timelines.
Margin improvement initiatives typically cover procurement optimization, operational efficiency, overhead rationalization, or manufacturing improvements. These often deliver faster but may require upfront investment.
Capital efficiency initiatives address working capital, capex optimization, or asset utilization. They affect cash flow but may not show in EBITDA.
Multiple expansion initiatives relate to strategic positioning, recurring revenue mix, or market perception. They are hardest to control but often drive significant value. The mix matters more than any single lever. Before you weight the plan, it is worth checking the evidence on [value creation in private equity] to see which levers have actually carried returns in comparable deals rather than assuming multiple expansion will do the work.
For middle market private equity deals, the typical VCP contains 8-15 initiatives across these categories, with 3-5 designated as primary drivers of thesis returns.
3. Sequencing Initiatives Across 90, 180, and 365 Days
Sequencing is where theory meets organizational capacity. You cannot run 15 initiatives at full intensity simultaneously. The question is which ones to start, which to defer, and which to make contingent on others.
The 90-Day Window: Establish Baseline and Launch Quick Wins
The first 90 days after close are about establishing facts and building credibility. Harvard Business Review’s research on post-acquisition integration suggests that the quality of baseline data established in the first quarter predicts long-term value capture success.
During this window, your VCP should prioritize:
- Baseline documentation: Current-state metrics for every initiative area. You cannot improve what you have not measured accurately.
- Quick wins that build credibility: Initiatives that can show measurable progress within 90 days, even if the full value capture takes longer.
- Diagnostic work for larger initiatives: Scoping, stakeholder mapping, and resource assessment for the 180-day and 365-day workstreams.
A common mistake is launching too many initiatives in the first 90 days. Management bandwidth is your scarcest resource immediately post-close. Overloading the organization creates execution chaos that damages credibility and slows everything down. Cap the first wave at 3 or 4 initiatives and let the diagnostic work carry the rest. I have written up how I handle [sequencing the opening sprint after close], including which quick wins are worth the management time and which ones only look cheap.
The 180-Day Window: Execute Primary Levers
By day 180, your primary value creation workstreams should be in full execution mode with measurable progress. This is the window where procurement savings should be showing in the P&L, commercial initiatives should be moving pipeline metrics, and operational improvements should be visible in unit economics.
The 180-day checkpoint is also your first major decision gate. Initiatives that are not showing progress by this point need intervention or termination. The evidence you designed into your VCP tells you which workstreams are on track and which are struggling.
The 365-Day Window: Compound and Extend
By year end, successful initiatives should be compounding. Procurement savings create cash flow that funds commercial investment. Commercial improvements create revenue that supports multiple expansion. The VCP at this stage shifts from launch mode to optimization and extension.
This is also when you should be planning the next wave of initiatives. Value creation is not a one-year project. According to EY’s research on portfolio operations, the most successful private equity owners maintain rolling 12-month value creation horizons throughout the hold period.
4. Designing Owners, Evidence Gates, and KPIs
The operating discipline that separates successful value creation plans from wishful thinking lives in three elements: clear ownership, explicit evidence requirements, and KPIs that actually indicate progress.
Ownership Means Decision Rights
Naming an owner is not enough. The owner needs specified decision rights. What can they approve without escalation? What budget do they control? What cross-functional support can they demand? What happens when another department’s priorities conflict with theirs?
In private equity portfolio operations, unclear decision rights are a primary source of execution delay. The CFO thinks procurement reports to her. The COO thinks procurement is an operations function. The procurement initiative stalls while they negotiate territory.
Your VCP should specify for each initiative owner:
- What decisions they own outright
- What decisions require their input but are made elsewhere
- What escalation path exists for conflicts
- What resources they control directly versus request through others
Evidence Gates That Enable Go/No-Go Decisions
Every initiative needs defined evidence gates, checkpoints where you evaluate whether to continue, adjust, or stop. The evidence should be objective enough that reasonable people would agree on the assessment.
Good evidence gates have three characteristics:
Specificity: “Pipeline coverage ratio above 3x for Q3” rather than “improved pipeline health.”
Measurability: The data exists or can be created to evaluate the gate. If you cannot measure it, you cannot use it as an evidence gate.
Timeliness: The evidence is available early enough to inform decisions. A lagging indicator that arrives too late to change course is not useful as a gate.
Leading and Lagging KPIs
Every initiative needs both leading and lagging indicators. Leading indicators predict whether you will hit the target. Lagging indicators confirm whether you did.
For a sales effectiveness initiative, a lagging indicator might be revenue growth. Leading indicators might include opportunity creation rate, win rate by stage, average deal size, and sales cycle length. If leading indicators are positive but lagging indicators are not yet moving, you have reason for patience. If leading indicators are negative, you have early warning to intervene.
Governance: Who Owns the Value Creation Plan?
Effective value creation plans distinguish between strategic oversight and execution ownership. While governance structures vary across private equity firms, successful plans typically define who owns the investment thesis, who removes execution barriers, and who is accountable for delivery.
A common governance model looks like this:
- Investment team: ensures initiatives remain aligned with the original investment thesis and investment case.
- Operating partner (where applicable): removes execution blockers, coordinates cross-functional support, and helps reallocate resources when priorities shift.
- CEO and executive team: own implementation and day-to-day delivery.
- Board: reviews progress, approves major strategic changes, capital allocation decisions, and significant resets to the value creation plan.
Clearly defined governance reduces the risk that initiatives lose sponsorship as management attention shifts toward day-to-day operations after closing.
5. Accounting for Capital and Capability Constraints
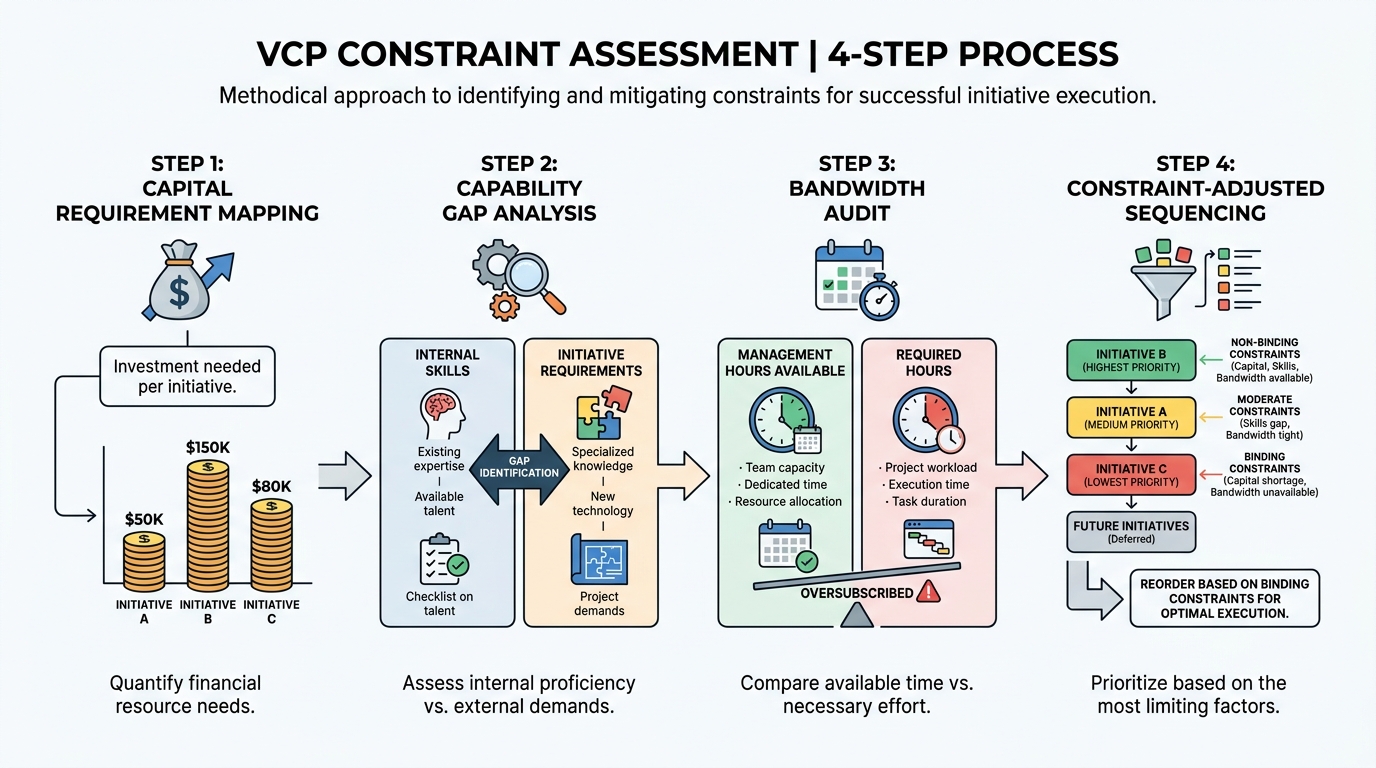
Every VCP is constrained by two resource categories: capital you can deploy and capability you can access. Ignoring either produces plans that fail on contact with reality.
Capital Constraints Shape Sequencing
Some value creation initiatives require upfront investment before they return value. A manufacturing improvement might need $2M in capex before it delivers $800K in annual savings. A commercial transformation might require $500K in sales enablement investment before pipeline improves.
Your VCP needs to account for these requirements and sequence accordingly. Initiatives with near-term positive cash flow should generally precede those requiring significant investment. Self-funding sequences create optionality. External funding requirements create dependencies.
According to Preqin’s analysis of portfolio company performance, value creation plans that require additional equity investment post-close face higher execution risk than those funded through operating cash flow or existing credit facilities.
Capability Constraints Are Often Binding
Capital constraints are visible. Capability constraints are often invisible until you hit them. You cannot execute a pricing optimization initiative if nobody in the organization understands pricing analytics. You cannot run an M&A integration if you have never done one before.
The capability audit for your VCP should address:
- Management bandwidth: How many initiatives can the executive team actually oversee while running the business?
- Functional expertise: Does the organization have the technical skills each initiative requires?
- Change capacity: How much organizational change can the company absorb simultaneously?
- External support availability: For capabilities you need to source externally, are qualified providers available and affordable?
When capability constraints bind, you have three options: sequence initiatives to match available capability, invest in building capability, or bring in external capability. Each choice has cost and timeline implications that belong in your VCP.
6. When to Stop or Reset a Workstream
One of the hardest decisions in value creation is knowing when to stop. Sunk cost psychology, organizational momentum, and ego all push toward continuation even when evidence suggests termination.
Defining Kill Criteria Upfront
The solution is defining kill criteria before you start. What evidence would convince you to stop this initiative? What conditions would trigger a fundamental reset? Writing these down at launch, when you are still objective, makes the decision easier when you are emotionally invested.
Kill criteria should be specific and time-bound:
- “If procurement savings are below $200K by month 6, we will reassess supplier consolidation feasibility.”
- “If pipeline coverage remains below 2x after Q2, we will evaluate whether the sales effectiveness approach needs fundamental redesign.”
- “If integration costs exceed synergy capture by month 9, we will shift to standalone optimization.”
The Reset Decision
Sometimes an initiative is not failing but is not succeeding either. The approach needs adjustment. The reset decision is different from the kill decision, it preserves the objective while changing the method.
Reset triggers might include:
- Leading indicators are mixed (some positive, some negative)
- External conditions have changed since launch
- New information suggests a different approach would be more effective
- The initiative owner requests a strategic review
Building reset points into your VCP at natural checkpoints (90 days, 180 days, board meetings) creates space for honest evaluation without the pressure of a kill-or-continue binary.
7. Building an Evidence Map by Value Creation Lever
An evidence map connects your thesis claims to the specific proof points that demonstrate progress. It is the diagnostic tool that tells you whether value creation is working.
Evidence Map Structure
For each value creation lever, the evidence map specifies:
- Thesis assumption: What the deal model assumed about this lever
- Baseline measurement: Current state at close
- Target outcome: End-state objective
- Leading indicators: Early signals of progress
- Lagging indicators: Confirmation of results
- Evidence gates: Checkpoints with specific criteria
- Data sources: Where the evidence comes from
Example Evidence Map by Lever
The table below provides an illustrative evidence map for a value creation plan spanning the primary lever categories. Adapt the specific metrics to match your portfolio company’s situation.
| Value Lever | Thesis Assumption | Baseline | Target (24 mo) | Leading Indicators | Lagging Indicators | 90-Day Gate | Data Source |
|---|---|---|---|---|---|---|---|
| Revenue Growth (Pricing) | 3-5% price increase achievable without volume loss | Avg price: $47/unit | Avg price: $50/unit | Price elasticity analysis complete; Pilot segment response | Realized price per unit; Volume retention rate | Elasticity study complete; 2 pilot segments identified | ERP transaction data; Customer research |
| Revenue Growth (Sales Effectiveness) | Win rate improvable from 22% to 30% | Win rate: 22% | Win rate: 30% | Pipeline quality scores; Sales process adherence | Closed-won rate; Revenue per rep | Sales process audit complete; CRM data quality baseline established | CRM; Sales performance dashboard |
| Margin Improvement (Procurement) | $2.5M savings from supplier consolidation | Spend: $18M across 340 suppliers | Spend: $15.5M across 180 suppliers | RFP response rates; Supplier negotiations in progress | Actual spend reduction; Supplier count | Category spend analysis complete; Top 3 categories for consolidation identified | AP system; Procurement tracker |
| Margin Improvement (Operations) | Labor productivity +15% through process standardization | Units/labor hour: 12 | Units/labor hour: 14 | Process documentation completion; Training hours delivered | Units per labor hour; Defect rate | Current-state process maps complete for 3 lines | Production system; Time tracking |
| Capital Efficiency (Working Capital) | DSO reducible from 58 to 45 days | DSO: 58 days | DSO: 45 days | Aging bucket trends; Collection call completion | DSO; Cash conversion cycle | AR aging analysis complete; Collection process documented | AR aging report; Cash flow statement |
| Multiple Expansion (Recurring Revenue) | Recurring revenue mix from 35% to 55% | Recurring: 35% | Recurring: 55% | Subscription product pipeline; Contract conversion rate | Recurring revenue %; Net revenue retention | Subscription offering designed; Pilot customer cohort identified | Revenue recognition system; Customer success metrics |
This evidence map becomes your value creation dashboard. Review it at every board meeting. Update baselines as you get better data. Adjust targets when evidence suggests the original assumptions were wrong.
8. Building Your Implementation Tracker
The evidence map tells you whether value creation is working. The implementation tracker tells you whether you are doing the work. They are complementary tools.
Implementation Tracker Structure
The tracker below provides a framework for monitoring initiative execution. Each row represents a workstream. The columns capture status, ownership, timeline, dependencies, and next actions.
| Workstream | Owner | Status | 90-Day Milestone | 180-Day Milestone | 365-Day Target | Dependencies | Blockers | Next Action | Due Date |
|---|---|---|---|---|---|---|---|---|---|
| Pricing Optimization | VP Sales | On Track | Elasticity analysis complete | Pilot segments live | Full rollout complete | Customer research; ERP access | None | Finalize pilot segment selection | [Date] |
| Supplier Consolidation | VP Operations | At Risk | Category analysis complete | Top 3 categories renegotiated | $2.5M savings captured | Finance support; Legal contract review | Legal capacity constrained | Escalate legal resource request to CFO | [Date] |
| Sales Process Redesign | CRO | On Track | Current-state documented | New process live | Win rate at 30% | CRM configuration; Training capacity | None | Complete sales process audit interviews | [Date] |
| Working Capital Optimization | CFO | Behind | AR aging analysis complete | Collection process implemented | DSO at 45 days | None | Finance team bandwidth | Bring in interim AR specialist | [Date] |
| Recurring Revenue Expansion | VP Product | Not Started | Subscription offering designed | Pilot cohort live | 55% recurring mix | Pricing work complete; Billing system capable | Waiting on pricing analysis | Initiate product design sprint | [Date] |
Using the Tracker in Practice
Review the implementation tracker weekly with initiative owners. The tracker should answer three questions in under 30 minutes:
- Which workstreams are on track, at risk, or behind?
- What blockers need escalation or resource allocation?
- What actions are due this week, and are they on schedule?
The tracker also provides board reporting material. Status, blockers, and milestone progress translate directly into the value creation section of board decks.

9. Connecting VCP to Operating Rhythm
A value creation plan only works if it connects to how the organization actually operates. That means embedding VCP reviews into existing meeting structures and reporting cadences.
Weekly Operational Reviews
Initiative owners should report progress weekly against implementation tracker commitments. These reviews do not require executive attendance for every initiative, but a senior sponsor should see the consolidated view.
Monthly Value Creation Reviews
Monthly reviews bring together all initiative owners to assess evidence map progress, identify cross-initiative dependencies, and escalate blockers. This is where you evaluate whether the portfolio of initiatives is collectively on track to deliver thesis returns.
Quarterly Board Updates
Board presentations should summarize VCP progress against the evidence map, highlight any initiatives requiring kill or reset decisions, and preview the next quarter’s priorities. The board should see leading indicators that predict whether lagging results will materialize.
For the operator’s 100-day execution plan, these rhythms become the backbone of post-close integration and value creation management.
10. Summary Checklist for an Investable Value Creation Plan
Before you finalize your VCP, verify it addresses each of these elements:
Thesis Translation
- Investment thesis decomposed into specific, testable claims
- Each claim mapped to value creation levers
- Levers translated to specific initiatives
Initiative Design
- Each initiative has a named owner with defined decision rights
- Resource requirements (capital and capability) specified
- Dependencies between initiatives documented
Evidence and Measurement
- Baseline metrics established for every initiative area
- Leading and lagging KPIs defined
- Evidence gates with specific criteria at 90, 180, and 365 days
Constraints and Sequencing
- Capital requirements mapped against available funding
- Capability gaps identified with sourcing plans
- Management bandwidth assessed and initiatives sequenced accordingly
Decision Framework
- Kill criteria defined for each initiative
- Reset triggers specified
- Escalation paths documented
Operating Rhythm
- Weekly implementation reviews scheduled
- Monthly value creation reviews structured
- Board reporting cadence established
A value creation plan that meets these criteria gives you the operating discipline to translate investment thesis into realized returns. It will not guarantee success, but it will ensure you know early when something is not working and have the information to respond.
Subscribe to the Growth Shuttle research briefing for the value-creation evidence and sequencing, and download the VCP evidence map and implementation tracker to adapt for your portfolio companies.