
You’re reviewing a deal where the seller isn’t a founder or a private equity sponsor. It’s a Fortune 500 parent divesting a division that no longer fits the corporate strategy. The financials look odd: shared services allocations you can’t trace, intercompany revenue that disappears post-close, and a management team that has never operated without corporate air cover. Half the due diligence findings are about what you don’t know yet.
This is the reality of corporate carve-outs. They represent some of the most attractive acquisition opportunities in the market, but they also carry structural complexity that platform deals and founder buyouts rarely present. The question isn’t whether carve-out acquisitions are worth pursuing. It’s whether you can distinguish the neglected gems from the assets that were neglected for good reason.
This framework helps you read the carve-out market: why parents divest, what those motivations signal about the asset, and how to evaluate whether a corporate divestiture becomes a value-creation platform or a multi-year separation nightmare that consumes your hold period.
The thesis behind divestiture deals and why they outperform
The thesis behind divestiture private equity is straightforward: corporate parents are not optimized to run non-core businesses. They over-allocate shared services, under-invest in growth, and manage divisions through corporate metrics that don’t fit the unit’s actual market position. When you separate that division and run it as a standalone entity with focused management, appropriate capital allocation, and aligned incentives, value creation follows.
Bain’s 2023 Global Private Equity Report found that carve-outs historically outperform other deal types on returns, though they require longer hold periods and more operational intervention. The outperformance comes from a specific dynamic: the parent’s strategic neglect creates a gap between the asset’s current performance and its potential under focused ownership.
Consider what a corporate parent typically does to a non-core division:
- Allocates corporate overhead at rates that obscure true standalone economics
- Restricts capital investment because returns don’t meet corporate hurdle rates (even if they’d be attractive standalone)
- Imposes enterprise systems, processes, and reporting that don’t fit the division’s scale or market
- Limits management autonomy, creating decision latency that competitors exploit
- Signals to customers and employees that the business isn’t a strategic priority
Each of these creates a value-creation lever. The question is whether you can access those levers without the separation costs consuming the gains.
The Structural Advantage Over Platform Deals
When you build a private equity investment thesis around a carve-out, you’re often buying a business with established customer relationships, proven products, and experienced middle management, but without the premium valuation that comes with a clean, standalone company. The parent’s motivation to divest creates negotiating leverage. The complexity creates deal protection against less sophisticated buyers.
Compare this to a typical platform acquisition where you’re competing with strategic buyers, other sponsors, and sometimes the management team itself. Carve-outs often have a smaller buyer universe because most firms can’t execute the separation. That’s your edge, if you can actually execute.
Why parents divest and what that signals about the asset
The parent’s reason for divesting tells you more about the asset’s potential than any management presentation. Understanding corporate divestiture motivations helps you distinguish between a division being sold because it’s broken versus a division being sold because it doesn’t fit.
Strategic Refocusing
The cleanest signal. The parent is doubling down on a core business and shedding everything else. McKinsey research on corporate portfolio management shows that focused companies typically outperform conglomerates, which drives periodic waves of divestitures as executives respond to investor pressure. These assets often have solid fundamentals but have been starved of attention and capital. The parent isn’t hiding problems; they’re acknowledging that the division deserves an owner who cares about it.
Activist Pressure
More complicated. An activist has identified the division as a source of hidden value and is forcing a sale. This can produce attractive deals, but the timeline is often compressed, and the parent may be less cooperative during transition. The asset quality varies widely: sometimes the activist is right that the division is undervalued, sometimes they’re simply creating short-term shareholder returns without regard for the division’s long-term viability.
Performance Problems
The riskiest signal. The parent is divesting because the division has underperformed. Here, you need to distinguish between corporate-induced underperformance (which you can fix) and market-driven underperformance (which you probably can’t). A division that’s losing share in a declining market doesn’t become attractive just because you separate it from the parent.
Balance Sheet Repair
The parent needs cash. This creates urgency that can work in your favor on price, but it also means the parent may have under-invested in the division for years. Deferred maintenance, delayed technology upgrades, and talent attrition often accompany these deals. Factor the catch-up investment into your model.
A thorough M&A due diligence checklist should include specific questions about the parent’s divestiture rationale, with triangulation across management interviews, board materials, and analyst reports.
Standalone-cost and stranded-cost reality
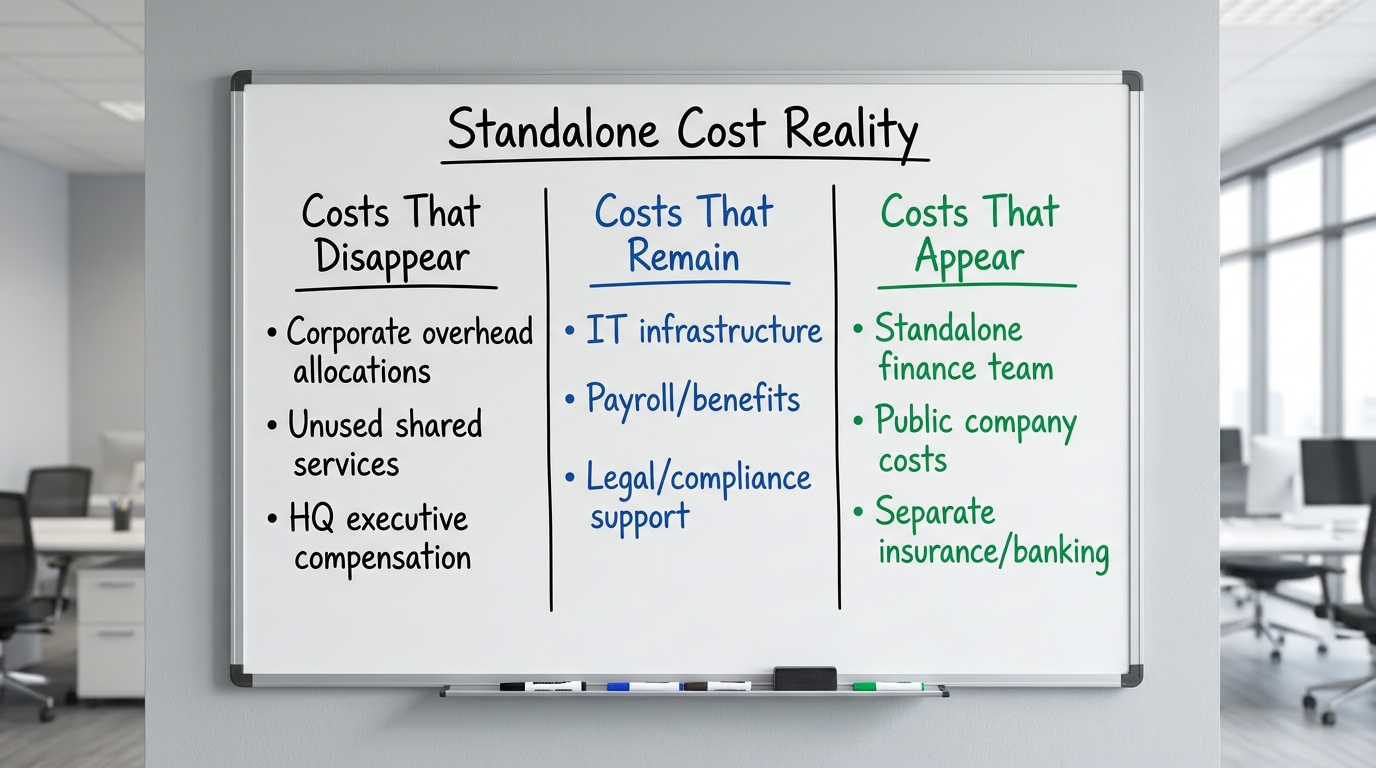
The most common mistake in carve-out acquisitions is underestimating what it actually costs to operate as a standalone entity. The division’s historical financials show allocated costs from the parent. Your job is to determine what costs disappear, what costs remain, and what new costs appear.
Costs That Disappear
Corporate overhead allocations often include charges for services the division doesn’t actually use or could source more cheaply independently. Executive compensation allocated from headquarters, shared aircraft, corporate real estate in cities where the division doesn’t operate. These allocations inflate the division’s apparent cost structure. Stripping them out improves margins, sometimes dramatically.
Costs That Remain
Shared services that the division actually uses: IT infrastructure, payroll processing, benefits administration, legal support. These don’t disappear at separation. You either build them internally, contract with the parent temporarily through transition services agreements, or outsource to third parties. The cost is rarely lower than what the parent charged, and it’s often higher in the first two years as you scale these functions.
Costs That Appear
Public company costs if you’re taking the division public. Standalone banking relationships. Insurance policies that were bundled under the parent. Compliance infrastructure. A CFO and finance team sized for a standalone entity rather than a division. BCG’s research on carve-out execution suggests that buyers typically underestimate standalone costs by 15-25% in initial models.
The stranded-cost problem affects the parent too. When a division leaves, the parent’s remaining businesses must absorb shared costs that were previously spread across a larger base. This creates friction in negotiations: the parent may resist certain separation approaches that leave them with stranded costs, even if those approaches would be better for the divested entity.
The separation risk premium and how to price it
Every carve-out carries separation risk. The question is how to price that risk into your offer without either overpaying (by ignoring it) or losing the deal (by discounting too aggressively).
Separation risk manifests in several ways:
- Timeline risk: Separation takes longer than planned, extending TSA costs and delaying value creation
- Execution risk: Critical systems or processes fail during cutover, disrupting operations
- Talent risk: Key employees leave during the uncertainty of separation
- Customer risk: Customers use the transition as an opportunity to renegotiate or switch
- Hidden liability risk: Problems surface post-close that were obscured by the parent’s consolidated reporting
I’ve seen separation timelines slip by 12-18 months on complex carve-outs, with each month adding TSA costs that weren’t in the original model. The best protection is conservative planning: assume separation takes 50% longer than management’s base case, and stress-test your returns at that timeline.
Pricing the Premium
Sophisticated carve-out buyers build separation costs and risks into their valuation rather than adjusting the headline multiple. This means:
- Modeling TSA costs at realistic durations, not management’s optimistic case
- Reserving capital for separation investments (systems, facilities, team buildout)
- Assuming 6-12 months of productivity loss during the transition
- Building contingency for stranded-cost negotiations with the parent
The separation risk premium typically runs 0.5x to 1.5x EBITDA multiple discount versus a comparable standalone asset, depending on complexity. Highly entangled divisions at the upper end; cleaner separations at the lower end.
This connects to broader private equity value creation planning. The separation itself isn’t value creation; it’s a prerequisite for value creation. Time and capital spent on separation is time and capital not spent on growth initiatives.
Signals of a clean carve versus an entangled one
Due diligence on a carve-out should answer one core question: how entangled is this division with the parent? The answer determines your separation timeline, cost, and risk.
Indicators of a Clean Carve
- The division has its own P&L and balance sheet, not just allocated financials
- Core operating systems (ERP, CRM) are either division-specific or easily separable
- The management team has operated with meaningful autonomy
- Customer contracts are in the division’s name, not the parent’s
- Facilities are dedicated to the division, not shared with other parent businesses
- Employee benefits can be separated without major restructuring
- The division has its own supplier relationships and contracts
Indicators of Entanglement
- Shared manufacturing facilities or supply chain with other parent divisions
- Intercompany revenue that represents a significant portion of the division’s sales
- Shared sales force that sells the division’s products alongside other parent products
- Common IT infrastructure with no clear separation path
- Intellectual property that’s commingled or licensed from the parent
- Key employees who split time between the division and other parent businesses
- Customer relationships that depend on the parent’s brand or broader offerings
The most dangerous entanglements are often non-obvious. A division might look clean on the surface, but its largest customer relationship might exist only because the parent bundles the division’s products with other offerings. Or the division’s competitive position might depend on technology licensed from the parent that becomes expensive or unavailable post-separation.
For context on how these separation dynamics compare to other transaction types, see our analysis of take-private transactions, which present different complexity profiles.
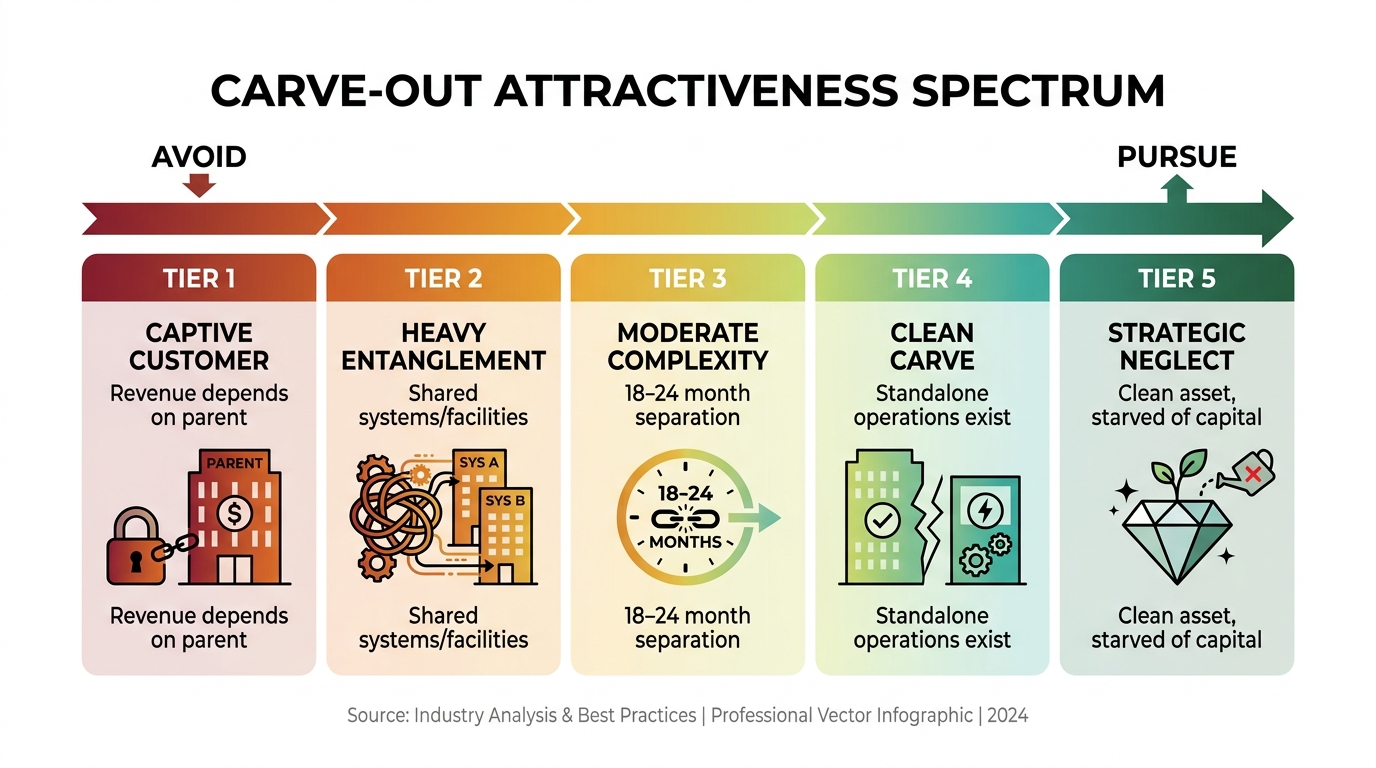
When a division never stands alone profitably
Not every carve-out is a hidden gem. Some divisions exist only because the parent subsidizes them, and that subsidy disappears at separation.
The Captive Customer Problem
A division whose primary customer is the parent faces an existential question: will that customer relationship survive at arm’s length? Sometimes yes, if the division provides genuinely competitive products. Often no, if the parent was buying internally out of convenience rather than value. PwC’s analysis of carve-out failures identifies captive customer relationships as one of the top three reasons deals underperform expectations.
The Shared Infrastructure Problem
Some divisions only work economically because they share manufacturing, distribution, or technology infrastructure with the parent. A consumer products division that uses the parent’s distribution network might have attractive margins today, but replicating that distribution independently could consume years of investment and permanently alter the cost structure.
The Brand Dependency Problem
If the division’s market position depends on the parent’s brand, separation creates risk. Customers may have chosen the division’s products because they trusted the parent company. That trust doesn’t transfer automatically to a new owner, and rebuilding it takes time and investment.
The Regulatory Shield Problem
In regulated industries, the parent’s licenses, certifications, or regulatory relationships may extend to the division. Post-separation, the division needs its own regulatory standing, which can be expensive and time-consuming to establish. In some cases, it’s not achievable at all without the parent’s scale or track record.
When evaluating these risks, access to private equity market intelligence on comparable carve-outs helps calibrate expectations. What happened to similar divisions post-separation? Did they achieve standalone viability, or did they struggle?
What the first year must prove operationally
The value-creation thesis for a carve-out only works if you can execute the separation while maintaining business performance. The first year is the proving ground.
Day 1 Through Day 100
The immediate post-close period focuses on stability. TSA execution must be flawless. Customer communication must reassure, not alarm. Employees need clarity on their roles, compensation, and future. Nothing growth-oriented happens in this phase; the goal is simply to keep the business running while you build the separation infrastructure.
Months 4 Through 9
The separation execution phase. You’re standing up standalone functions, migrating off parent systems, and building the organization that will run the business long-term. This is resource-intensive and distracting. Management attention is split between running the business and executing the separation. Performance often dips during this phase, and that dip should be in your model.
Months 10 Through 12
TSA exits and the transition to true standalone operation. This is when the separation either succeeds or stumbles. Key milestones: all critical systems operating independently, TSA costs declining toward zero, and management attention shifting from separation to growth.
For a detailed breakdown of post-close execution priorities, including the commercial, operational, and data integration workstreams that carve-outs require, see the operator’s post-merger integration playbook.
What “Success” Looks Like
At the end of Year 1, a successful carve-out shows:
- Revenue at or above pre-separation levels (flat is acceptable; growth is a bonus)
- EBITDA margins stabilizing at standalone economics (not inflated by parent allocations, not depressed by separation costs)
- TSA dependencies eliminated or on clear exit timeline
- Key customer relationships retained
- Management team intact and motivated
- Separation investments tracking to budget
Year 1 doesn’t prove the investment thesis. It proves that the thesis is achievable. The actual value creation, the growth initiatives, the margin improvement, the add-on acquisitions, happens in Years 2 through 5, once separation is behind you.
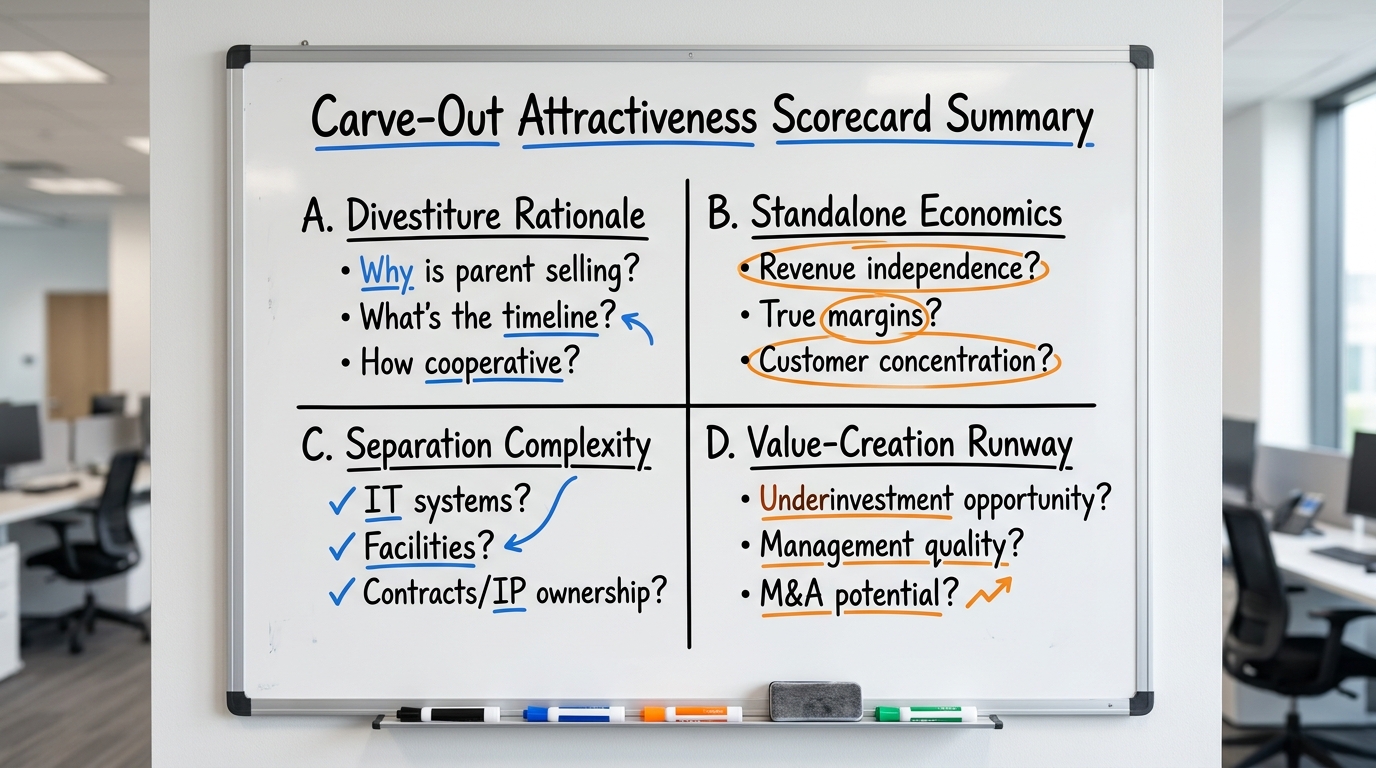
Carve-out attractiveness scorecard
The following scorecard provides a structured framework for evaluating corporate carve-outs across the four dimensions that determine deal attractiveness. Score each factor from 1 (unattractive) to 5 (highly attractive), then calculate category averages and an overall score.
| Category | Factor | Score 1 (Unattractive) | Score 3 (Neutral) | Score 5 (Attractive) | Your Score (1-5) |
|---|---|---|---|---|---|
| A. Divestiture Rationale | Parent motivation | Performance problems / distressed sale | Activist pressure / balance sheet repair | Strategic refocusing / portfolio optimization | |
| Timeline pressure | Fire sale, compressed diligence | Moderate urgency | Orderly process, adequate time | ||
| Parent cooperation | Adversarial, minimal support | Transactional relationship | Cooperative, invested in success | ||
| Competitive dynamics | Broad auction, strategic interest | Limited auction | Proprietary or narrow process | ||
| B. Standalone Economics | Revenue independence | >30% intercompany revenue | 10-30% intercompany | <10% intercompany revenue | |
| True standalone margins | Negative or <5% EBITDA | 5-15% EBITDA | >15% EBITDA standalone | ||
| Stranded cost exposure | Major stranded costs, difficult negotiation | Moderate stranded costs | Clean separation, minimal stranded costs | ||
| Customer concentration | Parent is top customer | Parent is significant but not dominant | No material parent dependency | ||
| C. Separation Complexity | IT systems | Fully integrated, no separation path | Shared but separable | Division-specific systems | |
| Facilities | Shared manufacturing / distribution | Some shared, some dedicated | Fully dedicated facilities | ||
| Workforce | Significant shared / split employees | Some shared functions | Dedicated workforce | ||
| Contracts / IP | Commingled IP, parent-held contracts | Mixed ownership | Clean division ownership | ||
| D. Value-Creation Runway | Historical underinvestment | Appropriately capitalized | Some deferred investment | Significant deferred investment opportunity | |
| Management quality | Weak team, corporate dependence | Capable but untested standalone | Strong team ready for autonomy | ||
| Market position | Declining share, weak position | Stable position | Strong position, growth opportunity | ||
| Add-on / consolidation opportunity | Limited M&A runway | Some tuck-in potential | Clear platform for consolidation |
Scoring Interpretation
Category A (Divestiture Rationale): Average score below 2.5 suggests the parent’s motivation may signal fundamental asset problems. Proceed with caution.
Category B (Standalone Economics): Average score below 3.0 indicates the asset may not be viable as a standalone entity. This is often a deal-breaker.
Category C (Separation Complexity): Average score below 2.5 means separation will consume significant time and capital. Factor 18-24+ months and substantial investment into your model.
Category D (Value-Creation Runway): Average score below 3.0 suggests limited upside even with successful separation. The thesis may not justify the execution risk.
Overall Score Guidance:
- Overall average 4.0+: Highly attractive carve-out opportunity
- Overall average 3.0-4.0: Attractive with manageable complexity
- Overall average 2.5-3.0: Proceed only with specific edge on execution or price
- Overall average below 2.5: Consider passing unless exceptional circumstances
The decision framework in practice
Applying this framework requires integrating the scorecard with your specific capabilities and deal economics. A firm with strong operational resources and carve-out experience can pursue deals that would be too complex for a generalist buyer. A firm with a specific sector thesis might accept higher separation complexity in exchange for strategic fit.
When to Walk Away
- Standalone economics don’t work at realistic cost assumptions
- Customer concentration risk is unhedgeable
- IP or regulatory dependencies create post-close vulnerability
- Separation timeline exceeds your operational capacity
- Parent cooperation is insufficient for successful transition
When to Lean In
- Strategic neglect has created clear operational improvement opportunities
- The division has a strong market position that the parent failed to exploit
- Management is capable and motivated for standalone operation
- Separation complexity is manageable with your resources and expertise
- Deal dynamics allow appropriate pricing for separation risk
The Competitive Advantage in Carve-Outs
Deloitte’s analysis of carve-out transactions suggests that buyers with dedicated separation capabilities, including experienced operators, established TSA management processes, and integration playbooks, consistently outperform those attempting carve-outs opportunistically. The complexity that deters other buyers becomes your competitive moat.
This is why carve-out private equity represents a legitimate specialization. The skill set required to evaluate, execute, and create value in these transactions is distinct from traditional buyout capabilities. Firms that develop this expertise access a segment of the market with less competition and attractive return potential.
Summary: The Carve-Out Evaluation Checklist
Before pursuing a corporate carve-out, confirm the following:
- Divestiture rationale is favorable: Strategic refocusing or portfolio optimization, not performance problems or distress
- Standalone economics are viable: The division can operate profitably without parent subsidies, intercompany revenue, or shared infrastructure
- Separation complexity is manageable: You have the resources, expertise, and timeline to execute the separation without destroying value
- Value-creation runway exists: Historical underinvestment, management quality, and market position support your investment thesis
- Pricing reflects separation risk: Your model includes realistic TSA costs, separation investments, and timeline assumptions
- First-year milestones are achievable: You can maintain business performance while executing the separation
Corporate carve-outs remain one of the most compelling opportunities in private equity for buyers who can execute. The parents divest for rational reasons. The divisions carry complexity that deters competition. The value-creation opportunity is real. The question is whether you’re equipped to capture it.
Subscribe to the Growth Shuttle research briefing for ongoing carve-out market analysis, and download the Carve-Out Attractiveness Scorecard to apply this framework to your current pipeline.