
You have two term sheets on your desk. One offers minority growth capital at a higher valuation, betting on your trajectory. The other proposes a control buyout at a lower headline number but with a clear operational thesis. Both claim they can double your enterprise value in five years. But they are betting on completely different things, and choosing wrong will cost you more than dilution. It will cost you the next phase of your company.
The growth equity vs buyout decision is not about which investor writes the bigger check. It is about which return engine matches your business reality. Growth equity investors need your revenue to compound. Buyout investors need your operations to transform. These are different bets with different dependencies, and the wrong match creates friction that neither side can fix with capital alone.
This framework helps you distinguish the two theses, understand what each demands from your business, and make a decision you can defend when the deal closes and the real work begins.
Two Different Return Engines, Not Two Labels
The labels “growth equity” and “buyout” suggest a spectrum. They are actually two distinct machines that generate returns through different mechanisms. Confusing them leads to misaligned expectations, board conflicts, and value-creation plans that fight the underlying economics of your business.
The Growth Equity Engine
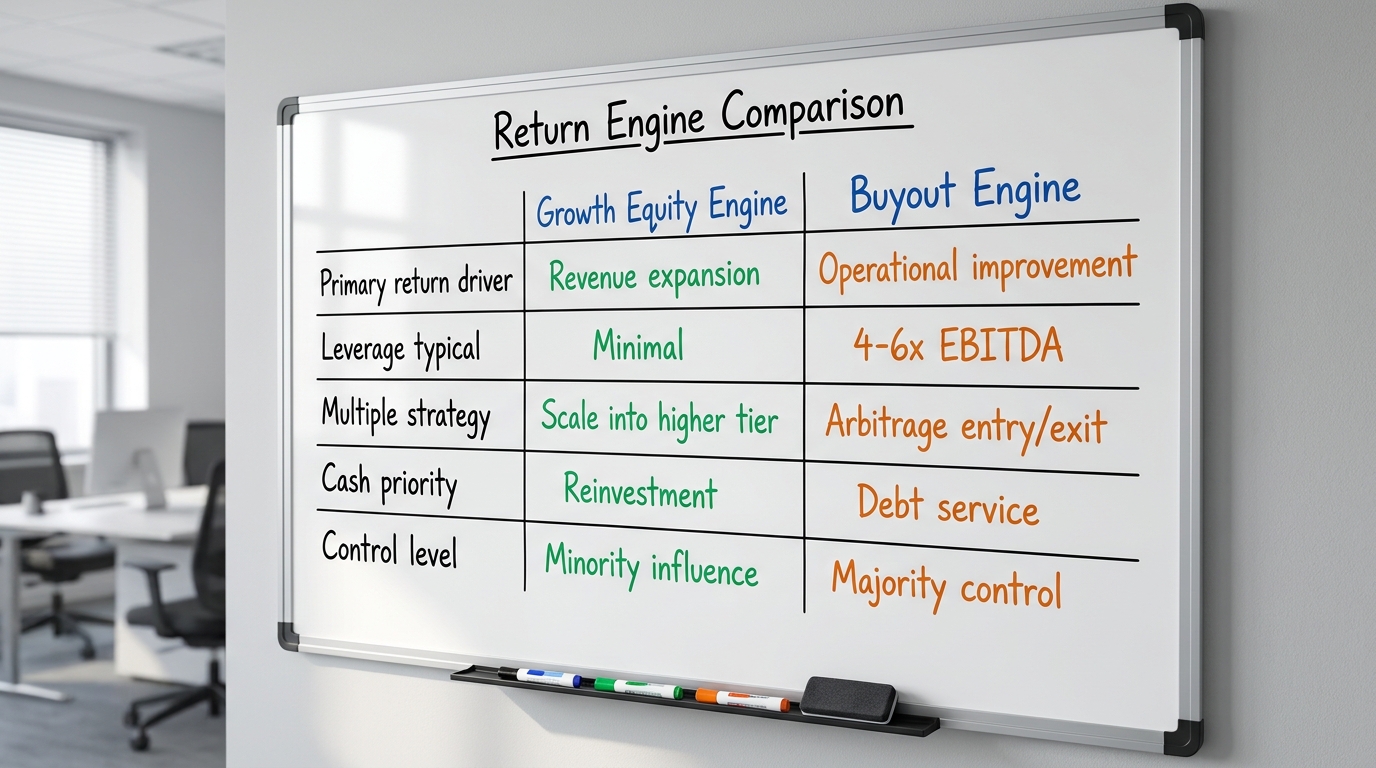
Growth equity investors generate returns primarily through revenue expansion and multiple expansion. They are betting that your company will grow into a higher valuation tier. According to Bain’s Global Private Equity Report 2024, growth equity funds target companies growing at 20% or more annually, with the expectation that sustained growth will support higher exit multiples.
The return math is straightforward: if revenue triples and the multiple holds, the investment triples. If revenue triples and the multiple expands because the company is now at a different scale, returns can reach 4x to 6x. Margin improvement is a bonus, not the thesis.
The Buyout Engine
Control buyouts generate returns through a combination of leverage, operational improvement, and multiple arbitrage. The debt structure means equity holders capture outsized gains from incremental EBITDA growth. A McKinsey analysis of private equity value creation found that approximately 50% of buyout returns historically came from leverage and multiple expansion, with operational improvement contributing the remainder.
The return math depends on cash generation: if EBITDA grows 30% while debt is paid down, the equity value can double even if the exit multiple compresses slightly. Revenue growth is helpful but not required.
When evaluating a private equity investment thesis, the first question is which engine the investor is running. Everything else follows from that.
What control versus influence actually changes in value creation
The minority versus majority distinction is not just about governance documents. It determines who owns the value-creation plan and who can actually execute it.
What Control Actually Means
In a control buyout, the private equity firm has the authority to replace management, change strategy, restructure operations, and force an exit. This authority lets them underwrite operational improvements into their return model. They can promise their LPs that specific changes will happen because they have the contractual power to make them happen.
This authority comes with accountability. Buyout firms cannot blame management for execution failures. They own the outcome, which means they tend to be conservative in their operational assumptions and aggressive in their monitoring.
What Influence Actually Means
Minority growth investing means the firm has board seats, information rights, and protective provisions, but not control. They cannot fire the CEO unilaterally. They cannot force a sale. They are betting that the founder or management team will execute the growth plan, and their role is to support that execution with capital, expertise, and connections.
This structure works when the management team is strong and aligned. It fails when execution problems emerge that require structural changes management will not make. Growth equity investors have limited tools when their portfolio company stalls.
Implications for Your Business
If your company needs operational transformation, growth equity cannot deliver it. A minority investor cannot restructure your sales organization, replace your CFO against your wishes, or force you to exit a product line. They can suggest, advise, and eventually threaten to block future rounds, but they cannot act.
If your company needs capital to accelerate a working model, a control buyout may overcomplicate the situation. Buyout firms justify their ownership premium by making changes. A business that does not need changes will generate friction as the firm looks for ways to add value beyond the capital itself.
How leverage, cash generation and the multiple interact
The financial engineering in each structure creates different pressures and different risk profiles. Understanding these mechanics helps you anticipate what life will be like after the deal closes.
Buyout Leverage Mechanics
Control buyouts typically involve debt at 4x to 6x EBITDA, sometimes higher in favorable credit markets. According to S&P Global Market Intelligence, median leverage multiples for middle market buyouts in 2023 were approximately 5.2x total debt to EBITDA.
This leverage creates several operational realities:
- Cash discipline becomes mandatory. The debt service consumes cash flow, leaving less for discretionary investment. Growth initiatives compete with interest payments.
- Margin focus intensifies. Every point of EBITDA margin expansion directly increases the company’s ability to service debt and pay down principal.
- Exit timing matters. The fund needs to exit within its investment period. A company that has not deleveraged by year four faces difficult choices.
Growth Equity Capital Structure
Growth equity transactions are typically all-equity or involve minimal debt. The capital goes onto the balance sheet to fund growth, not into sellers’ pockets through leverage. This creates different realities:
- Cash is available for investment. Without debt service, the company can reinvest in sales, product, and expansion. Short-term profitability is sacrificed for growth.
- Burn rate becomes the constraint. Growth equity companies often operate at break-even or modest losses. The question is runway, not covenant compliance.
- Exit timing is more flexible. Growth equity firms can hold longer if the growth story is intact, though they still face fund life constraints.
Multiple Dynamics
Both structures depend on exit multiples, but they depend on them differently. A BCG study of private equity returns found that multiple expansion contributed roughly 30% of buyout value creation over the past decade.
Growth equity investors are betting on multiple expansion as companies scale into higher valuation tiers. A $20 million revenue company might trade at 3x revenue, while a $100 million company in the same sector trades at 5x. The growth itself creates the multiple expansion.
Buyout investors are more focused on multiple arbitrage, buying at lower multiples through operational complexity or ownership transitions, then selling at market multiples after improvements. They are less dependent on rising markets.
Understanding the role of leverage and multiples is essential to evaluating private equity value creation in either structure.
Growth durability versus operational fixability
Each return engine carries different risks. The question is not which structure is safer, but which risks match your business situation and which risks you can actually manage.
Risks in the Growth Equity Thesis
Growth equity fails when growth stalls. The entire return depends on revenue compounding at high rates for five or more years. The risks that break this thesis include:
- Market saturation. The addressable market is smaller than modeled, and growth slows before the company reaches target scale.
- Competitive pressure. New entrants or incumbents erode unit economics, making growth unprofitable.
- Execution limits. The management team that built the company to $20 million cannot operate it at $100 million.
- Customer concentration. Growth depends on a few large customers whose behavior cannot be predicted.
The fundamental risk is growth durability. Is the trajectory real, and can it persist long enough to generate returns?
Risks in the Buyout Thesis
Buyouts fail when operations cannot be fixed or when leverage becomes unserviceable. The risks that break this thesis include:
- Revenue decline. The company loses revenue faster than operations can be improved, and EBITDA falls despite margin gains.
- Integration failures. The expected synergies from operational changes do not materialize, or they take longer than projected.
- Leverage stress. Interest rates rise or EBITDA falls, and the company cannot service its debt.
- Management gaps. The firm underestimates the difficulty of operational transformation or cannot recruit the right operators.
The fundamental risk is operational fixability. Can the problems be solved within the hold period, and can the company generate enough cash to survive while they are solved?
Matching Risk to Reality
I have seen founders take growth equity when their growth was already slowing, hoping the capital would restart the engine. It rarely does. Capital does not create demand. And I have seen owners take buyout offers when their companies were growing nicely, only to watch the new owners strip investment and stall momentum.
The question is not which structure you prefer. It is which risk profile matches your business. A company with durable competitive advantages and a large addressable market is a growth equity candidate. A company with operational complexity and improvement potential is a buyout candidate.
Signals that a business fits one engine over the other
Before negotiating terms, you need clarity on which structure your business actually supports. These signals help you assess fit.
Signals Pointing Toward Growth Equity
Consider growth capital when your business shows these characteristics:
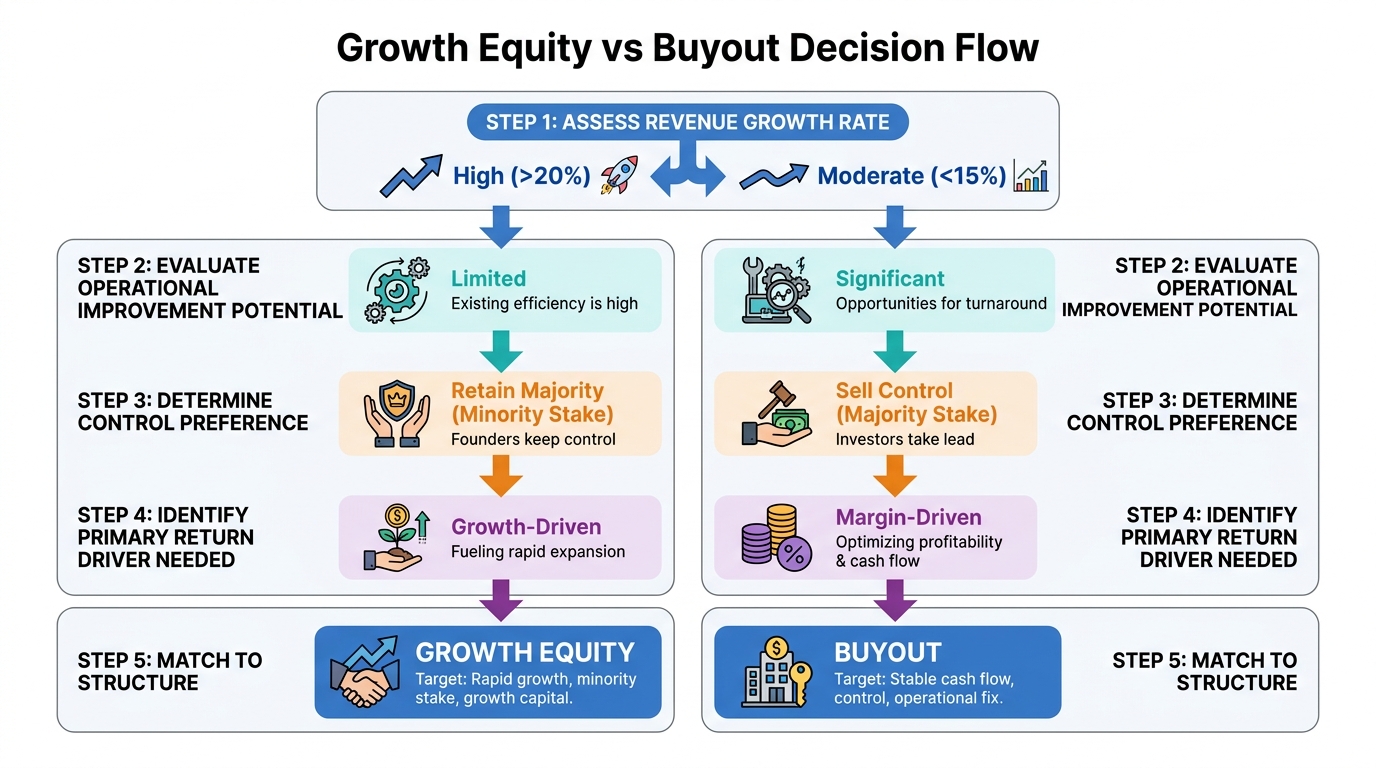
- Revenue is compounding above 20% annually. Growth equity investors need high growth to make their math work. If you are growing at 10%, the multiple expansion will not be sufficient.
- Unit economics are proven but not maximized. You know how to acquire customers profitably but need capital to do it at scale.
- The market opportunity is large and underpenetrated. You have runway to grow for years before hitting saturation.
- Management is strong and aligned. You do not need outside operators to run the business. You need capital and support.
- You want to retain control and continue building. Your goal is to lead the company through its next phase, not to exit.
Signals Pointing Toward Buyout
Consider a control buyout when your business shows these characteristics:
- The business is profitable but underleveraged. You have strong cash flow but have not optimized operations, and the balance sheet can support debt.
- Growth has slowed but the market position is defensible. You are a leader in a stable market with room for margin improvement.
- Operational complexity creates improvement opportunity. There are obvious inefficiencies that have not been addressed, perhaps because you lacked focus or expertise.
- Succession is a priority. You want to transition out of the business, partially or fully, and need a buyer who will operate it.
- The company would benefit from professionalization. Systems, processes, and governance need upgrading that you cannot or will not do yourself.
For founders exploring options in the middle market private equity space, these signals help narrow the field before conversations begin.
Strategy-Fit Decision Matrix
This matrix translates the framework into a practical tool. Use it to assess where your business sits and which structure aligns with your situation.
| Factor | Growth Equity Fit | Buyout Fit |
|---|---|---|
| Revenue Growth Rate | 20%+ annually, accelerating or steady | 0-15%, stable or declining modestly |
| EBITDA Margin | Modest or negative, with path to profitability | 15%+ with improvement potential |
| Operational Complexity | Simple, scalable model | Multiple levers for improvement |
| Management Strength | Strong team that will execute independently | Capable but needs support or replacement |
| Capital Use | Fuel growth (sales, product, expansion) | Acquisition, debt paydown, operations |
| Control Preference | Retain majority, take minority capital | Open to selling control stake |
| Exit Horizon | 5-7 years, growth-dependent | 4-6 years, transformation-dependent |
| Primary Return Driver | Revenue growth + multiple expansion | EBITDA improvement + debt paydown |
| Risk Tolerance | Can absorb growth volatility | Can absorb leverage risk |
| Value-Creation Logic | Scale the existing model faster | Transform operations and structure |
Score your business on each factor. If most factors point clearly in one direction, you have a strong fit signal. If the factors split, you may be in hybrid territory, which carries its own challenges.
Hybrid situations and where they break
The clean framework helps clarify the poles. But some businesses sit in between, and some deals try to blend structures. These hybrids deserve scrutiny.
The Growth-at-Scale Problem
Some companies have growth equity characteristics (high growth, large market) but also have operational complexity that demands structural change. A fast-growing software company with a broken sales organization is an example. Growth equity will provide capital but not fix the sales problem. A buyout will fix the sales problem but may constrain the investment needed for growth.
These situations often require a growth equity structure with strong operational support, which limits the field to firms that can actually provide both. Many cannot.
The Stable-but-Stagnant Problem
Some businesses fit buyout criteria (stable cash flow, improvement potential) but have a hidden growth opportunity that requires investment. A traditional manufacturer with a nascent software offering is an example. A buyout focused on cost cutting might kill the growth opportunity. Growth equity would not take the deal because the core is not growing.
These situations often require creative structuring or a specific buyer thesis that values both the cash flow and the option value.
The Minority-Buyout Trap
Some deals are structured as minority investments but carry buyout-like governance provisions. The investor takes 30% but has board control, approval rights over major decisions, and redemption provisions that force a sale. This is economically a control deal with minority pricing.
If you sign terms like these, you get the constraints of a buyout without the capital to support operational transformation. This structure benefits the investor, not the company.
When Hybrids Work
Hybrid structures work when both parties have explicit, aligned expectations about the thesis. A growth equity deal with an operational support package can work if the scope is defined. A buyout with a preserved growth investment budget can work if the commitment is contractual, not conversational.
The danger is ambiguity. If you and your investor are running different mental models of the deal, the conflict will emerge after closing, when it is expensive to resolve.
How the choice reshapes the value-creation plan
The structure you choose determines the playbook you will run for the next five years. This section maps the practical differences in value creation under each model.
Value Creation Under Growth Equity
A growth equity value-creation plan focuses on scaling what already works:
- Sales capacity. Hiring sales reps, building channels, expanding territories. The plan assumes unit economics hold at scale.
- Product investment. Building features that expand the addressable market or increase wallet share with existing customers.
- Geographic expansion. Entering new markets where the model can be replicated.
- Marketing investment. Brand building and demand generation to support the sales capacity.
The growth equity board meeting focuses on pipeline, bookings, retention, and burn rate. Margin improvement is a secondary consideration.
Value Creation Under Buyout
A buyout value-creation plan focuses on transformation and extraction:
- Cost structure. Reducing overhead, renegotiating contracts, consolidating operations. The plan assumes savings flow to EBITDA.
- Pricing optimization. Increasing prices where the market will bear it, often after years of underpricing by the prior owner.
- Working capital. Improving collections, managing inventory, extending payables. Cash generation is prioritized.
- Add-on acquisitions. A buy-and-build strategy to consolidate the market and create synergies.
- Management upgrades. Bringing in experienced operators to professionalize the organization.
The buyout board meeting focuses on EBITDA, cash flow, debt paydown, and integration progress. Revenue growth is monitored but not the primary metric.
Practical Implications for You
If you take growth equity, your job is to execute the growth plan. You will be measured on revenue, and you will be supported with capital to invest. The pressure is to perform on the top line.
If you take a buyout (assuming you stay with the company), your job is to execute the transformation plan. You will be measured on EBITDA and cash, and you will face constraints on discretionary spending. The pressure is to deliver on the promised improvements.
Neither is easier. They are different jobs. Choose the structure that matches the job you want to do and the business you actually have.
Applying the framework when you are actually making the decision
The framework provides clarity, but execution requires additional work. Here is how to apply it when you are actually making the decision.
Test Your Growth Durability
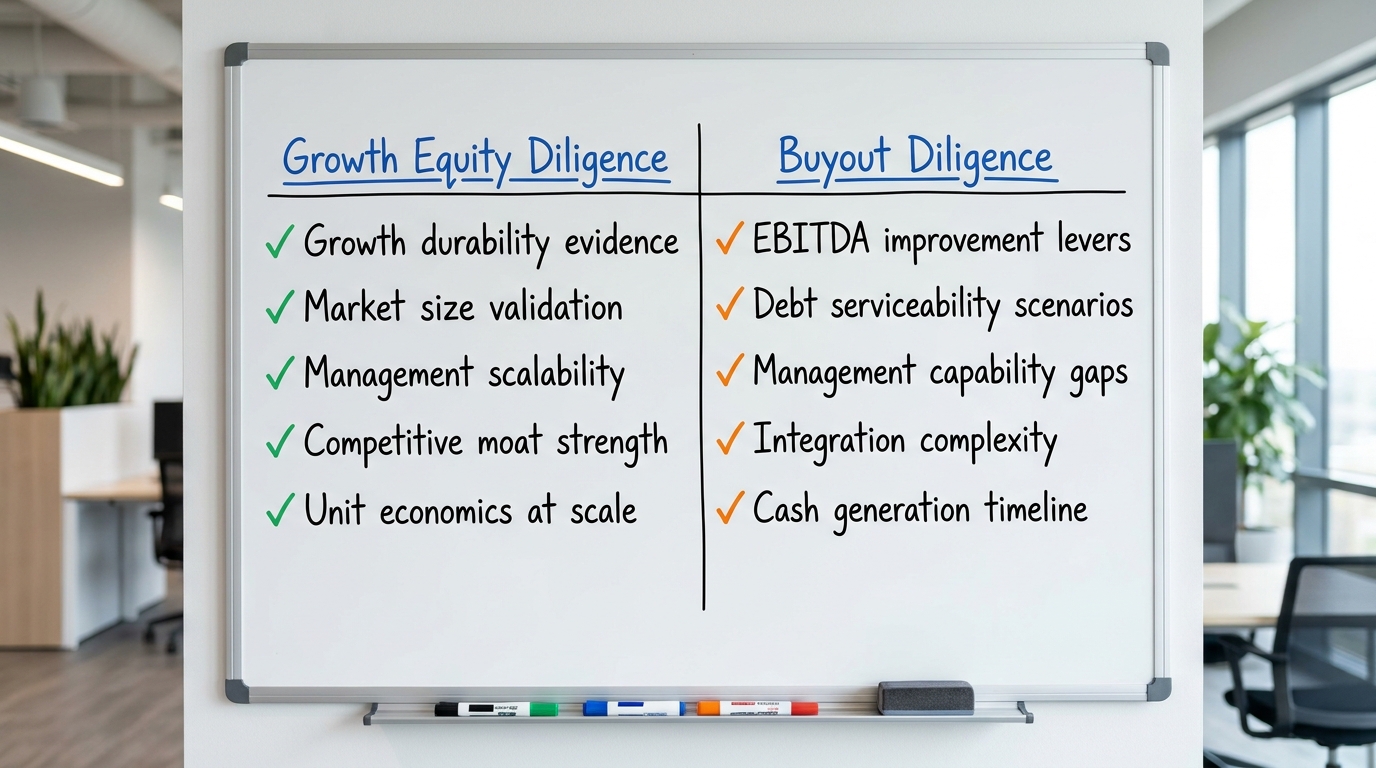
If you are considering growth equity, stress-test your growth thesis. Interview recent lost deals to understand why customers did not buy. Analyze cohort retention to see if growth is sustainable or leaky. Model your market share at target scale and ask whether it is realistic. Growth equity fails when growth was never as durable as it appeared.
Test Your Operational Fixability
If you are considering a buyout, stress-test your improvement thesis. List the specific operational changes that would improve EBITDA and estimate their impact. Assess whether your management team can execute those changes or whether new talent is required. Model the debt service at various interest rate scenarios. Buyouts fail when operations were harder to fix than they appeared.
Align with Your Goals
Beyond the business fit, consider your personal goals. Do you want to lead the company for another five years, or transition out? Do you want to retain control, or are you comfortable with a new majority owner? Are you energized by growth challenges or operational challenges?
The best fit on paper will fail if it does not match what you actually want to do next.
Vet the Specific Firm
Structures matter, but so do partners. Growth equity firms vary widely in how much operational support they actually provide. Buyout firms vary in how aggressively they cut versus invest. Reference calls with portfolio company CEOs are more valuable than pitch decks.
Ask specifically: what did the last three companies in my situation look like two years after close? The answer will tell you more than the marketing materials.
Summary checklist and final considerations
Before signing a term sheet, run through this checklist to confirm alignment between your business and the proposed structure.
Growth Equity Readiness:
- Revenue growing at 20%+ with a path to sustained growth
- Unit economics are positive and hold at scale
- Addressable market is large and underpenetrated
- Management team is strong and aligned with growth plan
- You want to retain majority control and continue leading
- Capital will fuel expansion, not fix operational problems
Buyout Readiness:
- EBITDA margins are strong with clear improvement potential
- Cash generation can support 4-6x leverage
- Operational complexity creates transformation opportunity
- Management needs support, upgrade, or transition
- You are open to selling control or exiting
- Capital will fund operations, acquisitions, or paydown
Red Flags (Either Structure):
- Investor thesis does not match your business profile
- Governance terms create more control than the equity stake implies
- Value-creation plan requires capabilities the investor lacks
- Exit expectations are misaligned with realistic outcomes
- Reference calls reveal patterns inconsistent with pitch claims
The growth equity vs buyout choice is not about investor preference. It is about matching the return engine to your business reality and your goals. Get that match right, and the capital becomes fuel. Get it wrong, and the capital becomes friction.
For ongoing private equity market intelligence, frameworks like this one provide the foundation for sound decisions. The details matter, and the details depend on your specific situation.
If you are navigating this choice and need help stress-testing the fit, DevriX supports middle-market operators with technical diligence and post-close execution for digital and SaaS assets.