

You are reviewing a platform acquisition priced at 12x EBITDA. The seller’s advisor calls it “in line with sector comps.” Your operating partner asks a sharper question: at that entry multiple, what combination of margin expansion, revenue growth, and debt paydown is required to hit your fund’s 2.5x gross return target over five years? If the answer demands 300 basis points of margin improvement in a business that has already been optimized, plus 12% organic growth in a market growing at 4%, the deal math is broken before you write the LOI.
This is the core tension with private equity valuation multiples in the current environment. Entry pricing has compressed the margin for error. The days when multiple expansion alone could deliver fund-level returns are largely behind us. What remains is operational value creation, and the entry multiple determines how much of it you need. This framework connects those two realities: the price you pay and the work required to earn your return.
For SMEs considering PE partnerships, selling to financial sponsors, or benchmarking their own valuations, understanding this dynamic is essential. The multiple is not an abstract number. It is a contract about future performance.
The entry multiple sets your return math before Day One
Every private equity return decomposes into three sources: EBITDA growth (through revenue or margin), multiple expansion at exit, and debt paydown from free cash flow. The entry multiple determines the relative contribution each source must make. Pay a low multiple, and modest operational improvement delivers strong returns. Pay a high multiple, and you need exceptional performance just to hit hurdle.
Consider the arithmetic. A deal purchased at 8x EBITDA and exited at 8x requires the business to grow EBITDA by roughly 2.5x over five years to deliver a 2.5x gross equity return (assuming moderate leverage). At 12x entry, the same exit multiple requires nearly 3.5x EBITDA growth. That is not a rounding error. It is the difference between achievable and aspirational.
Bain & Company’s Global Private Equity Report 2024 found that the share of PE returns attributable to multiple expansion has declined steadily since 2010, with operational improvement now accounting for the majority of value creation in successful deals. The implication is clear: the entry multiple is not just a price tag. It is a forecast of the operational intensity required.
When building your private equity investment thesis, the entry multiple should be the first input to your value creation plan, not an afterthought.
How multiples disperse across sector, size, and quality
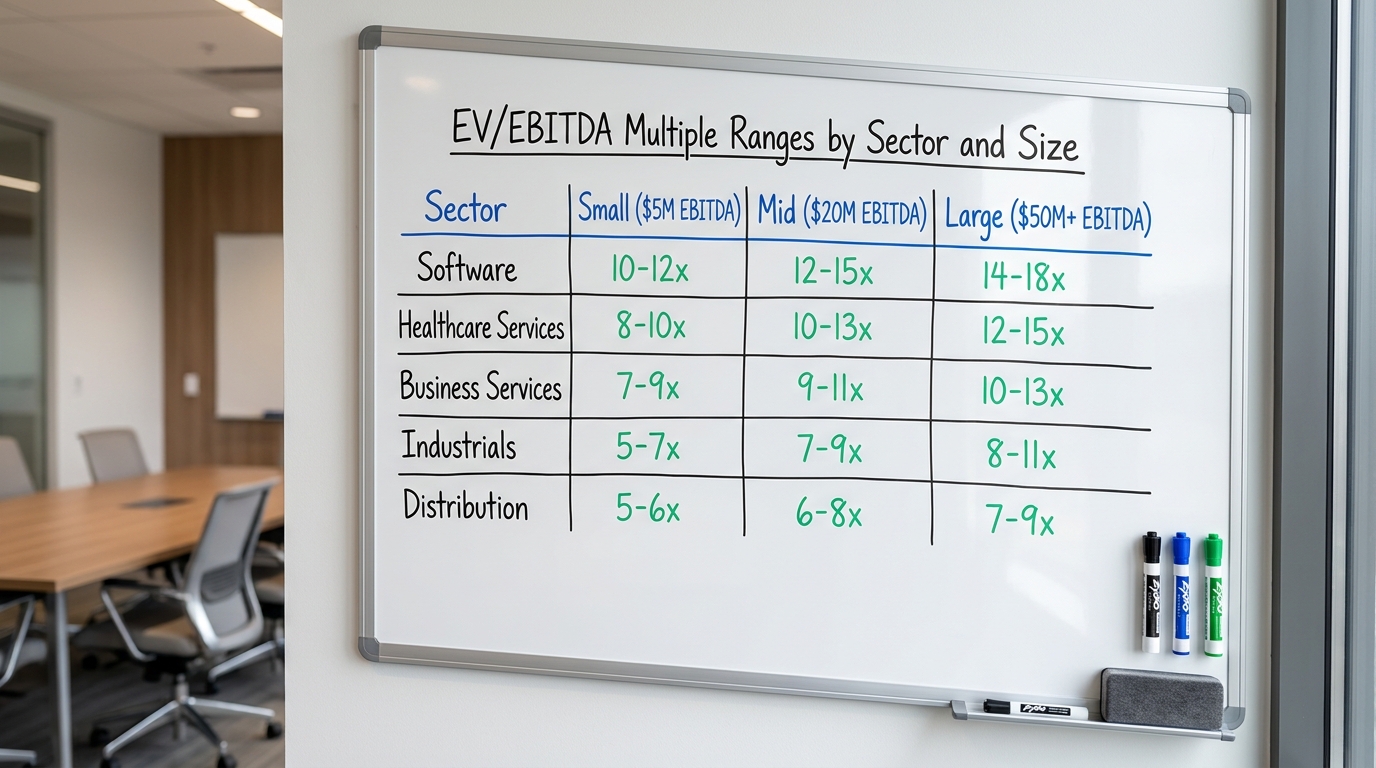
Private equity valuation multiples vary dramatically across sectors, company sizes, and quality tiers. Understanding this dispersion is critical for benchmarking whether a specific multiple represents opportunity or overreach.
Sector Dispersion
According to PitchBook’s Q4 2023 U.S. PE Breakdown, median EV/EBITDA multiples ranged from approximately 8x in industrials and distribution to over 14x in software and healthcare services. These gaps reflect fundamental differences in growth expectations, capital intensity, and margin stability.
Software commands premium multiples because of recurring revenue models, high gross margins, and the potential for operating leverage at scale. Industrial businesses trade at lower multiples because of cyclicality, capital requirements, and thinner margins. Neither is inherently better or worse as an investment. The question is whether the multiple paid reflects the realistic value creation opportunity.
Size Premium
Larger businesses consistently trade at higher multiples. A $5 million EBITDA business in a given sector might trade at 6-8x, while a $50 million EBITDA platform in the same sector commands 10-12x. This “size premium” reflects reduced key-person risk, more developed management teams, and broader buyer universes at exit.
For SMEs, this creates an important dynamic: your current valuation multiple may be lower than you expect, but the path to a higher exit multiple runs through professionalized operations and scale. Understanding where your business sits in the size continuum informs realistic expectations.
Quality Stratification
Within any sector and size band, “quality” assets, those with recurring revenue, demonstrated organic growth, diversified customer bases, and defensible market positions, trade at material premiums. McKinsey’s private equity practice has documented premiums of 2-4 turns for businesses exhibiting these characteristics versus sector peers.
The practical question is whether a business’s quality characteristics are durable through the hold period. A quality premium paid at entry must be preserved or enhanced at exit. If the quality degrades, so does the multiple.
Where returns come from now that multiple expansion has faded
The historical PE playbook relied heavily on buying at one multiple and selling at a higher one. This worked when debt was cheap, competition for deals was lower, and public market comparables were expanding. That playbook is largely exhausted.
The Math Has Changed
BCG’s 2023 analysis of PE returns found that multiple expansion contributed approximately 30% of total returns in funds from the 2000-2010 vintage years but has declined to under 15% for recent vintages. The remainder must come from EBITDA growth and debt paydown. The follow-on question is which operational levers actually produced that EBITDA growth across completed deals. What the data says about operational gains points consistently at commercial and digital execution, with cost programs carrying a smaller share than they did in earlier vintages.
This shift has profound implications for deal underwriting. If you assume exit at the same multiple you paid at entry (a “multiple neutral” assumption), your return depends entirely on how much you grow EBITDA and how efficiently you deleverage. If you assume multiple compression (exiting at a lower multiple than entry), you need even more operational improvement to compensate.
Where Expansion Still Exists
Multiple expansion remains achievable in specific circumstances. Building a platform through add-on acquisitions often creates a “multiple arbitrage” by buying smaller companies at 5-6x and consolidating into a larger platform that exits at 9-10x. This is not magic. It reflects the real size premium discussed earlier and requires genuine integration work to realize.
Similarly, transforming a project-based business into one with recurring revenue, or shifting from low-margin distribution to higher-margin value-added services, can justify a higher exit multiple. But these are operational achievements, not financial engineering.
For deeper analysis of where returns are actually being generated, explore our private equity value creation research.
How rising debt costs constrain entry pricing
The relationship between interest rates and sustainable entry multiples is mechanical, not theoretical. When the cost of debt rises, the cash flow available for operations, growth investment, and debt service shrinks. This constrains how much leverage a deal can support and, by extension, what multiple the equity can afford to pay.
The Leverage Equation
In a low-rate environment (base rates near zero, spreads of 400-500 basis points), a business could comfortably service 5-6x leverage with interest expense consuming perhaps 25-30% of EBITDA. At current rates (base rates of 4-5%, spreads of 500-600 basis points), the same leverage ratio might consume 40-50% of EBITDA in interest expense.
The S&P Global Leveraged Finance data shows that average debt multiples in PE transactions have declined from approximately 6x in 2021 to closer to 5x in 2023-2024. Lower leverage means sponsors must fund a larger portion of purchase prices with equity, which mathematically reduces returns unless entry multiples also compress.
Practical Implications
If debt is more expensive and less available, one of two things must happen: entry multiples must decline, or return expectations must reset. In competitive processes, multiples have proven sticky because of the volume of dry powder seeking deployment. The result is that many deals underwritten in 2022-2024 carry elevated risk profiles.
For SMEs, this means the financing environment directly affects your valuation. A buyer who cannot access cheap leverage cannot pay the same multiple, regardless of your business quality. Understanding private equity market trends in financing helps you calibrate timing and expectations.
Signs a multiple is defensible versus a bet on hope
Not every high multiple is a mistake, and not every low multiple is a bargain. The question is whether the multiple is defensible given the business’s characteristics and the realistic value creation opportunity.
Defensible High Multiples
A premium multiple can be justified when several conditions exist:
- Predictable revenue: Contracted or recurring revenue reduces execution risk and supports valuation confidence.
- Demonstrated organic growth: Historical growth above market rates, sustained over multiple years, provides evidence of competitive advantage.
- Margin expansion runway: Clear, identifiable opportunities to improve margins (not hypothetical “synergies” but specific operational changes).
- Fragmented market for consolidation: A realistic buy-and-build opportunity with identified targets and a logical integration playbook.
- Management continuity: A team that will execute the value creation plan, not just collect their earnout and disengage.
Warning Signs of a Stretched Multiple
Conversely, certain patterns suggest a multiple may be unsupportable:
- Reliance on market growth alone: If the underwriting assumes the business will grow simply because its market is growing, without specific drivers, the case is weak.
- Margin improvement without operational specificity: “We’ll improve margins by 200 basis points through operational excellence” is not a plan. What operations? What changes? What capital required?
- Exit multiple above entry: Unless there is a clear thesis for why the multiple should expand (transformation, scale, quality shift), assuming exit multiple expansion is hope, not strategy.
- Customer concentration risk: If 30%+ of revenue comes from one customer, the multiple should reflect that risk, not ignore it.
- Cyclical peak earnings: EBITDA multiples applied to peak-cycle earnings produce inflated valuations. Normalize before applying any multiple.

When paying up for genuine compounders makes sense
The framework above might suggest that high multiples are always dangerous. That is not the case. Some businesses genuinely compound value at rates that justify premium entry pricing. The discipline is distinguishing real compounders from businesses that merely look the part.
What Compounders Look Like
A genuine compounder exhibits several characteristics:
- Unit economics that improve with scale: Customer acquisition costs decline, lifetime value increases, and gross margins expand as the business grows.
- Durable competitive moats: Network effects, switching costs, proprietary data, or regulatory barriers that protect the business from competition.
- Reinvestment opportunities at high ROIC: The ability to deploy capital into growth at returns well above the cost of capital.
- Management with a track record of capital allocation: Leaders who have demonstrated the ability to deploy capital wisely, not just grow revenue.
The Berkshire Test
Warren Buffett has famously articulated the logic of paying premium prices for exceptional businesses: “It’s far better to buy a wonderful company at a fair price than a fair company at a wonderful price.” In PE terms, this means a 14x entry multiple for a business that can compound EBITDA at 20% annually may outperform a 7x entry multiple for a business that grows at 5%.
However, the PE holding period creates a constraint that public market investors do not face. A compounder needs time to demonstrate its compounding. Over a 5-7 year hold, there may not be enough time for compound growth to overcome a very high entry multiple. The math favors compounders over long holding periods and moderate multiples over short ones.
Practical Application
If you are evaluating a deal at a premium multiple, pressure-test the compounding thesis. What is the historical growth rate? What is the reinvestment rate? What is the return on incremental capital? If you cannot answer these questions with evidence, you may be paying a compounder multiple for a non-compounder business.
The value creation burden implied by today’s pricing
Current entry multiples in many sectors imply a value creation burden that is historically unusual. Understanding this burden helps calibrate deal selection and operational planning.
Benchmarking the Burden
According to Hamilton Lane’s Market Overview, median entry multiples for PE transactions have increased from approximately 9x EBITDA in 2012-2015 to over 11x in 2021-2023. At the same time, exit multiples have not risen proportionally, and in some sectors have compressed.
The math is unforgiving. At 11x entry, even assuming multiple-neutral exits, a sponsor needs to roughly double EBITDA over five years to achieve a 2x gross return with moderate leverage. At 13x entry, EBITDA needs to grow 2.5x. At 15x, over 3x.
Where This Matters for SMEs
If you are an SME owner approached by PE, the entry multiple conversation is also a conversation about what you will be asked to deliver post-close. A buyer paying a high multiple will have aggressive expectations. A buyer paying a moderate multiple may be more patient and partnership-oriented.
Understanding this dynamic helps you select the right partner. For a comprehensive view of how to think about PE engagement, visit our private equity market intelligence hub.
Mapping entry multiples to required performance
The following worksheet operationalizes the framework. It allows you to map an entry multiple to the specific combination of growth, margin improvement, and deleveraging required to hit a target return.
The Core Formula
Equity return in a leveraged buyout can be approximated as:
Exit Equity Value = (Exit EBITDA × Exit Multiple) − Exit Debt
Gross Multiple of Money = Exit Equity Value ÷ Entry Equity Value
Entry Equity Value is the portion of the purchase price funded with equity (Purchase Price minus Debt). Exit EBITDA is a function of entry EBITDA, revenue growth, and margin change. Exit Debt is entry debt minus cumulative debt paydown from free cash flow.
Usable Return-Bridge Table
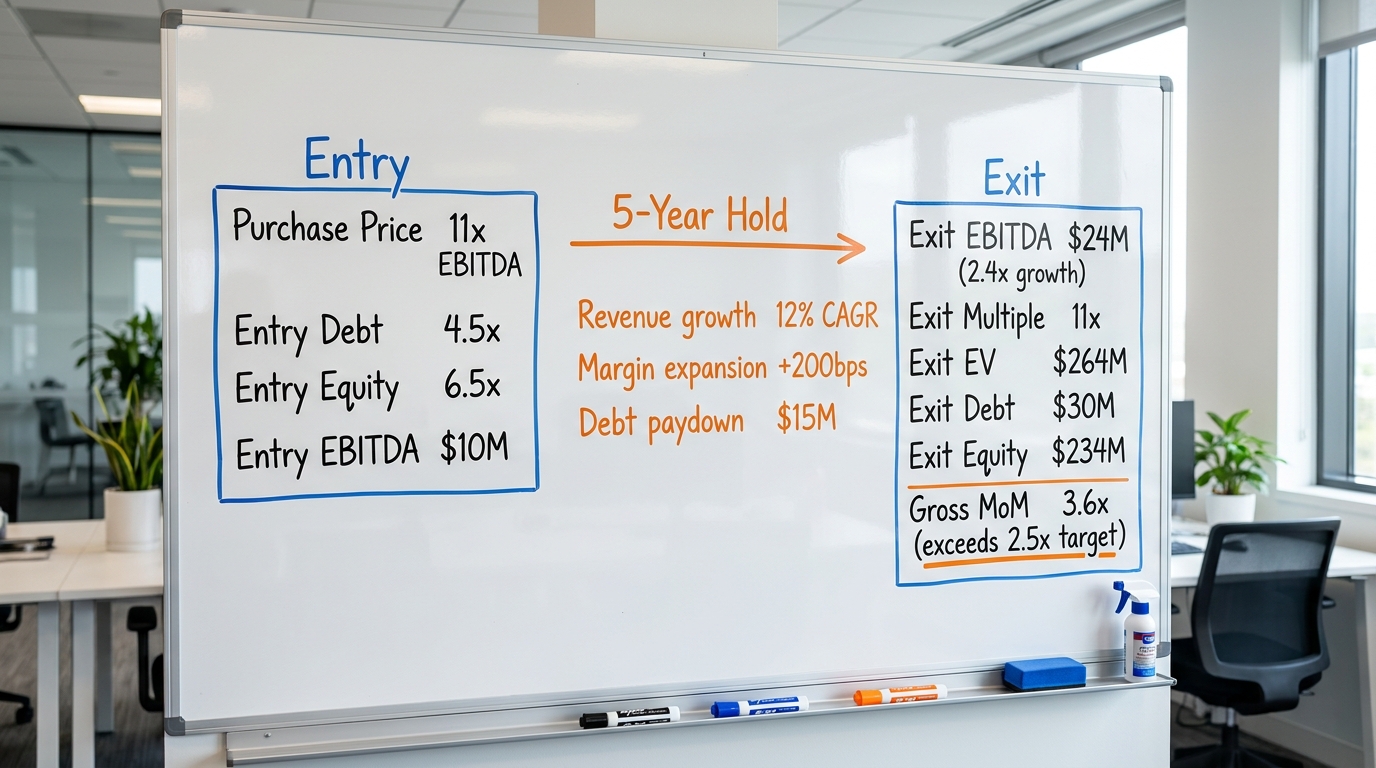
The following table shows the EBITDA growth required to achieve a 2.5x gross return over five years at various entry multiples, assuming: entry leverage of 4.5x EBITDA, exit multiple equal to entry multiple, and debt paydown of 1.5x EBITDA over the hold period. These are illustrative assumptions. Your deal will differ.
| Entry Multiple (EV/EBITDA) | Entry Equity (as % of EV) | Required EBITDA Growth (5yr) | Implied EBITDA CAGR | Value Creation Intensity |
|---|---|---|---|---|
| 7x | 36% | 1.6x | 10% | Moderate |
| 9x | 50% | 2.0x | 15% | Elevated |
| 11x | 59% | 2.4x | 19% | High |
| 13x | 65% | 2.9x | 24% | Very High |
| 15x | 70% | 3.4x | 28% | Exceptional |
How to Use This Table
- Identify your entry multiple. What EV/EBITDA is the deal priced at?
- Find the required EBITDA growth. This tells you how much the business must grow over five years to hit a 2.5x return.
- Decompose EBITDA growth into revenue and margin. If EBITDA must grow 2.4x, is that realistic through 15% revenue growth and 300bps margin expansion? Or does it require 25% revenue growth with flat margins? Test multiple scenarios.
- Stress-test with multiple compression. What if exit multiple is 1-2 turns lower than entry? Re-run the math. If the deal breaks, you are dependent on market conditions you cannot control.
- Validate against the value creation plan. Do you have specific, identified initiatives that deliver the required EBITDA growth? If not, the return is theoretical.
Decomposing growth: revenue-led versus margin-led plans
The return bridge can be achieved through different combinations of revenue growth and margin expansion. The right mix depends on the business’s characteristics and realistic opportunities.
Revenue-Led Value Creation
Revenue growth is the right primary lever when:
- The market is growing and the business has competitive positioning to capture share
- There are identified geographic or product expansion opportunities
- Customer acquisition economics are favorable (CAC payback under 18 months)
- The business has operating leverage (incremental revenue drops to EBITDA at high rates)
The risk with revenue-led plans is execution complexity. New markets, new products, and new customers all carry uncertainty. Revenue plans that assume 20%+ growth in markets growing at 5% require share gains that may not materialize.
Margin-Led Value Creation
Margin expansion is the right primary lever when:
- The business has demonstrably below-benchmark margins versus peers
- Specific operational inefficiencies are identified (procurement, labor productivity, overhead)
- Pricing power exists but has not been exercised
- Scale benefits are available through consolidation
The risk with margin-led plans is that they often require upfront investment (systems, people, restructuring) and may hit natural limits. A business already at peer-leading margins has limited runway. A business with structural cost disadvantages may not close the gap regardless of effort. The systems half of that upfront investment is where the cost estimates usually break. A fractional CTO retainer gives the sponsor a sized view of the migration, the integration work and the headcount required before the margin plan gets written into the model.
The Balanced Approach
Most successful value creation plans combine modest revenue growth with meaningful margin improvement. This diversifies execution risk and creates multiple paths to the return target. A plan requiring 25% revenue CAGR is fragile. A plan requiring 10% revenue CAGR plus 300bps margin expansion has more degrees of freedom.
Planning for exit multiple risk over the holding period
Entry multiples get attention, but exit multiples determine realized returns. Planning for exit multiple risk is essential.
What Drives Exit Multiples
Exit multiples depend on factors largely outside your control:
- Capital market conditions: Availability of debt, appetite of strategic buyers, and PE fund deployment pressure all affect what buyers can pay.
- Sector sentiment: Sectors move in and out of favor. A hot sector today may be out of favor in five years.
- Size at exit: If you have grown the business, the natural buyer universe may be different, potentially commanding a higher multiple.
- Quality improvements: If you have improved revenue quality (recurring vs. project), customer concentration, or management depth, you may exit at a premium to entry.
Scenario Planning for Exit
Run three exit scenarios: base (multiple neutral to entry), downside (1-2 turns compression), and upside (1-2 turns expansion). If the deal requires the upside scenario to hit your return target, the risk profile is elevated. A good deal should work in the base case and survive the downside. The controllable half of the exit multiple is the asset itself. An exit readiness review, run 12 to 18 months ahead of a process, tells you which quality gaps a buyer will price against while there is still hold period left to close them.
Understanding how exits are executed and what drives exit value is critical. Explore our private equity exit strategies analysis for deeper perspective.
When the math tells you to walk away
The framework and worksheet above are decision tools. They help you build conviction when the math works and walk away when it does not.
When to Lean In
If your return-bridge analysis shows a realistic path to target returns through identified, specific value creation initiatives, and the plan survives stress-testing on exit multiples, the deal may warrant pursuit. High entry multiples are not disqualifying if they are supported by genuine opportunity.
When to Walk Away
If the return bridge requires growth rates the business has never achieved, margin improvements without operational specificity, or exit multiple expansion in a sector where multiples are contracting, the deal is a gamble on hope. Walking away is often the highest-return decision.
The Discipline Differential
PE firms that outperform over cycles are not necessarily smarter. They are more disciplined about entry pricing. They run this math before every deal, and they walk away when the math does not work. That discipline is the edge.
Summary and Action Checklist
Private equity valuation multiples are not abstract metrics. They are contracts about future performance. The entry multiple determines the value creation burden. The value creation plan determines whether that burden is realistic. The exit multiple determines whether the return is realized.
Key Takeaways
- The entry multiple sets the return math before any operational work begins
- EV/EBITDA multiples vary by sector (6x to 16x), size (2-4 turn premium for scale), and quality (2-3 turn premium for recurring revenue and growth)
- Multiple expansion has declined as a return source. Operational improvement now drives the majority of PE returns
- Higher debt costs reduce sustainable leverage, which either compresses returns or requires lower entry multiples
- Defensible high multiples require recurring revenue, demonstrated growth, specific margin levers, and realistic M&A opportunities
- Paying up for genuine compounders can work, but requires evidence of compounding, not assumption
- Today’s elevated multiples imply value creation burdens of 2-3x EBITDA growth over five years for typical return targets
Pre-LOI Checklist
- ☐ Calculate the required EBITDA growth for your target return using the return-bridge worksheet
- ☐ Decompose required growth into revenue and margin components
- ☐ Validate each component against specific, identified initiatives
- ☐ Stress-test with exit multiple compression of 1-2 turns
- ☐ Benchmark the entry multiple against sector, size, and quality comparables
- ☐ Assess whether premium multiple characteristics (recurring revenue, growth, moats) are durable through the hold period
- ☐ Document the thesis: if you cannot articulate why this multiple is defensible in one paragraph, it probably is not
Subscribe to the Growth Shuttle research briefing for the valuation-environment briefing, and download the Return-Bridge Worksheet to apply this framework to your next deal or valuation conversation.