

You signed the LOI, the QoE lands next week, and someone on the deal team asks the question that decides whether this is a good deal or a slow bleed: can this business actually deliver the plan you underwrote? Not the revenue plan. The operational one. Can it ship, staff, fulfill, service and scale at the volumes your model assumes, without the margin quietly eroding under integration cost, key-person risk and systems that cannot take the load?
That is the job of operations due diligence, and in private equity it is where a lot of value creation plans go to die. Commercial diligence tells you the market wants more of what the target sells. Operations diligence tells you whether the target can make and deliver more of it at the margin you paid for. If you are an operating partner, a portfolio-company CEO inheriting a mandate, or a deal lead trying to decide what to fund in the first hundred days, this is the workstream that turns a thesis into a defensible number. This guide covers what you actually need to decide, how to scope the work, and how to tell a real operations diligence effort from an expensive activity report.
Operations diligence decides more deals than it gets credit for
Most deal teams weight financial and commercial diligence heavily and treat operations as a confirmatory checkbox. That ordering makes sense on paper and fails in practice, because the operating model is where the value creation plan either has room to run or does not. Bain’s annual private equity report has documented for years that multiple expansion is a weaker driver of returns than it was, which pushes the burden onto margin and revenue improvement that operations has to deliver. You can read the current view in Bain’s Global Private Equity Report.
The commercial consequence is direct. If your model assumes a 400-basis-point EBITDA improvement from operational leverage and the operations diligence surfaces that the plant, the ERP, the service desk or the delivery org cannot absorb the volume without new fixed cost, you did not buy a margin story. You bought a capex story with a longer payback. That is a different deal, and you want to know before close, not in the second board meeting.
Operations diligence sits alongside buy-side commercial due diligence, not underneath it. Commercial confirms demand. Operations confirms deliverability. When those two disagree, you have found the real risk in the deal.
What operations diligence is actually deciding
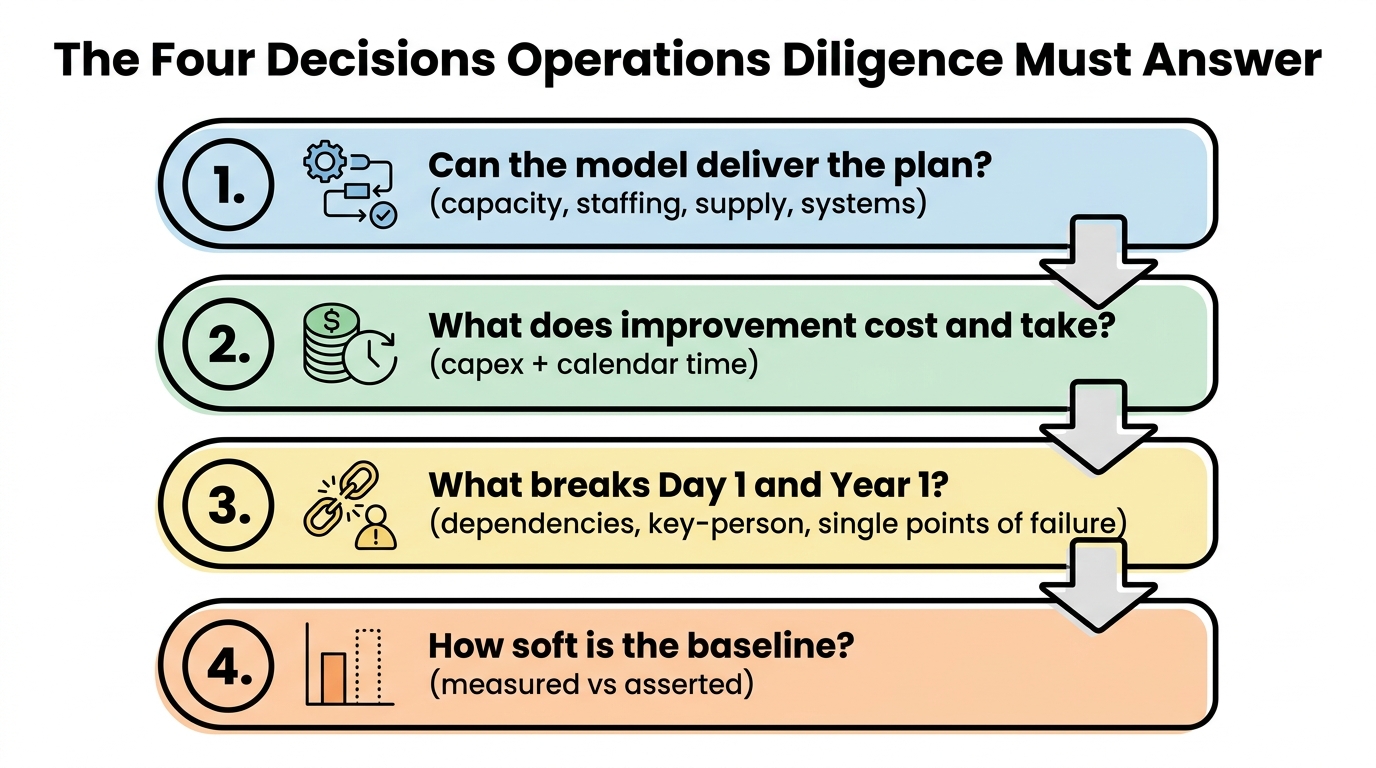
Do not let the scope drift into a general audit. An operations diligence effort exists to answer a small set of decision questions, and every hour spent should map to one of them:
- Can the operating model deliver the plan? At the volumes and mix your model assumes, does capacity, staffing, supply and systems hold, and at what incremental cost.
- What does the improvement actually cost and take? The value creation plan promises savings and throughput gains. Are they realized, run-rate, or forecast, and what capital and calendar time do they require.
- What breaks on Day 1 and in the first year? Which dependencies, contracts, licenses, key people or single points of failure create integration or continuity risk.
- Where is the operating baseline soft? What is measured versus asserted, and how much of the reported performance survives a hard look at the underlying data.
Notice what is not on that list: a generic maturity assessment, a benchmarking deck against unnamed peers, or a list of best practices. Those are outputs vendors produce when they were not given a decision to serve. Your scope document should name the decision, the owner of the decision, and the evidence that would change it.
Scope the workstream before anyone starts collecting documents
The failure mode I see repeatedly is a diligence team that starts pulling documents before anyone has defined what a pass or a fail looks like. You end up with a warehouse of information and no verdict. Set the frame first.
Define the operational thesis in one page
Write down what the deal assumes operationally. Example, and this is an illustrative scenario, not a real deal: “We assume we can raise fulfillment throughput 30 percent within 18 months by consolidating two distribution centers and standardizing the WMS, at under two million in capex, holding service levels flat.” Now you have something to prove or disprove. Every workstream below hangs off that sentence.
Set the decision rights
Name who owns the go/no-go on operational risk, who owns the value creation plan sizing, and who signs off that the integration cost is in the model. On mid-market deals these are often the same two or three people. Write it down anyway, because the disagreements you want to surface are between those roles.
Time-box against the deal calendar
Confirmatory diligence windows are short. McKinsey’s private capital research has repeatedly noted how compressed diligence has become in competitive processes, and you can see the broader body of their work at McKinsey. Scope to the calendar you have, not the one you wish you had, and be explicit about what you are deliberately not covering.
The operating baseline, and why most of them are soft
Before you can judge whether operations can deliver more, you need a defensible picture of what it delivers now. This is the single most under-invested part of operations diligence, and it is where deals get repriced after close.
The reported operating metrics (on-time delivery, utilization, first-pass yield, cost per unit, service resolution time) are frequently assembled by hand, pulled from spreadsheets that live on one person’s laptop, and reconciled to nothing. The moment you ask how a number is calculated and whether the same definition held for the last three years, a surprising amount of the operating story softens.
This overlaps heavily with data quality, and the same problems that survive a Quality of Earnings review survive operations diligence. If you have not already, the failure modes in data due diligence for private equity map almost one to one onto operational reporting. A metric that cannot be reproduced from source systems is not a baseline. It is a claim.
What to demand as evidence
- The definition of each key operating metric, written down, and the query or process that produces it.
- The same metric pulled twice, once from the management deck and once from the source system, and the reconciliation between them.
- A time series long enough to see seasonality and one-time distortions, not a single trailing quarter.
When management cannot produce a metric from source, that is itself a finding. It tells you the business runs on judgment rather than instrumentation, which changes both your risk register and your first-hundred-days priorities.
Capacity and the volume assumption in your model
Your model has a volume ramp. Operations diligence has to test whether the operating model absorbs it. This is concrete work, not a maturity score.
Trace the ramp through the constraint
Every operation has a binding constraint (a machine, a shift pattern, a warehouse footprint, a licensed capacity, a lead engineer, a support queue). Find it, then ask what happens to it at the volume your model assumes in year two and year three. The answer is usually one of three: it holds, it needs incremental variable cost, or it needs a step change in fixed cost. Only the first one is free margin. The other two belong in the model, sized and dated.
Separate variable scaling from step-function scaling
A support org that scales by hiring is a variable cost that erodes the margin story gently. A distribution network that needs a new node at a volume threshold is a step function that hits cash and EBITDA in a single quarter. Your value creation plan should treat these differently, and your diligence should flag which is which. Classify each improvement you are underwriting as realized today, run-rate, or forecast, so nobody confuses a plan with a result.

Systems, technology and the hidden integration bill
Operations runs on systems, and the systems are where the integration cost hides. An ERP nobody has upgraded in eight years, a WMS held together by custom scripts, a CRM that three business units use three different ways, each of these is an operational risk that reads as a technology line item. This is the seam between operations diligence and technology due diligence, and the two workstreams have to talk to each other or you will double-count nothing and miss everything.
The specific commercial questions are:
- Which systems are load-bearing for the value creation plan, and can they take the planned volume without a replacement project?
- What is the true cost and timeline of any system consolidation the thesis assumes, and who has ever actually done a migration on this stack?
- Where does the operation depend on undocumented, single-person knowledge of a system, which is key-person risk wearing a technology mask?
If the thesis assumes standardizing systems across a platform, treat that as its own program with its own budget, not a line in the synergy total. The considerations in CRM consolidation for portfolio companies and CRM standardization across portfolio companies show how quickly a clean-sounding “we will get everyone on one system” turns into a multi-quarter operating disruption if it is scoped as an afterthought.
People, key-person risk and the org that has to execute
The operating model is people before it is process. The plan you underwrote assumes a management team and a workforce that can execute change while running the business. Both parts of that assumption deserve testing.
Map the load-bearing individuals
Identify the people without whom a core operational process stops. The founder who still approves every large order. The one engineer who understands the pricing logic. The plant manager with 20 years of tribal knowledge. Each is a single point of failure and a retention question, and each belongs in the risk register with a mitigation, not a footnote.
Judge the change capacity, not just the headcount
A team fully occupied running the business today does not have spare capacity to execute an integration and a value creation plan simultaneously. Harvard Business Review’s body of work on mergers and acquisitions, collected at HBR’s M&A topic hub, returns repeatedly to the theme that integration fails on execution bandwidth, not strategy. If your plan needs the same 12 people to both run and transform, you have a sequencing problem that operations diligence should surface now.
Supply chain, vendors and contractual dependencies
Concentration risk is not only a customer-side issue. On the supply side, a single sole-source vendor, an expiring master agreement, an input with volatile pricing, or a logistics partner with better switching costs than you assumed can all undo an operating plan. S&P Global Market Intelligence tracks supply and credit conditions across sectors, and their coverage at S&P Global is a useful external check on how fragile a given supply base is at the moment you are underwriting it.
The work here is contractual and quantitative:
- Concentration on the buy side: what share of critical inputs comes from one or two vendors, and what is the switching cost and lead time if one fails.
- Contract runway: which key agreements expire inside the hold period, and what leverage does the counterparty gain at renewal.
- Change-of-control clauses: which supply, license or logistics contracts can be repriced or terminated on the transaction itself, a Day 1 issue that belongs in the integration dependency list.
How to tell real operations diligence from an activity report
You are the buyer of this work, so you need to judge it on delivery, not on the size of the deck. The tells are consistent, and they are the same tells that separate any serious diligence firm from a report factory. The framing in how to judge a commercial due diligence firm before you commit the budget applies directly here.
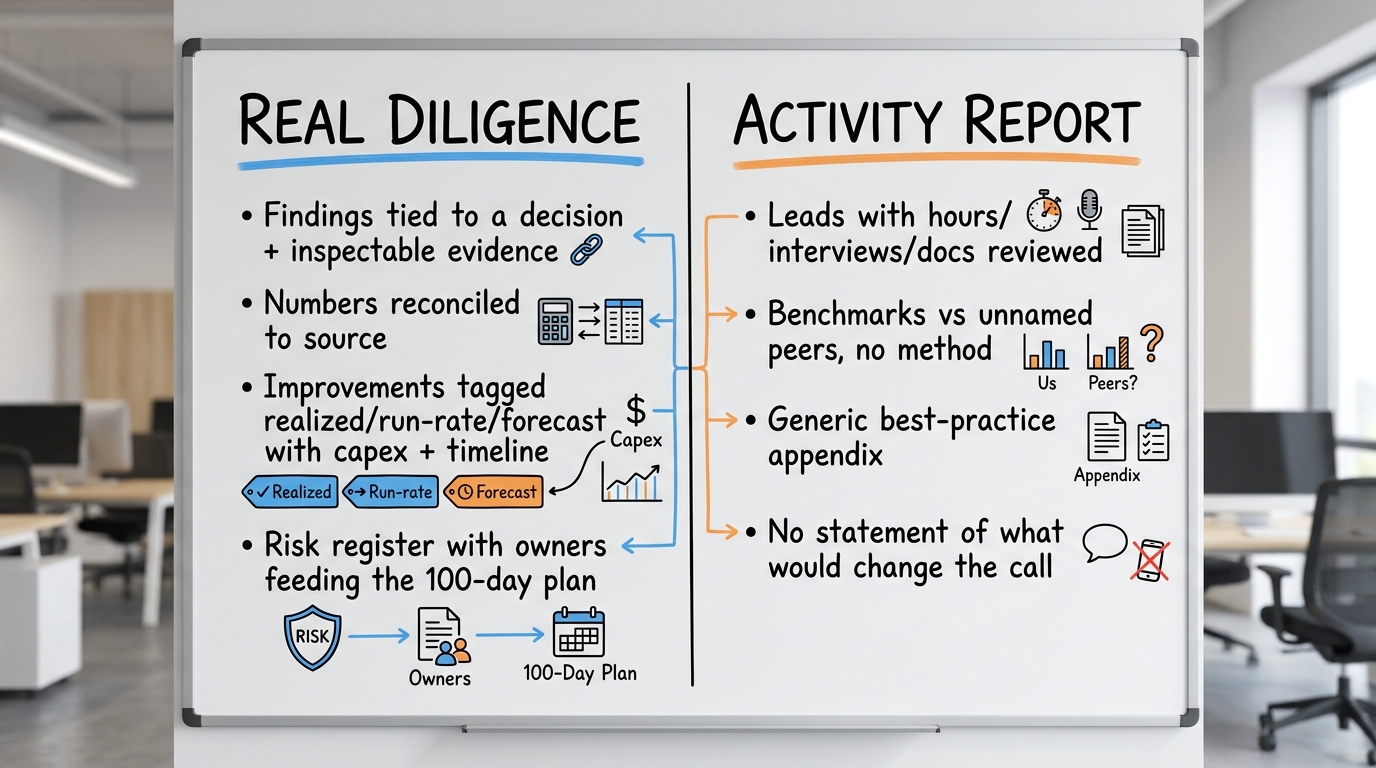
Signs you are getting a real product
- Every finding is tied to a decision and to evidence you can inspect, not to a maturity color.
- Numbers are sourced to systems and reconciled, and the team tells you which ones they could not verify.
- Improvements are classified as realized, run-rate or forecast, with capex and calendar attached.
- The risk register names owners and mitigations, and feeds directly into a first-hundred-days plan.
Signs you are getting an activity report
- The deliverable leads with hours spent, interviews conducted and documents reviewed.
- Benchmarks against unnamed peers with no method disclosed.
- A generic best-practices appendix that could apply to any company in the sector.
- No clear statement of what would have changed the recommendation.
Activity is not outcome. A firm that leads with how much work it did, rather than what it decided, is showing you its billing model, not its judgment.
Turning findings into the value creation plan and the first 100 days
Operations diligence is only worth the budget if its output survives close and drives action. The bridge is the value creation plan and the first 100 days. Every material finding should exit diligence in one of three buckets:
- Reprice or renegotiate: findings that change what the business is worth or what protection you need at close.
- Fund in the plan: improvements that require capital and calendar time, sized and sequenced so they do not all land in the same quarter.
- Fix in the first 100 days: the instrumentation, the reporting, the single points of failure that need attention before you can even measure progress.
Getting the operating baseline instrumented is almost always a first-hundred-days item, because you cannot manage a value creation plan against numbers you cannot reproduce. This is also where the commercial and go-to-market side reconnects. The revenue improvements in GTM value creation for portfolio companies only convert to EBITDA if operations can fulfill the demand they generate. A demand-generation win that the operation cannot service is a customer-satisfaction problem, not a growth story.
Connect it to how the deal is held
The structure of the hold changes how you weight operational risk. Longer holds, including the continuation-vehicle structures discussed in GP-led continuation vehicles and the longer-hold thesis, give a step-function investment more runway to pay back, which can flip a “reprice” finding into a “fund it” finding. The operational fact is the same. The decision it drives depends on the hold.
Where operations diligence connects to RevOps and commercial data
Operations is not only the factory and the warehouse. In services and software businesses, the operating model runs on revenue operations, the CRM, the pipeline data, the quote-to-cash process. The same diligence discipline applies. What in the pipeline is instrumented versus asserted, which processes depend on one person, and can the revenue engine scale at the plan’s volume.
If the target is CRM-heavy or subscription-based, the questions in what private equity should ask a RevOps consultant and the budgeting discipline in value proposition budgeting for SMEs belong inside the operations workstream, not bolted on afterward. BCG’s principal investors and private equity practice, whose work sits at BCG, and PitchBook’s deal and operating data at PitchBook are both useful for framing where operational leverage in a given sector realistically comes from.
The operations due diligence checklist
Use this as the scoping and judging checklist for an operations diligence effort in a private equity deal. If your provider cannot address these, you are buying activity, not an answer.
Scope and framing
- The operational thesis is written in one page and stated as something provable.
- Decision rights are named: who owns go/no-go, sizing, and model sign-off.
- The scope is time-boxed to the deal calendar with explicit exclusions.
Baseline and evidence
- Each key operating metric has a written definition and a reproducible source.
- Management-deck numbers are reconciled to source systems, with gaps flagged.
- Time series are long enough to expose seasonality and one-offs.
Capacity and cost
- The binding constraint is identified and tested at year two and year three volumes.
- Improvements are classified realized, run-rate or forecast, with capex and calendar.
- Variable scaling and step-function scaling are separated in the model.
Systems and people
- Load-bearing systems are identified and load-tested against the plan; system consolidation is scoped as its own program.
- Single points of failure among people and systems are in the risk register with mitigations.
- Change capacity is judged, not just headcount.
Supply and contracts
- Buy-side concentration, switching costs and lead times are quantified.
- Contract runway and change-of-control exposure are mapped to the hold period and Day 1.
Output
- Every finding lands in reprice, fund in the plan, or fix in the first 100 days.
- The risk register feeds directly into the value creation plan and the hundred-day plan.
- The provider states what evidence would have changed the recommendation.
What good looks like when you sign it off
When operations diligence is done well, you close with three things you did not have at LOI. A defensible operating baseline you can manage against. A value creation plan where the operational improvements are sized, dated, and classified honestly rather than lumped into an optimistic synergy number. And a risk register that becomes the spine of the first hundred days rather than a document nobody opens again. That is the difference between buying an operating story and buying an operating asset you can actually improve.
The governance literature on this is worth keeping current, and the Harvard Law School Forum on Corporate Governance regularly publishes on how boards oversee operational and integration risk post-close. Fund it early enough that the findings can change the deal, not just describe it.
If you want operations, commercial and go-to-market diligence run to this standard, tied to a value creation plan and a hundred-day sequence rather than a deck, see how DevriX and GrowthShuttle scope commercial and GTM due diligence for private equity and bring us the operational thesis you need to prove before close.