
The CDD report lands three weeks before you have to sign, and it is 90 pages long. Somewhere in there is the answer to the only question that matters: is the revenue thesis you underwrote in the LOI real, and will it survive contact with the operating plan you are about to own? Most operating partners and portfolio executives inherit this report late, read it once, and treat it as a checkbox for the investment committee. That is a mistake. Buy-side commercial due diligence is not paperwork you clear to get to close. It is the evidence base for your first 100 days, your board case, and the value-creation plan you will be held to at exit.
This guide is written for the buyer who already has budget and a signed LOI. The job here is to tell you what a good commercial diligence process actually decides, where the standard vendor report is thin, and how to judge whether the work in front of you is worth trusting with a nine-figure decision.
Commercial diligence exists to answer one question with evidence
Will this business hit the revenue and margin trajectory in the model, and what has to be true for that to happen? Everything else is supporting detail. The market sizing, the competitor teardown, the win-loss interviews, the customer concentration analysis, the pricing study, they all ladder up to a single output, which is a defensible view of forward revenue and the risks against it.
Bain’s annual review of the industry, published in its Global Private Equity Report, has consistently pointed at the same structural pressure: entry multiples are high, cheap leverage is gone, and returns increasingly have to come from operating improvement rather than multiple expansion. That changes what CDD is for. When you could underwrite a deal on financial engineering, the commercial diligence was a comfort read. When the return has to come from growing the business you buy, the commercial diligence is the underwriting.
So the practical test for any CDD deliverable is this: does it give you a growth thesis you can hand to an operator and execute, or does it give you a well-formatted description of a market you already knew existed? Those are very different products, and vendors sell both under the same name.
The three decisions CDD should inform
- Price and structure. Does the evidence support the number in the LOI, or does it argue for a retrade, an earnout, or walking away?
- The value-creation plan. Where does the growth actually come from, new logos, expansion, pricing, new segments, and is that credible?
- The risk register you inherit at close. Customer concentration, churn dynamics, a channel that is quietly deteriorating, a founder relationship that carries the pipeline.
If a report does not visibly serve all three, you are reading a market study, not a diligence product.
Separate the revenue thesis from the market story
Here is the most common failure I see buyers accept: a report that spends 40 pages establishing that a market is large and growing, and four pages on whether this specific company can win in it. Total addressable market is the easiest thing to research and the least decision-relevant. A big market does not pay your returns. This company’s share of demand, at a defensible price, with a repeatable motion, is what pays your returns.
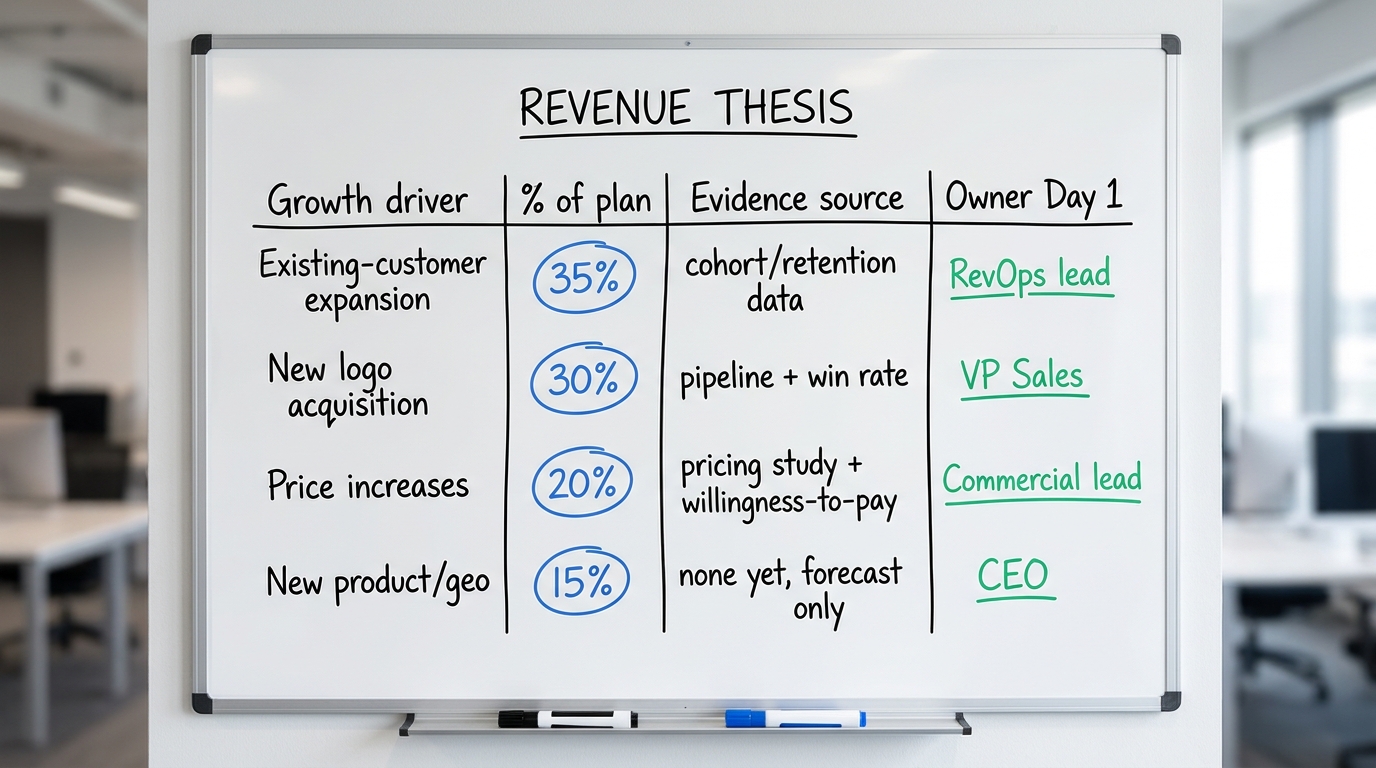
The revenue thesis has to be decomposed into its drivers. If the model says revenue grows 18% a year for five years, that number has to break down into something you can inspect: how much comes from existing customers spending more, how much from new customer acquisition, how much from price, how much from new products or geographies that do not exist yet. Each of those has a different risk profile and a different owner in the first 100 days.
McKinsey’s private capital research, available through McKinsey, has repeatedly made the point that value-creation plans built on generic “grow the market” logic underperform plans built on specific, owned commercial levers. When you read a CDD report, mark every growth claim and ask where its evidence lives. A claim with no evidence behind it is a hope you are being asked to pay for.
How to judge the quality of the evidence base
Every CDD conclusion rests on evidence, and the evidence is where the weakness hides. A report can be persuasive and still be built on nothing. Your job is to trace the claims back to their sources and grade them.
Primary versus secondary evidence
Primary evidence is data the diligence team gathered directly: customer interviews they conducted, win-loss calls, a churn analysis run on the target’s actual transaction data, a pricing survey they fielded. Secondary evidence is analyst reports, market databases, and desk research. Both have a place. A report that is 90% secondary is a literature review dressed as diligence. The expensive, hard-to-fake work is the primary work, and that is what you are paying a premium for.
Sample sizes and who was actually interviewed
When a report says “customers value the product’s reliability,” ask how many customers said that, which ones, and whether the sample skewed toward happy references the seller pre-selected. Customer interviews arranged entirely by the seller are worth less than the report implies. Independent outreach to lost deals and churned accounts tells you more than any managed reference call. If the win-loss work only talked to wins, it is not win-loss work.
The base rate and the counterfactual
Good diligence tells you not just what the company does but how that compares to what a typical company in the segment does. A 92% gross retention rate sounds strong until you learn the segment norm is 95%. Data providers like PitchBook and S&P Global Market Intelligence exist partly so you can benchmark a target against real comparables rather than the seller’s framing. If your CDD provider is not benchmarking, they are describing the company in a vacuum.
Customer concentration and the durability of demand
Concentration is where a clean-looking business hides its real risk. If the top five customers are 60% of revenue and two of them are up for renewal in the first year of your hold, the revenue thesis is a hostage situation, not a growth plan. Commercial diligence has to surface this and quantify it, not bury it in an appendix.
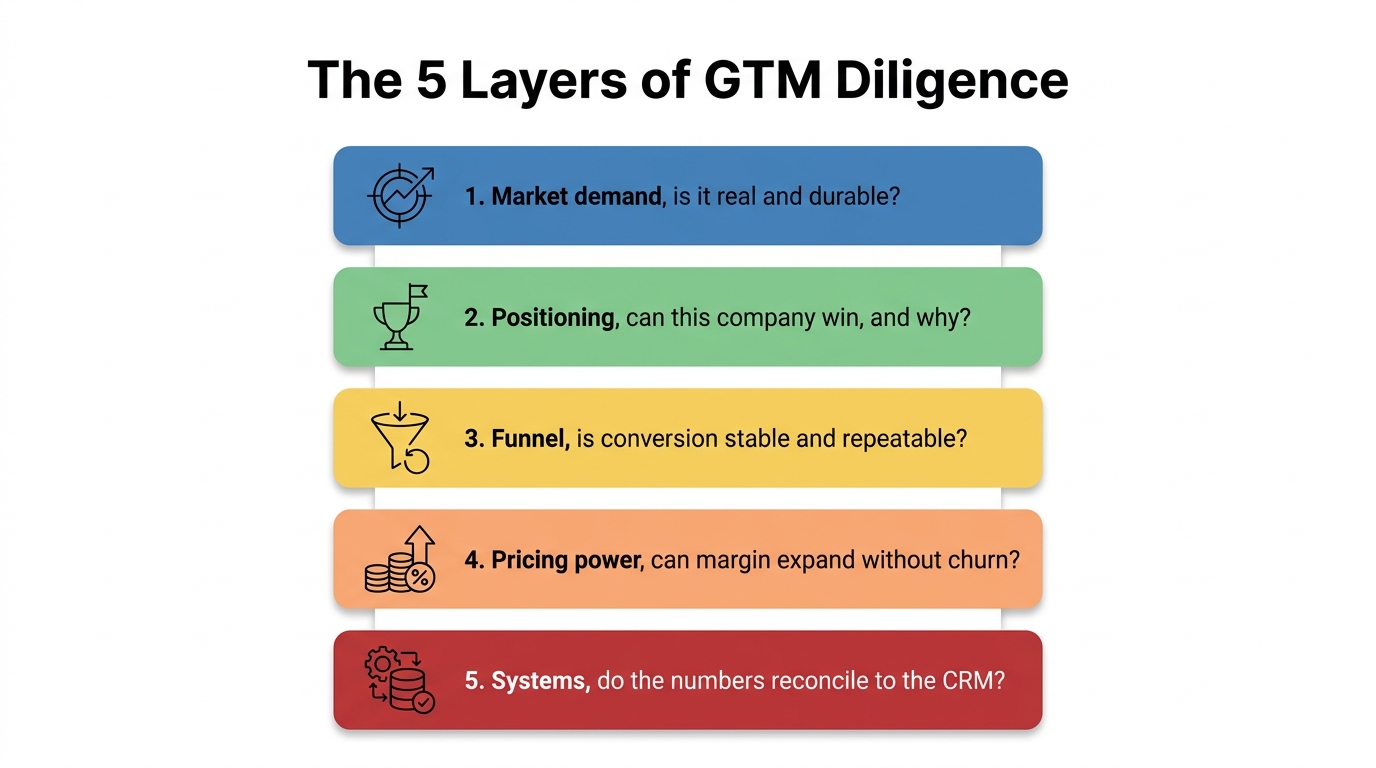
What you want to see is a cohort view of revenue: how customers acquired in each year have behaved over time, whether net revenue retention is holding up or quietly eroding, and whether the business is dependent on a small number of relationships that may be personal to the founder or a single account executive. This is exactly the kind of question that connects commercial diligence to operational reality, and it is why the CRM and revenue systems matter so much in the same review. If the data to answer these questions does not exist in a clean form, that itself is a finding. It usually means the target does not run on evidence, and you will spend part of your first year building the visibility you assumed you were buying.
When concentration risk is real, it should change the deal, not just the report. It might argue for an earnout tied to renewals, a lower price, or a specific retention workstream owned from Day 1. A CDD process that finds concentration but does not translate it into a commercial decision has done half the job.
Pricing power and the margin story most reports skip
Revenue growth without pricing power is a treadmill. You can grow the top line by discounting your way into worse customers, and the model will look fine until the margin collapses. Strong commercial diligence tests whether the business can raise prices without losing volume, because pricing is the single fastest lever for EBITDA expansion in the first year of ownership.
The evidence for pricing power comes from a few places: historical price increases and what happened to churn afterward, willingness-to-pay research with actual customers, and an honest read of how differentiated the product really is versus the alternatives. A business with genuine switching costs and a product customers cannot easily replace has room to price. A business winning on price has none, and no amount of sales-team energy fixes that.
Harvard Business Review’s coverage of mergers and acquisitions has made the point repeatedly that pricing discipline is one of the most reliable, least glamorous sources of post-deal value. If your commercial diligence has nothing to say about pricing, it is missing the lever most likely to pay for the deal.
The go-to-market engine and whether it is repeatable
A growth thesis is only as good as the machine that produces the growth. Buy-side commercial due diligence has to open up the go-to-market engine and ask whether the revenue comes from a repeatable system or from heroics that do not scale. This is where commercial diligence and operational diligence overlap, and where a lot of value is won or lost.
Pipeline, conversion, and the shape of the funnel
You want to see the funnel with real numbers: how many opportunities enter, what converts at each stage, how long the cycle runs, and whether those metrics are stable or deteriorating. A pipeline that only converts when the founder gets on the call is not a scalable engine, it is a person. A funnel that has been quietly getting less efficient for six quarters is a warning the growth story is running out of road.
The revenue systems underneath
The CRM and revenue tooling are not an IT footnote. They are where you find out whether the reported numbers are trustworthy and whether the business can be scaled without rebuilding the plumbing. If you are going to standardize systems across a platform, the diligence is where you learn what you are walking into. Our guides on CRM standardization across portfolio companies and CRM consolidation for portfolio companies walk through what to decide once you own the asset, and much of that decision starts with what the commercial diligence uncovers.
This is also where commercial and technology due diligence have to talk to each other. A go-to-market plan that assumes a self-serve motion the platform cannot support is not a plan, it is a wish. If the two workstreams run in separate rooms and never reconcile, you inherit the gap.
Reconcile the commercial view with the numbers
A commercial story that does not reconcile to the financials is fiction. If the CDD says the sales team is winning new logos at an accelerating pace, that has to show up in the quality-of-earnings work as new-customer revenue. If the commercial team and the financial diligence team never compared notes, you have two reports that agree with the seller and disagree with each other.
This reconciliation is one of the highest-value things you can insist on. The commercial view of retention should match the financial view of recurring revenue. The pricing story should match the observed average selling price over time. Guidance from AICPA & CIMA on quality-of-earnings work makes clear how carefully financial diligence separates one-time from recurring revenue. Your commercial diligence has to line up with that separation, not fight it.
When the two do not agree, do not paper over it. The disagreement is usually the most important thing either report will tell you. It means someone’s model has a hole, and it is cheaper to find that hole before close than after.
Match the diligence depth to the deal type
The commercial diligence you need depends on what kind of return you are underwriting and what kind of business you are buying. A growth-equity minority stake in a fast-scaling company demands a different lens than a buyout of a mature cash-generative business, because the source of return is different. Our comparison of growth equity versus buyout lays out why the return engine changes what you have to prove.
A carve-out is its own beast. When you buy an orphaned division out of a larger parent, the commercial diligence has to untangle which revenue and which customer relationships actually travel with the asset and which were subsidized or shared by the parent. The commercial standalone case is often the hardest part of the deal. Our guide to corporate carve-outs covers where standalone value hides and where phantom revenue does.
And the length of your hold changes the weight you put on the growth thesis. As we argued in our piece on how longer hold periods move the value-creation burden to the operator, when you plan to hold for seven or eight years, the commercial diligence is less about defending the entry number and more about verifying that the growth engine can run for the full hold. Bain and BCG both track this shift toward operator-led value creation; BCG’s work on principal investors and private equity is a useful place to see how the underwriting logic has moved.
Where standard CDD reports fall short for the operator
The standard commercial diligence report is written for the investment committee, not for the person who has to execute the plan. That is the structural gap. The IC wants a go or no-go with a risk-adjusted view. The operating partner wants a plan they can run on Monday of week one. Most reports deliver the first and gesture vaguely at the second.
Here is what an operator needs that a standard report often omits:
- The 100-day commercial priorities, ranked. Not a list of everything, but the three things that matter most in the first quarter and who owns them.
- The specific data gaps the target cannot answer today, because those become your first reporting-build projects.
- The revenue at risk with a name attached, which accounts, which renewals, which relationships, so retention becomes a workstream, not a worry.
- A baseline you can measure against. If the diligence does not establish where the numbers stand at close, you will spend your first board meeting arguing about what “improvement” even means.
This is precisely the bridge between diligence and the first 100 days. A commercial diligence process that ends at close and hands nothing forward has wasted most of its value. The findings should flow directly into the value-creation plan, the reporting cadence, and the specific commercial workstreams you launch on Day 1.
If you are bringing in an outside RevOps or commercial advisor to help translate the diligence into execution, our guide on what private equity should ask a RevOps consultant covers how to tell a real operator from someone who will hand you another deck.
Judge the provider, not just the report
You are hiring a team, and the quality of the team determines the quality of the evidence. A few tests separate serious providers from box-checkers.
Do they run primary work themselves?
Providers who conduct their own customer and win-loss interviews, run their own pricing research, and analyze the target’s actual data are building evidence. Providers who repackage analyst reports are selling you a summary you could buy from Preqin or an industry publication for a fraction of the fee. Ask directly: how much of this report is primary work your team did, and who did it?
Will they stake a position?
A report full of hedges is a report that is protecting the provider, not informing you. The best commercial diligence takes a clear view, this thesis holds, or it does not, and here is what would change the answer. If every conclusion is qualified into meaninglessness, the provider is optimizing for never being wrong rather than being useful.
Do they understand what you inherit?
The providers worth paying understand that their report becomes your operating plan. They think about handoff, about baselines, about the workstreams the findings imply. Providers who treat the report as the end of their engagement produce documents that die at close. Coverage in Private Equity International and Buyouts regularly notes the same industry shift: the value-creation edge now sits with firms that connect diligence to execution rather than treating them as separate purchases.
Read the diligence in light of how the deal makes money
Your commercial diligence should be read against the entry price and the return math, not in isolation. A growth thesis that looks fine on its own may be entirely inadequate once you account for what you paid. When the entry multiple is high, more of the return has to come from growth, and the commercial diligence has to clear a higher bar. Our explainer on private equity valuation multiples walks through how entry pricing shifts where the returns have to come from.
The same discipline applies to how you will report performance later. If your commercial thesis assumes a certain revenue ramp, that ramp will show up in your fund’s marks and eventually in your realized returns. Reading those numbers honestly matters, which is why we wrote about reading IRR, MOIC and DPI without being fooled. The commercial diligence is the first place the story that produces those numbers gets written, and it is where optimism is cheapest to insert and most expensive to unwind.
For longer-hold structures, the connection is even tighter. If you are underwriting through a GP-led continuation vehicle, the commercial diligence has to support a growth story that runs well past a normal hold, which raises the bar on how durable the demand and the pricing power really need to be.
Do not treat every risk finding as equal
Commercial diligence surfaces risks, and part of judging the work is judging whether it distinguishes value-relevant risk from noise. A finding that a customer might churn and take 8% of revenue with them is a material commercial risk. A finding that the company has an incomplete data-privacy policy might be a compliance item that matters or might be theater, depending on the business. Confusing the two wastes management attention on the wrong things.
We made this argument in the context of ESG, where the discipline is to separate value-relevant risk from compliance theater, and the same logic applies across the whole commercial risk register. Ask of every risk in the report: does this change the revenue thesis, the price, or the plan? If it does not touch any of the three, it belongs in an appendix, not on your board agenda. And where a risk genuinely is regulatory in nature, the primary sources like the SEC and governance analysis from the Harvard Law School Forum on Corporate Governance are where the real requirements live, not the summary paragraph in the CDD.
The buyer’s checklist for judging commercial diligence
Before you accept a commercial diligence report as the basis for a decision worth this much, run it against a short list. If it fails on several of these, send it back or find a better provider before you sign.
- Does it decompose the revenue thesis into named growth drivers, each with its own evidence and its own owner for Day 1?
- Is the majority of the evidence primary work the team did, not repackaged analyst reports?
- Were lost deals and churned customers interviewed, not only happy references the seller chose?
- Is customer concentration quantified and translated into a deal or plan implication, not buried?
- Does it take a clear position on pricing power, with evidence, rather than skipping margin entirely?
- Does the funnel show real, stable numbers, or does growth depend on one or two people?
- Does the commercial view reconcile with the quality-of-earnings view of recurring revenue?
- Is the depth matched to the deal type, carve-out, growth equity, buyout, continuation vehicle?
- Does it hand forward a ranked 100-day plan, named data gaps, and a measurable baseline?
- Does it separate value-relevant risk from compliance noise, so board attention goes to what moves returns?
A report that clears this list is worth the fee, because it does more than tell you whether to buy. It tells you how to run the asset once you own it. That is the difference between commercial diligence as a checkbox and commercial diligence as the first chapter of your value-creation plan.
Where this leaves the buyer
The commercial diligence you accept before close becomes the operating truth you inherit after it. If the report is a market study, you will spend your first year discovering the business you actually bought. If it is a real evidence base, decomposed revenue thesis, primary customer work, honest pricing view, reconciled to the numbers, and handed forward as a plan, you start Day 1 knowing where the value is and who owns it. The gap between those two outcomes is not the size of the fee you paid. It is how seriously the provider treated the work, and how seriously you held them to it.