
You are three weeks from a confirmatory diligence deadline, and the commercial deck the sell-side gave you tells a clean story: strong logo retention, a growing pipeline, a repeatable sales motion. Your investment committee wants to know whether the top-line case in the model actually holds, or whether the growth is one lucky enterprise deal, a channel that is about to saturate, and a sales team that has never sold without the founder in the room. That is the question GTM due diligence answers, and it is the one most likely to blow up the thesis after close if you get it wrong.
This guide is for the operating partner, deal lead, or portfolio CEO who has budget to commission commercial diligence and needs to know what a good scope looks like, what the findings should let you decide, and how to tell a rigorous vendor from one selling a pretty slide. It assumes you already know the mechanics of a deal. It does not re-explain what a cohort or a pipeline is. It focuses on the commercial engine, because in most mid-market deals the revenue plan is where value is created or quietly lost.
1. Why GTM due diligence is the part of the model most likely to be wrong
Financial diligence tells you what happened. Quality of earnings normalizes the past. GTM due diligence in private equity is the only workstream that tests whether the forward revenue plan is real, because the go-to-market engine is what has to produce the growth the entry multiple already paid for. If you underwrote a business at a full price, the returns have to come from operational improvement rather than multiple expansion, and a large share of that improvement is commercial. That relationship between entry pricing and where returns must come from is worth sitting with before you scope anything, and it is covered well in this breakdown of how private equity valuation multiples shift where returns have to come from.
The commercial case is also the part of the model built on the thinnest evidence. Bain’s annual private equity report has documented for years how much of the industry’s return now depends on revenue and margin growth rather than leverage and multiple arbitrage, which puts more weight on the durability of the GTM motion than a leverage-driven deal ever did. You can read the pattern in Bain & Company’s Global Private Equity Report. The uncomfortable implication: the number in the model with the least underlying data is now the number carrying the most of the return.
So the job of GTM diligence is not to confirm the seller’s story. It is to find the two or three assumptions in the growth plan that, if wrong, break the underwrite, and to price them before you sign.
2. Name the decisions the diligence has to inform
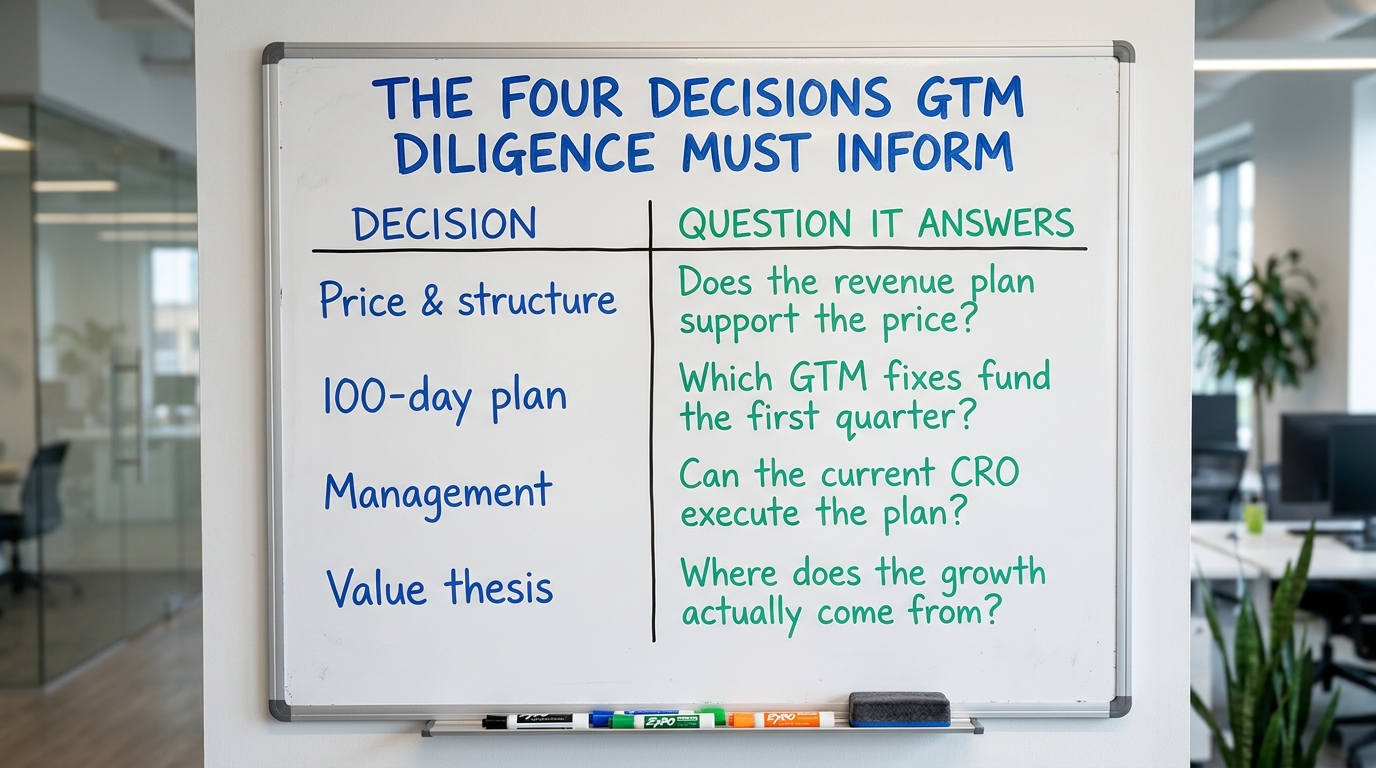
Weak commercial diligence produces a description of the business. Strong commercial diligence produces inputs to specific decisions. Before you brief a vendor, write down the decisions the work must serve, because that scope discipline is what separates a useful report from an expensive one.
- Price and structure. Does the revenue plan support the price, or do you need a lower entry, an earn-out, or a walk?
- The 100-day commercial plan. Which GTM fixes are urgent enough to fund in the first quarter of ownership, and which can wait?
- Management assessment. Can the current commercial leadership execute the plan, or is there a CRO-shaped hole in the org?
- The value creation thesis. Is the growth going to come from new logos, expansion inside the base, pricing, new segments, or add-ons, and does the current engine support that path?
If a finding does not move one of those four decisions, it is background color. The reader with budget should push the vendor to map every workstream to a decision on this list.
3. Start with revenue quality, not the pipeline
Sellers lead with pipeline because it is the most flattering number and the easiest to inflate. Sober diligence starts one layer down, with the quality and durability of revenue that already exists. Three things matter more than pipeline size.
Retention and its composition
Gross revenue retention and net revenue retention tell different stories, and sellers show whichever one is prettier. Gross retention exposes the leak. Net retention can hide a churning base under a few large expansions. Ask for both, by cohort, and look at whether net retention is carried by three accounts or spread across the base. Concentration in expansion is as dangerous as concentration in bookings.
Customer concentration and the logo behind the growth
If the last two years of growth trace to one or two enterprise wins, the “repeatable motion” narrative is fiction until proven otherwise. Rebuild the growth bridge yourself and identify which logos and segments actually drove it. A motion that produced ten similar mid-market wins is worth more than one that produced a single whale, even if the whale is larger.
The economics under the growth
Customer acquisition cost, payback period, and lifetime-value-to-CAC ratios tell you whether growth is profitable or bought. For guidance on how these unit-economic measures are constructed and where they mislead, the AICPA & CIMA resources on management reporting are a reasonable anchor. If CAC payback has been quietly lengthening while the seller celebrates bookings growth, the engine is getting more expensive to run, and the model probably assumes it gets cheaper.
4. Test whether the sales motion survives without the founder
In lower-mid-market companies, the single largest hidden GTM risk is founder dependency. The founder closes the big deals, holds the key relationships, sets pricing on instinct, and is the reason enterprise buyers signed. None of that shows up in a pipeline report, and all of it walks out the door somewhere between close and year two.
Judge this directly. Ask what share of closed revenue in the last eight quarters involved the founder personally. Look at whether there is a documented sales process, a functioning pipeline stage definition, and reps hitting quota without heroics. Interview two or three reps and listen for whether they can articulate the value proposition without reciting the founder’s lines. A motion that only works with the founder in the room is not a scalable GTM engine. It is a personal brand, and you are about to lever it.
This is also where management assessment and commercial diligence merge. If the plan requires a professional sales organization the company has never had, that is a hire, a ramp, and a risk you price now rather than discover in the first board meeting. Longer hold periods make this even more consequential, because the burden of building that engine shifts squarely onto the operator, a shift laid out in this piece on how longer hold periods move the value creation burden from the deal team to the operator.
5. Separate market truth from the seller’s TAM slide
Every commercial deck has a total addressable market number, and most of them are theater. The useful question is not “how big is the market” but “how much of the near-term plan depends on the market growing versus the company taking share.” Those are different risks with different mitigations.
Ground the market view in independent data rather than the seller’s analyst deck. PitchBook and S&P Global Market Intelligence both publish sector and deal data you can use to sanity-check growth rates and competitive density. If the plan assumes the company keeps winning at its current rate in a market that is consolidating or slowing, that assumption needs to be surfaced, not smoothed over.
Three market questions carry most of the weight:
- Is the served segment growing, flat, or contracting, independent of the company’s own trajectory?
- Where does the company actually win against competitors, and is that advantage durable or a temporary pricing gap?
- What is the realistic ceiling on the current motion before it needs a new segment or product to keep growing?
The answers tell you whether the value creation thesis should lean on share gains, expansion, new segments, or add-ons, which connects directly to the return engine you are choosing. The distinction between a share-gain buyout and a market-expansion growth story is drawn well in this comparison of growth equity versus buyout and choosing the return engine that fits the business.
6. Audit the revenue infrastructure, because bad data hides bad news
Here is a failure mode that costs deals: the commercial diligence looks clean because the underlying data was never good enough to reveal the problem. If the CRM is a graveyard of half-filled fields, if pipeline stages mean different things to different reps, and if forecast accuracy has never been measured, then every number in the commercial deck is an estimate dressed as a fact.
Treat the state of the revenue operations stack as a diligence finding in its own right, not an IT footnote. Poor CRM hygiene is both a data-reliability problem now and an integration cost later. If you are building a platform through add-ons, the cost and disruption of standardizing systems across the portfolio is real, and it is worth reading before you assume synergy. Two practical treatments of that work sit here: CRM standardization across portfolio companies and CRM consolidation for portfolio companies.
The commercial view also has to reconcile with the technical one. Where GTM diligence assesses whether the revenue motion works, technology due diligence assesses whether the systems and product underneath can support the plan without an expensive rebuild. When those two workstreams disagree, that disagreement is usually the most important finding in the whole process, and it should be surfaced to the deal team rather than resolved quietly by two vendors who never spoke.
7. Judge the vendor before you judge the target
You are buying commercial diligence to reduce the risk of a bad decision. A vendor who confirms the seller’s story and hands you a deck of pipeline charts has increased your risk while making you feel better, which is the worst possible outcome. Before you sign a scope, pressure-test the provider.
Do they rebuild the numbers or repackage them?
A serious provider pulls raw data from the CRM and billing system and rebuilds retention, concentration, and the growth bridge from source. A weak one restates the seller’s summary in nicer fonts. Ask directly what raw data they require and what they do if the seller cannot provide it.
Do their findings map to decisions?
Ask to see a redacted prior deliverable. If the findings read as observations rather than as inputs to price, plan, and management decisions, the report will not help your investment committee. The right questions to put to a commercial or revenue-operations provider are laid out in this buyer’s guide to what private equity should ask a RevOps consultant.
Can they turn diagnosis into execution?
The best commercial diligence flows straight into the 100-day plan, because the people who found the problem are best placed to help fix it. That continuity is a real advantage of a firm that does both diagnosis and operating work, such as a private equity commercial and GTM diligence engagement that hands off directly into execution.

8. Turn findings into a priced risk register
A finding that is not priced is not actionable. The output of GTM diligence should be a short list of the commercial risks that matter, each with an owner, a rough cost or revenue impact, and a classification of how confident you are it is real. Resist the urge to catalog everything. Three well-priced risks beat thirty observations.
For each material commercial risk, force a classification:
- Priced into the deal. The risk is real, quantified, and reflected in your bid or structure.
- Fixable in the first 100 days. The problem is addressable with a known intervention and cost, and it belongs in the day-one plan.
- Structural. The problem changes the thesis itself, and the right response may be a lower price or a walk.
The Harvard Business Review’s work on mergers and acquisitions and the Harvard Law School Forum on Corporate Governance both document how often deals underperform because commercial integration risk was identified but never priced or assigned. The discipline is not finding risks. It is deciding what each one costs and who owns it.
9. Read the growth plan the way the return math will
The commercial plan does not exist in isolation. It has to produce returns that clear the fund’s hurdle, and the way you read GTM findings should be conditioned on what the return actually depends on. In a growth-oriented deal, revenue durability and expansion capacity carry the case. In a value-oriented buyout, margin and cash conversion may matter more than top-line acceleration.
Understanding how those returns are measured keeps you honest about which GTM findings are load-bearing. The mechanics of reading IRR, MOIC, and DPI without being misled are covered in this guide to private equity fund performance benchmarks, and the broader research from McKinsey’s private capital work and BCG’s principal investors and private equity practice is useful for framing where returns in the current environment are coming from. The point for the diligence reader: a commercial finding is only as important as its effect on the return path, and the return path depends on the deal’s structure.
10. Handle the special cases: carve-outs, continuation vehicles, and platforms
Standard GTM diligence assumes a clean, standalone business with its own commercial engine. Several common situations break that assumption and require a different lens.
Carve-outs
When you buy a division out of a parent, the GTM engine may not exist as a standalone unit at all. Shared sales teams, shared CRM, and shared brand equity all have to be untangled and stood up independently, and the commercial ramp during separation is a real revenue risk. The specific value and risk pattern in these deals is worth studying in this piece on corporate carve-outs and where orphaned divisions become standalone value.
Continuation vehicles and longer holds
When an asset is held longer, through a continuation vehicle or a longer-hold thesis, the commercial diligence has to look further out, because the plan is no longer a three-year sprint to exit. The durability of the motion over a longer horizon matters more than short-term pipeline. The underwriting logic of these structures is explained in this analysis of GP-led continuation vehicles and how the longer-hold thesis actually underwrites.
Platform and add-on plans
If the thesis is roll-up, GTM diligence has to assess not just the target’s motion but whether it can absorb and standardize acquired revenue engines. Cross-sell assumptions in platform models are notoriously optimistic, and they should be discounted heavily until proven.
11. Don’t skip the value-relevant risks that hide outside the GTM slide
Some commercial risks live outside the pipeline entirely. Customer-facing ESG exposure, data-privacy practices in the marketing and sales stack, and regulatory constraints on how the company sells can all affect the revenue plan and the eventual exit. The trick is separating value-relevant risk from compliance theater, a distinction drawn carefully in this treatment of ESG in private equity diligence and separating value-relevant risk from compliance theater.
On the data and disclosure side, the U.S. Securities and Exchange Commission materials are a reasonable reference point for the kinds of representations and practices that can become liabilities. The commercial reader’s job is narrow here: flag only the risks that could actually impair revenue or complicate exit, and leave the rest to the compliance workstream.
12. A working checklist for the diligence reader
Use this as the outline for what a strong GTM due diligence engagement should deliver, and as a scorecard for judging whether the one you commissioned did its job.
- Revenue quality: gross and net retention by cohort, customer concentration, and a rebuilt growth bridge showing which logos and segments drove the last two years.
- Unit economics: CAC, payback, and LTV-to-CAC trend lines, with the direction of travel called out, not just the current value.
- Motion durability: founder dependency, documented process, quota attainment without heroics, and whether reps can sell the value proposition independently.
- Market truth: independent segment growth, competitive positioning, and the realistic ceiling on the current motion.
- Revenue infrastructure: CRM hygiene, forecast accuracy history, and the reliability of every number in the commercial deck.
- Reconciliation: explicit agreement or documented disagreement with the technology diligence findings.
- Priced risk register: three to five commercial risks, each classified as priced-in, 100-day fixable, or structural, with an owner and a rough impact.
- Handoff: the material findings mapped directly into the day-one commercial plan, ready for the operating partner to run.
If the deliverable covers those eight lines with evidence rather than assertion, you can make the price, plan, and management decisions with your eyes open. If it does not, you paid for a nicer version of the seller’s story.
13. From diligence to the first 100 days
The value of GTM due diligence is realized only if the findings survive the transition into ownership. Too many commercial diligence reports are read once, quoted in the investment committee memo, and never opened again. The findings that matter should become the backbone of the early operating plan, with the priced risks turning into funded workstreams and the founder-dependency finding turning into a hiring and knowledge-transfer plan.
That continuity from diagnosis to execution is where commercial diligence actually pays back, and it is the reason to think about the first 100 days plan while you are still in diligence rather than after close. The commercial risks you found are the plan. Treating them as a separate exercise loses the thread and the momentum.
Research from Preqin and industry coverage in Private Equity International and Buyouts consistently points to the same thing: operational value creation, executed early, separates the funds that clear their targets from the ones that rely on the market. GTM diligence is the front end of that operational work, not a checkbox before it.
The short version
GTM due diligence in private equity exists to test the one part of the model built on the thinnest evidence and carrying the most of the return. Scope it to four decisions: price, the 100-day plan, management, and the value thesis. Start with revenue quality rather than pipeline. Test whether the motion survives without the founder. Ground the market view in independent data. Treat the revenue infrastructure as a finding, not a footnote. Judge the vendor as hard as you judge the target, and demand a priced risk register that flows straight into the first 100 days. Do that, and the commercial case in your model becomes something you can defend rather than something you hope is true.
If you are approaching confirmatory diligence or building the commercial plan for an asset you are about to own, and you want the revenue engine rebuilt from source data rather than repackaged from the seller’s deck, see how DevriX runs commercial and GTM due diligence for private equity, from diagnosis through the first 100 days of execution.