

You are three weeks from signing an LOI, the quality-of-earnings report is landing next week, and someone on the deal team just asked who is going to tell you whether this business can actually run at the scale your model assumes. That is the operational question, and it is different from the financial one. A QoE tells you the earnings are real. It does not tell you whether the ERP will fall over at 2x volume, whether the sales team hits plan because of the product or because of one rainmaker who is about to retire, or whether the integration you priced into the model is a six-month job or an eighteen-month one.
Choosing an operational due diligence provider in private equity is a purchasing decision, not a research project. You have budget. You have a timeline. What you need is a way to judge which provider will give you evidence you can underwrite against, and which will hand you a well-formatted deck that repeats management’s story back to you. This guide is written for the operating partner, deal lead, or portfolio-company executive making that call, and it assumes you already know what an ODD is. The question is how to buy one that changes a decision.
1. What you are actually paying an ODD provider to do
The commercial consequence of a weak operational diligence is simple: you pay for a business that cannot deliver the plan, and you find out in month nine when the forecast misses and the board asks why nobody flagged it. Good operational due diligence exists to move a number in your model, either the entry price, the value-creation plan, or the risk register that governs the first year of ownership.
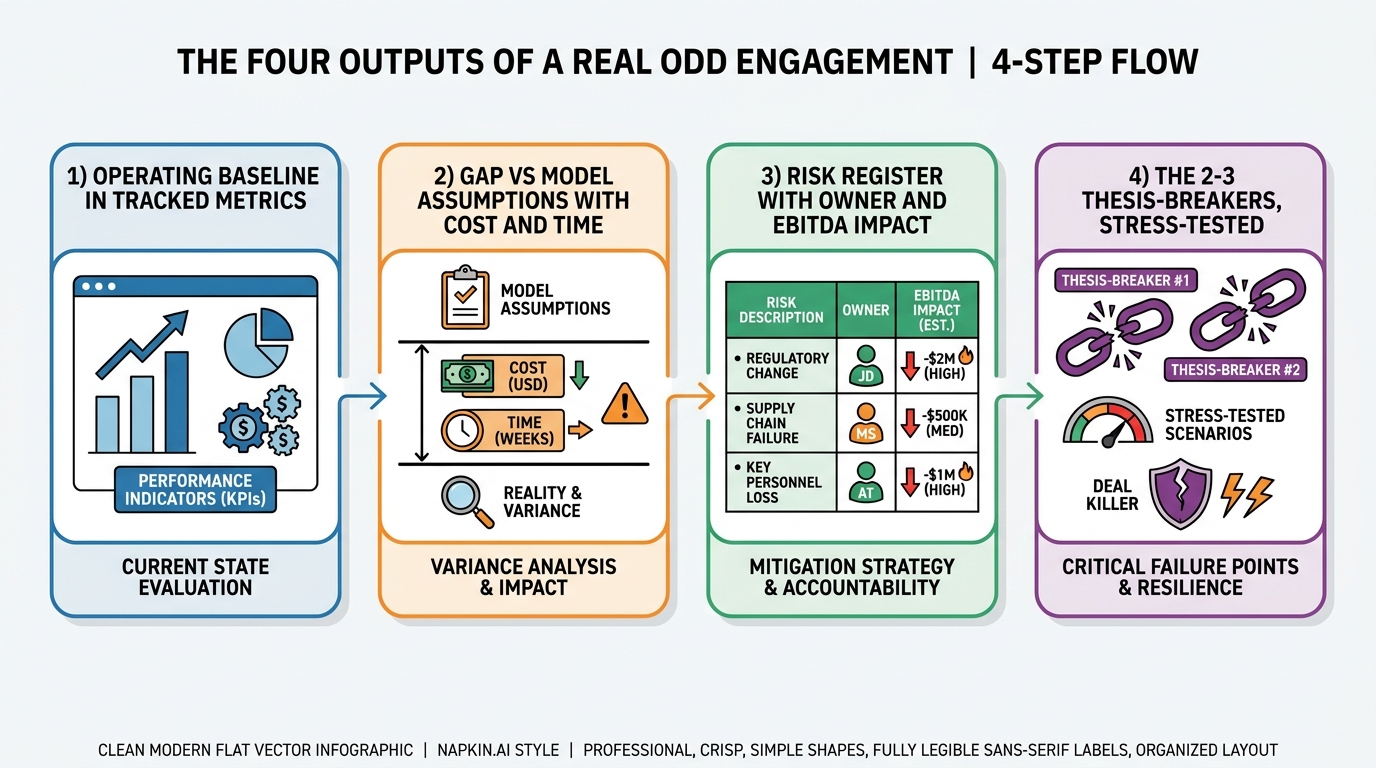
So before you compare providers, get specific about the output you are buying. A useful ODD engagement produces at least these four things:
- A baseline of how the business runs today, expressed in metrics you can track after close, not adjectives.
- A gap between that baseline and the operating assumptions in your model, with the cost and time to close each gap.
- A risk register that names each operational risk, its owner, its likely EBITDA or cash impact, and whether it is a pre-close price issue or a post-close execution issue.
- A short list of the two or three things that would break the thesis, tested hard rather than mentioned in passing.
If a provider’s scope does not obviously produce those four, you are buying a description, not a diagnosis. Bain’s Global Private Equity Report has tracked for years how value creation has shifted away from multiple expansion and financial engineering toward operational improvement, which is exactly why the diligence that reads the operations well is now worth paying for.
2. Separate operational diligence from the reports next to it
Deal teams routinely commission four or five diligence workstreams that overlap at the edges, and providers are happy to let the boundaries blur because it expands scope. You should draw the lines yourself so you know what you are and are not getting.
What operational diligence is not
It is not the QoE, which addresses the quality and sustainability of earnings. It is not commercial diligence, which tests the market, the demand, and the go-to-market engine. It is not technology diligence, which examines the code, the architecture, and the security posture. Each of those is a distinct discipline, and buying one on the assumption it covers another is how gaps survive to Day 1.
Two of these are so frequently confused with ODD that they deserve a direct pointer. If your thesis leans on revenue growth, the workstream you actually want may be commercial rather than operational, and it is worth reading our guide on how to judge a commercial due diligence firm before you commit the budget. If the business is software-heavy, a proper technology due diligence engagement will surface architecture and scalability risks that a general operations review will wave past.
Where the overlaps are useful
The overlap between operational and data diligence is the one worth engineering deliberately. Many operating problems are really data problems wearing operating clothes: a forecast that misses because the pipeline data is fiction, a margin that looks stable because two entities book revenue differently. Our breakdown of the five data problems that survive a QoE is the companion read here, because those problems land on the operating partner’s desk after everyone else has signed off.
3. Match the provider to your thesis, not to their brand
The biggest waste of a diligence budget is hiring a generalist firm with a strong logo to answer a specific operational question they have no particular edge on. Before you shortlist anyone, write down in one sentence what your thesis actually depends on operationally. The right provider follows from that sentence.
- If the thesis is a roll-up or buy-and-build, you need a provider fluent in integration, shared services, and system consolidation, because the value is in combining entities, not running one better.
- If the thesis is margin expansion in a single asset, you need someone who can baseline cost-to-serve, throughput, and process yield with real rigor.
- If the thesis is growth, the operational question is capacity: can the operating model support the revenue the plan promises without breaking?
- If it is a carve-out, the operational risk is standalone readiness, which is its own discipline. Our piece on where orphaned divisions become standalone value covers why carve-out diligence should not be handed to a general ODD team.
McKinsey’s private capital research and BCG’s work on principal investors and private equity both make the same underlying point in different language: operational value creation is where returns are increasingly won, and the diligence that predicts it has to be specific to the operating model in front of you. A provider who pitches the same methodology for a manufacturing carve-out and a SaaS growth deal is selling a template.
4. The evidence test, applied to a provider’s proposal
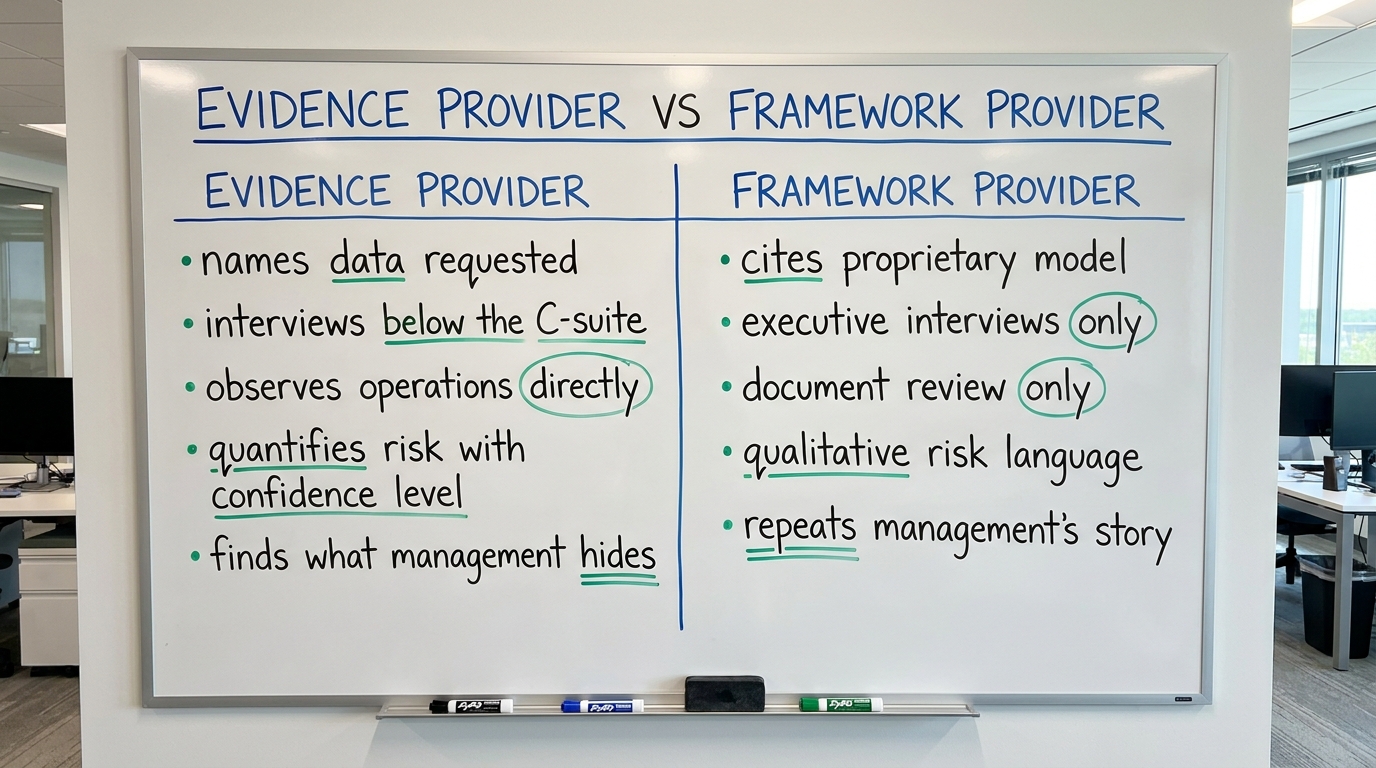
Here is the single most useful filter I know for judging an ODD provider before you sign: read their proposal and ask, for each claim they promise to deliver, what evidence would sit underneath it. Good providers describe their access, their samples, and their tests. Weak ones describe their frameworks.
Questions that separate the two
- What data will you request, and what will you do if the target cannot produce it?
- How many operational interviews, at what levels, and will you talk to people below the executive team?
- Will you observe the operation directly, or only review documents and management’s version?
- When you report a risk, will you quantify its likely impact and rate your own confidence in that estimate?
- What have you seen that management is not showing us, and how do you find it?
A provider who answers these concretely is telling you they gather evidence. One who redirects to their proprietary maturity model or their four-quadrant framework is telling you they gather opinions and format them well. The Harvard Law School Forum on Corporate Governance has published extensively on diligence quality and the governance risks of thin diligence, and the recurring theme is that process rigor, not brand, predicts whether the report holds up after close.
5. Read the operating metrics they choose to baseline
You can judge a provider’s seriousness by the metrics they propose to baseline before they have seen the data. A provider who leads with generic KPIs is going to give you a generic report. One who asks pointed, operating-model-specific questions in the first call is already doing the work.
What a strong baseline looks like
The baseline should tie directly to the levers in your value-creation plan. If the plan assumes price increases stick, the baseline needs to show historical price realization and churn sensitivity. If the plan assumes a sales-led growth engine, the baseline needs to show pipeline conversion, sales cycle length, and how much of revenue depends on a handful of accounts or reps.
This is where operational and commercial diligence have to talk to each other, and where many engagements fall down. Revenue operations is usually the seam. If your provider cannot tell you how the target’s revenue actually gets manufactured, from lead to cash, they cannot tell you whether the growth plan is real. Our buyer’s guide on what private equity should ask a RevOps consultant lays out the specific questions that expose whether the revenue engine is a system or a hero.
The metric that gets faked most
Pipeline is the number most likely to be dressed up for a sale process. A provider who accepts the CRM pipeline at face value has not done operational diligence. A provider who reconstructs conversion from raw stage-change data, then compares it to what management presented, has. This connects to why CRM data quality shapes what you can trust, particularly in businesses that grew by acquisition and never reconciled their systems.
6. Judge how they handle the things that break the thesis
Every deal has two or three assumptions that, if wrong, sink the return. A competent ODD provider identifies those early and spends most of the budget there. A weak one spreads effort evenly across a checklist, produces a comprehensive report, and buries the one issue that matters on page 47.
Ask a candidate provider directly: given what you know so far, what are the two things that would break this thesis, and how will you test them? Their answer tells you whether they think like an underwriter or a checklist-runner. The good ones will name the risks before they have full access, because they have seen the pattern before. PitchBook’s research and data and S&P Global’s market intelligence are useful here for sector context, but context is not a substitute for a provider willing to concentrate on the specific fragility of your deal.
Key-person and single-point-of-failure risk
The most common thesis-breaker in mid-market deals is dependence on one or two people. The founder who is the entire sales function. The operations lead who is the only person who understands the scheduling system. A provider who maps these dependencies and prices the retention or replacement cost into your plan is worth several times their fee. One who lists “key-person risk” as a bullet without quantifying it has done nothing.
7. Insist on outputs you can hand to the first-100-days team
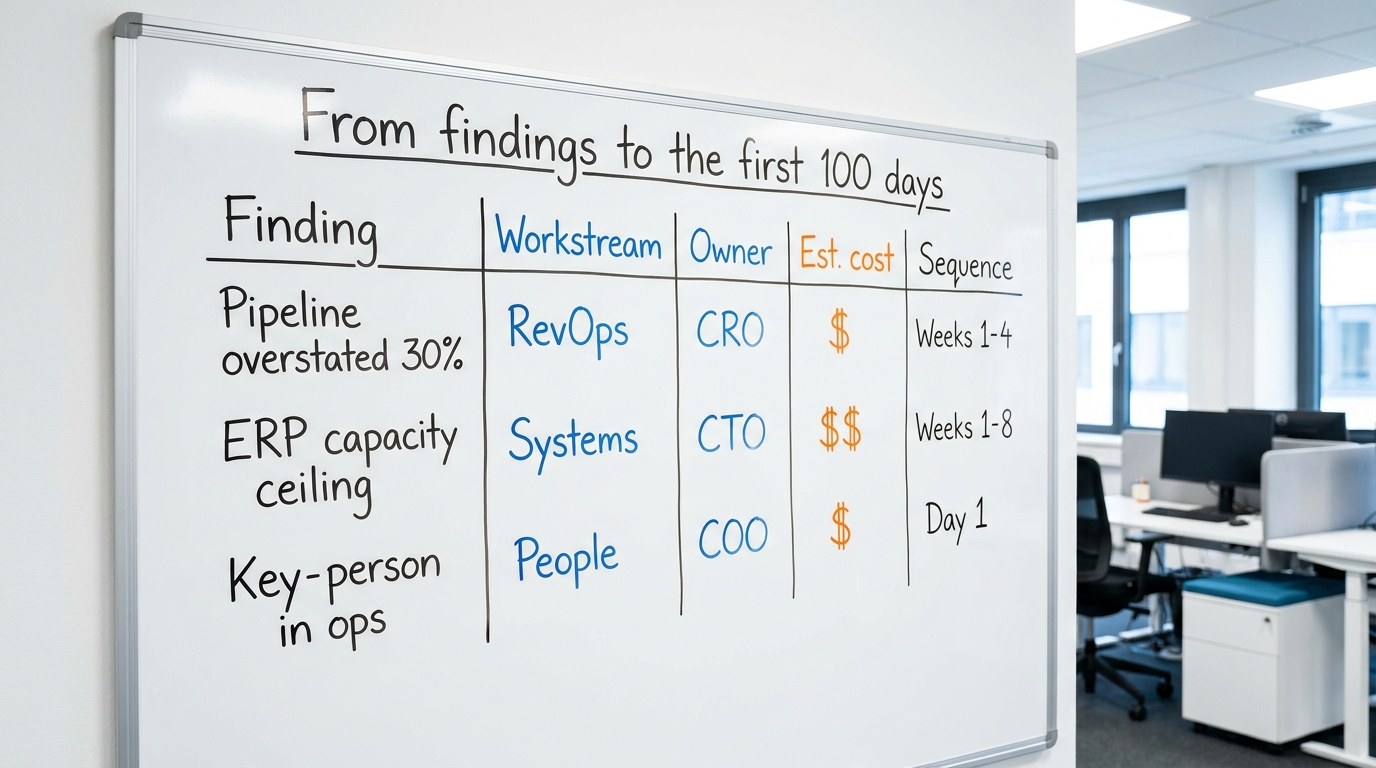
An ODD report that ends at close has failed half its job. The findings should convert directly into the value-creation plan and the early operating agenda. If the provider hands you a diagnosis with no bridge to action, someone on your team has to rebuild the whole thing in the weeks when they have the least time.
The strongest engagements produce a findings-to-action map: each material issue tied to a workstream, an owner, a rough cost, and a sequence. That is the raw material for the first 100 days plan, and it is the difference between a report that sits in a data room and one that shapes the first board meeting. When you evaluate a provider, ask to see a sample of how they translate findings into an execution plan. If they cannot show one, they do not build one.
This matters even more when the operating plan involves standardizing systems across a portfolio. If your thesis includes rolling a new acquisition onto a common platform, the diligence should already anticipate that work. Our guide on CRM standardization across portfolio companies shows how much cheaper that decision is when it is scoped during diligence rather than discovered in month six.
8. Understand how the provider makes money, because it shapes what they tell you
Incentives shape findings. A provider whose revenue depends on being invited back for the next deal has a quiet reason to keep the deal team comfortable. A provider who also sells the remediation work has a reason to inflate the problems they can then fix. Neither is disqualifying, but you should know which one you are dealing with and read the report accordingly.
The cleanest arrangement is a provider who is paid to be right, not paid to be reassuring, and who is comfortable telling you to walk. Ask directly whether they have ever recommended against a deal, and what happened. A provider who cannot recall ever saying no has either only worked good deals, which is implausible, or tells clients what they want to hear.
The AICPA and CIMA’s work on assurance and diligence standards is a useful reference point for the discipline of independent findings, even though ODD sits outside formal audit standards. The principle carries: independence of judgment is what you are paying for.
9. Right-size the scope to the deal, not to the fee schedule
Providers will scope to their standard package unless you push. A $30 million platform deal and a $4 million bolt-on do not need the same diligence, and paying for the full workup on a small add-on is as much a mistake as underspending on the platform.
Scaling scope up
Platform deals, carve-outs, and anything where you are underwriting significant operational change deserve deep, direct-observation diligence. The cost of a missed operational risk on a platform is the whole return.
Scaling scope down
For a bolt-on that will be folded into an existing operating model within months, the relevant question is narrower: what does it take to integrate this cleanly, and what breaks in the process. You do not need a full standalone operating diagnosis of a business you are about to dissolve into another one.
The strategic frame matters here too. A buyout and a growth-equity investment carry different operational risk profiles, and our comparison of growth equity versus buyout and the return engine that fits is worth reading before you set scope, because the return engine dictates which operational failures you can actually tolerate.
10. Watch how they behave when access is limited
In most processes, especially competitive ones, you will not get everything you ask for. Management will limit access, the timeline will compress, and the data will arrive late and incomplete. How a provider behaves under those constraints is the truest signal of their quality.
A strong provider tells you plainly what they could not test and how that affects their confidence. They flag the gaps as gaps rather than papering over them with confident-sounding language. A weak provider produces the same polished report regardless of how much access they had, which means the polish is disconnected from the evidence.
Preqin’s alternative assets data and reporting in Private Equity International both note the persistent tension between compressed deal timelines and diligence depth in competitive processes. The provider’s job is to be honest about that tension, not to hide it. When a report reads as fully confident on a deal you know was rushed, that is a warning, not a comfort.
11. The relationship after close is part of what you are buying
The best operational diligence providers stay useful after the deal closes, because the risk register they built becomes the tracking document for the value-creation plan. That continuity is worth paying a small premium for, provided it does not compromise their independence during diligence.
This is where operational diligence connects to the actual value-creation work, and where a provider who understands both is more valuable than a pure diligence shop. Our guide on GTM value creation for portfolio companies and the companion piece on hiring a GTM strategy consultant both show how the operating agenda flows out of what diligence found, if the diligence was built to feed it.
One caution: if the hold period itself is unusual, for instance a continuation vehicle where the same sponsor is buying from itself, the operational diligence has to be genuinely fresh rather than a rerun of the original underwriting. Our analysis of how the longer-hold thesis actually underwrites in GP-led continuation vehicles covers why the operating assumptions deserve a hard second look in those structures.
12. A checklist for choosing your ODD provider
Before you sign, run the shortlist through this. If a provider clears most of it, you are buying a diagnosis. If they miss several, you are buying a deck.
- Scope tied to thesis. Their proposal names the specific operational assumptions your return depends on, not a generic checklist.
- Evidence over frameworks. They describe the data, access, and tests they will use, and they interview below the executive layer.
- Thesis-breakers named early. They can tell you the two or three things that would sink the deal before they have full access.
- Quantified risk register. Every material risk has a likely EBITDA or cash impact, an owner, and a confidence rating.
- Pipeline reconstructed, not accepted. They rebuild the revenue engine from raw data rather than trusting the management version.
- Findings map to action. They produce a bridge from diagnosis to the value-creation plan and the first 100 days.
- Honest about access gaps. They tell you what they could not test and how it affects their confidence.
- Independent incentives. They have said no to a deal before, and they can tell you when and why.
- Scope right-sized. The depth and cost fit the deal size and the type of thesis, not their standard package.
- Sector-specific judgment. They bring pattern recognition from businesses that run like this one, not a template applied across every operating model.
The pattern across all of these is the same. You are not buying a report. You are buying a change in what you decide, whether that is the price you pay, the plan you build, or the deal you walk away from. Judge every provider against that standard. Harvard Business Review’s coverage of mergers and acquisitions and the deal-quality reporting in Buyouts, PE Hub, and disclosure guidance from the SEC all converge on the same operator truth: the diligence that pays for itself is the one that stops a bad decision or sharpens a good one, well before the money moves.
13. Where this leaves you
Operational due diligence is the workstream that most directly connects what you underwrite to what actually happens after close. Get it wrong and the model’s operating assumptions are decoration. Get it right and the risk register you commission during diligence becomes the operating agenda for year one. The choice of provider is where that gets decided, and it deserves the same scrutiny you would apply to the QoE firm or the lender.
The commercial and go-to-market side of that diagnosis is where many operating theses actually live or die, and it is often the seam where general ODD providers are weakest. If your thesis depends on revenue growth, sales-team performance, or a repeatable go-to-market motion, and you want that read with the same rigor as the financials, look at the DevriX commercial and GTM diligence work built for private equity. It is designed to turn what diligence finds into a plan your portfolio team can actually run.