
You are three weeks from signing, the QoE looks clean, and the commercial deck says the market grows at a comfortable double digit. That is exactly the moment most deals get talked into a number nobody can defend later. Revenue that looked durable in the data room turns out to be three customers deciding whether to renew. A “growing market” turns out to be growing for someone else. And the thesis you underwrote, the one that gets you from entry multiple to exit multiple, quietly depends on assumptions that were never tested against actual buyers.
Customer and market due diligence private equity work exists to stop that. Not to produce a report you file, but to answer a small set of decisions: is the revenue base as sticky as the model claims, is the market real and winnable, and does the growth plan the seller is selling you match how customers actually buy. This guide is for the operating partner or portfolio executive who already has budget approved and now has to judge whether the work coming back is good enough to bet on. It assumes you know the mechanics of a deal. It focuses on what to decide and how to tell rigor from theater.
1. The three decisions this diligence actually informs
Before you scope a single interview or buy a single market report, be clear about what the answer changes. Customer and market due diligence is expensive and slow when it drifts. It stays useful when every workstream ties back to a decision a deal team actually makes.
There are three, and only three, that matter at this stage:
- Do we proceed, and at what price. If the revenue base is more concentrated or more churn-prone than the model shows, that is a valuation input, not a footnote. It moves the number you can defend to your investment committee.
- What do we underwrite for growth. The gap between the seller’s plan and what the market and customer evidence support becomes your value creation baseline. If you cannot see that gap clearly, you are underwriting the seller’s optimism, not your own thesis.
- What has to be fixed, and by when. Every material risk you find is either a price adjustment, a condition, or a first 100 days workstream. Diligence that does not produce that list has not finished.
Bain’s annual report on the industry has tracked for years how much of returns now has to come from operational improvement rather than multiple expansion or leverage. You can read the pattern in Bain & Company’s Global Private Equity Report. The practical consequence for you is simple: the growth you underwrite has to be real, because you are the one who has to deliver it. Customer and market diligence is where you find out whether it is.
If your firm has not written down which decision each workstream serves, that is the first thing to fix. It is the difference between diligence that informs a decision and a document that justifies one already made.
2. What the QoE will not tell you
Quality of earnings is necessary and it is not sufficient. A QoE confirms that the revenue happened, that it was recognized correctly, and that the earnings are what the seller says. It is backward-looking by design. It tells you the money came in. It does not tell you whether it comes in again.
That gap is where customer diligence lives. The QoE will show you a clean revenue line from a customer who has already, internally, decided to leave. It will show you a margin that depends on a pricing structure the market is about to reprice. It confirms history; it does not test durability.
The cleanest way to think about the handoff: the accountants tell you the revenue is real, and the commercial team tells you whether it survives. We have written separately about the five revenue signals that survive a QoE, and that framing matters here. The number that clears the accounting test can still fail the durability test. Your job is to run both.
The AICPA maintains guidance on how earnings quality work is scoped and what it does and does not cover; their hub at AICPA & CIMA is the reference. Read it to understand where the QoE ends, because that boundary is precisely where your customer and market work begins.
3. Testing whether the revenue is as sticky as the model claims
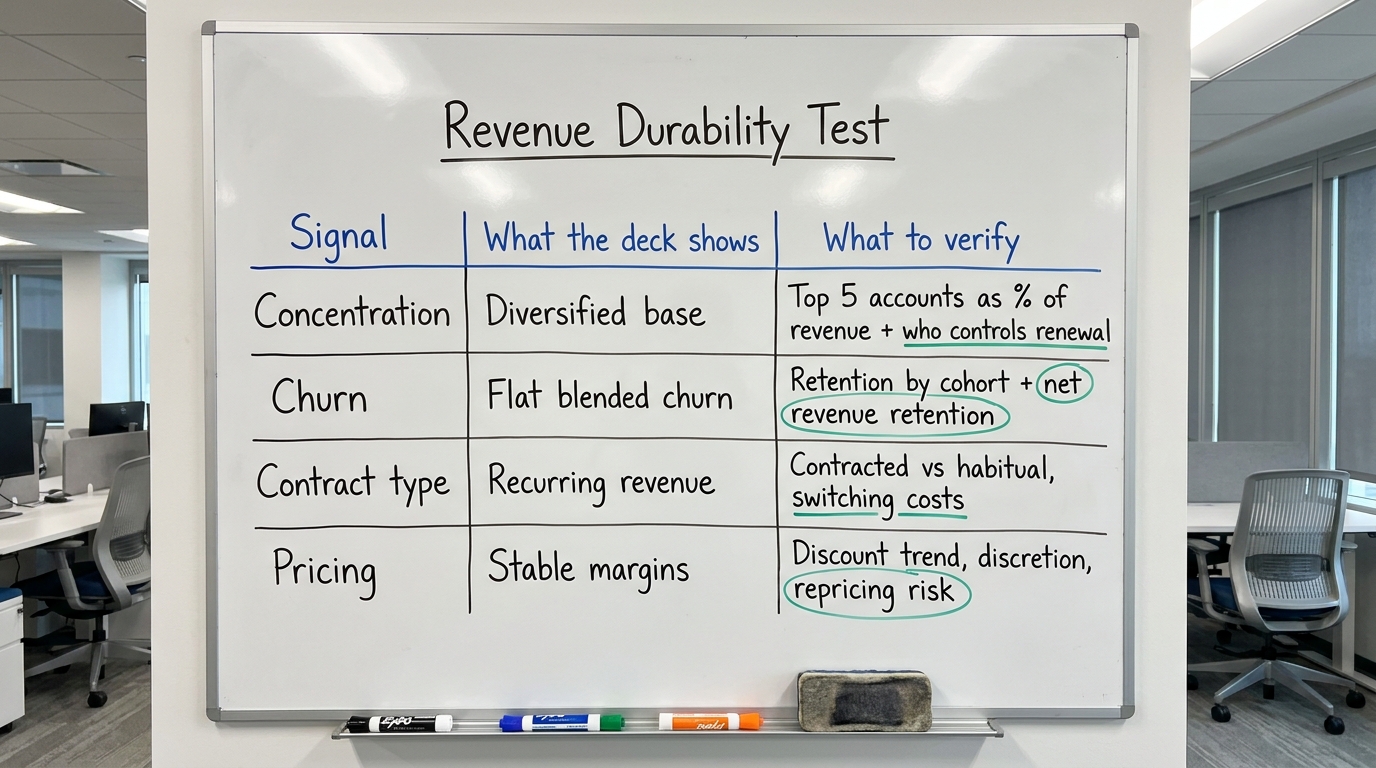
Concentration is the first thing to size. Pull the revenue by customer, by cohort, and by contract. Then ask the questions the seller’s deck avoids.
Concentration and dependency
How much revenue sits in the top five accounts, and what happens to the thesis if the largest one leaves. This is not a formality. In lower-mid-market businesses, a single account at fifteen or twenty percent of revenue can be the difference between a growth story and a workout. Map the dependency, then map who inside those accounts actually controls the renewal.
Cohort retention, not blended churn
Blended churn hides the truth. A company can show flat overall churn while its newest cohorts leave twice as fast as its oldest ones, which means the retention curve is deteriorating and the blended number is being propped up by a shrinking base of loyal legacy customers. Insist on retention and net revenue retention by cohort. If the seller cannot produce it, that is itself a finding: a company that does not track this does not manage it.
Contracted versus habitual
Distinguish revenue that is contracted from revenue that is merely habitual. Auto-renewing multi-year contracts with switching costs behave very differently from month-to-month relationships that continue out of inertia. Both show up as recurring in the data room. Only one survives a competitive threat.
4. Reference calls that surface real risk, not testimonials
Customer reference calls are the single most abused part of commercial diligence. Done badly, they produce a stack of testimonials from accounts the seller hand-picked. Done well, they are the closest thing you get to the future.
Three rules keep them honest.
Control the sample. You choose who to call, not the seller. Blend the sample: large and small, recent and long-tenured, and critically, some who have already churned or downgraded. The churned customer tells you more in ten minutes than five happy ones tell you in an hour.
Ask about behavior, not satisfaction. “Would you recommend them” is a satisfaction question and it is close to useless. “Walk me through the last time you evaluated an alternative” is a behavior question. So is “what would have to happen for you to switch” and “who else did you shortlist and why.” Satisfaction predicts nothing. Documented switching behavior predicts renewal.
Score against the thesis. Every call should feed back to the specific assumption you are testing. If your thesis is upsell into the installed base, the calls have to test appetite for the next product, not general goodwill. Harvard Business Review’s collection on mergers and acquisitions has repeatedly made the point that acquirers overweight positive signals and discount contradicting ones. Structure the calls so the contradicting signal cannot hide.
5. Sizing the market you can actually win, not the one on the slide
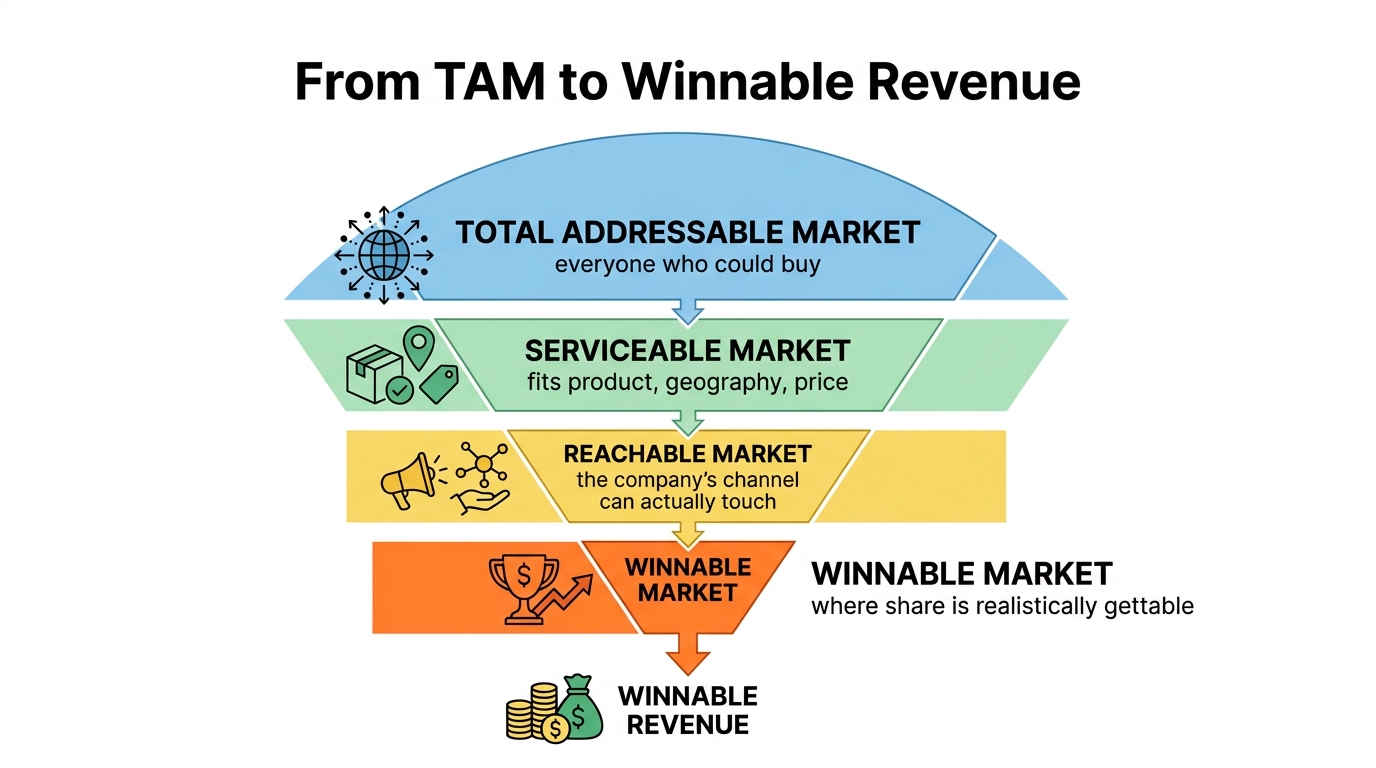
Total addressable market is where commercial decks go to inflate. A big TAM feels reassuring and tells you almost nothing, because the company does not sell into the total market. It sells into a serviceable, reachable, winnable slice, and that slice is often a fraction of the headline.
Three distinctions do the work.
Addressable versus reachable
The addressable market is everyone who could theoretically buy. The reachable market is everyone the company can actually get in front of given its channel, its geography, its price point, and its sales motion. A firm with a direct field sales team and a six-figure deal size cannot reach a long tail of small buyers, no matter how many of them exist.
Growing for whom
A market can grow while the company shrinks. Ask who the growth accrues to. If the segment is growing because a new low-cost entrant is expanding it, that growth is not the incumbent’s to capture. PitchBook’s research and market data, at PitchBook, is a useful cross-check against a seller’s growth narrative, as is S&P Global Market Intelligence for sector-level views. Use a named external source to sanity-check the growth rate the deck asserts, and note when the two disagree.
Structural position
Is the company gaining, holding, or quietly losing share. Share direction matters more than market direction. A slow grower gaining share in a flat market is a better business than a flat performer losing share in a fast one. We go deeper on how market work should change the decision in go-to-market due diligence that actually changes your investment decision.
McKinsey’s private capital research, at McKinsey, and BCG’s principal investors practice, at BCG, both publish sector work you can use to pressure-test a market narrative before you accept it. The goal is not a bigger number. It is a defensible one.
6. Does the growth plan match how customers actually buy
Here is where customer diligence and market diligence meet, and where most theses fall down. The seller has a plan. It usually involves some mix of new logos, upsell, geographic expansion, and pricing. Each lever has to be tested against evidence, not asserted.
Take the new-logo assumption. If the plan calls for doubling new customer acquisition, the diligence question is whether the current motion can carry it. What is the actual sales cycle, the win rate against named competitors, the cost to acquire, and the payback. If the reachable market is thinner than the deck claims and the win rate is falling, the acquisition plan is a hope, not a forecast.
Take upsell. The plan assumes the installed base buys the next thing. Your reference calls should have tested exactly that appetite. If customers are satisfied with what they have and see no reason to expand, the upsell line is fiction regardless of how the model compounds it.
Take pricing. Price increases are the fastest EBITDA lever in the book, which is precisely why they get overused in models. The test is whether the value proposition supports the increase and whether the competitive set allows it. Our note on value proposition budgeting is a useful frame for pressure-testing whether a price move is earned or wishful.
The discipline here is the same one that runs through good private equity value creation: separate what the business is from what someone hopes it becomes, and price only the first.
7. Reading the go-to-market machine, not just its outputs
Customers and market are the demand side. The company’s ability to convert that demand is the go-to-market engine, and diligence that skips it underwrites revenue the company cannot actually generate at scale.
Look at the mechanics, not the marketing. Pipeline coverage against target. Conversion rates by stage and whether they are trending up or down. Sales rep ramp time and productivity distribution, because a team that depends on two heroic reps is a fragile team. Marketing-sourced pipeline versus founder-sourced, since founder-led sales rarely survives a scale plan intact.
Our fuller treatment of this is in GTM due diligence in private equity, which covers what to decide before you sign. The short version for this guide: a growth plan is only as good as the machine that has to execute it. If the machine is one person and a spreadsheet, that is not a growth story, it is a key-person risk on your risk register.
8. Where technology and data become a commercial risk
Commercial diligence and technology diligence are usually run by different teams, which means the seams between them are where risk hides. Two seams matter for the customer and market view.
First, can the product deliver what the growth plan promises. If the plan is to expand into a new segment and the platform cannot support that segment’s requirements without a rebuild, the commercial forecast is gated by an engineering timeline nobody priced. This is where your commercial workstream has to talk to technology due diligence directly. A gap in that handoff shows up later as a missed year-one plan. For a sense of what a technical team actually inspects, our piece on what a buyer’s team opens first in a source code review is a useful companion.
Second, data and privacy. If the growth plan relies on customer data, marketing to the installed base, or expanding into regulated geographies, the way the company handles data is a commercial constraint, not just a compliance one. The distinction between privacy by design and privacy by default is worth understanding before you underwrite a data-driven growth lever. The U.S. Securities and Exchange Commission, at the SEC, and the governance discussion at the Harvard Law School Forum on Corporate Governance both track how disclosure and data obligations are tightening, which increasingly feeds into deal terms.
9. How to tell a rigorous provider from an expensive one
You have budget. The question is whether the work you buy is decision-grade or a laminated version of the seller’s deck. The tells are consistent.
Signs of rigor
- The provider insists on choosing part of the reference sample, including churned accounts.
- Findings are tied to specific thesis assumptions, and disconfirming evidence is presented, not buried.
- Market sizing is built bottom-up from the reachable base, not top-down from a headline TAM.
- The output ends in a risk register with owners and a value-creation baseline, not a summary.
Signs of theater
- Reference calls drawn entirely from the seller’s list.
- A big TAM slide with no bridge to what the company can actually win.
- Positive signals in bold and caveats in the appendix.
- A report priced by page count rather than by the decisions it informs.
We have written two guides specifically on this judgment: how to judge a commercial due diligence firm before you commit the budget, and, on the market side, how to hire a market due diligence consultant without buying a report you can’t use. Both come down to the same test: does the work change what you would do, or does it decorate what you had already decided. The broader frame sits in our overview of buy-side commercial due diligence and how to judge the work.
10. Turning findings into a first-100-days plan
Diligence that dies at signing wasted its own budget. The most valuable output is not the go or no-go. It is the list of things you now know have to change, sequenced and owned.
Every material finding should convert into one of three things. A price or term adjustment before close. A condition of the deal. Or a workstream in the first 100 days with a named owner and a measurable target. Concentration risk becomes an account-diversification workstream. A deteriorating retention cohort becomes a retention program with a baseline. A fragile go-to-market machine becomes a hiring and process plan. This is where a discipline like structured continuous improvement earns its place, turning findings into repeatable operating gains rather than one-time fixes.
The handoff from diligence to operating plan is where value is either captured or lost. A finding without an owner is a note. A finding with an owner, a baseline, and a date is a plan. Preqin’s data on holding periods and returns, at Preqin, and the industry coverage in Private Equity International, both point at the same reality: the clock starts at close and the plan you carry in from diligence is what you have to execute against.
11. A checklist you can hold the work to
Before you accept a customer and market diligence deliverable as decision-grade, run it against this. If the answer to any of these is no, send it back.
- Does every workstream tie to one of the three decisions: proceed and price, growth to underwrite, what to fix by when.
- Is revenue durability tested by cohort retention and contract type, not blended churn.
- Is customer concentration sized, with the renewal owner identified inside each major account.
- Was the reference sample controlled by the diligence team, including churned accounts.
- Do the calls test behavior and switching, not satisfaction.
- Is the market sized bottom-up to a winnable slice, cross-checked against a named external source.
- Is each growth lever tested against evidence: acquisition motion, upsell appetite, pricing power.
- Was the go-to-market machine inspected, not just its outputs.
- Did the commercial and technology workstreams talk to each other about what the platform can deliver.
- Does the output end in a risk register with owners, baselines, and a first-100-days sequence.
That list is the difference between a report that gets filed and diligence that protects the number you take to your investment committee. Coverage in outlets like Buyouts and PE Hub is full of deals that cleared a clean QoE and still underperformed the plan. The common thread is almost always the same: the revenue was real and the growth was not.
12. What good looks like when it is done right
Well-run customer and market due diligence does not produce comfort. It produces a sharper, sometimes lower, number that you can actually defend, plus a list of specific things to do about the risks you found. It tells you the revenue survives, the market is winnable, and the growth plan matches how customers buy, or it tells you exactly where each of those breaks.
The best sign you got it right shows up a year after close, when the year-one plan holds because the assumptions behind it were tested rather than accepted. That is the whole point. Not a thicker binder. A plan you can hit.
If you are scoping customer and market diligence on a live deal and want the work built around the decisions it has to inform, rather than a report you cannot use, see how the DevriX and GrowthShuttle commercial and GTM diligence engagement is structured and bring it into your process before you commit the number.