
You are three weeks from an LOI expiring, the QoE is progressing, and the one workstream that could actually change your entry price is the one you understand least: is the market thesis real. The seller’s management deck says the addressable market is growing double digits and the company is taking share. Your investment committee wants that claim stress-tested by someone independent before the equity check is committed. So you go shopping for a market due diligence consultant, and within two calls you notice the problem. Every firm promises a “comprehensive commercial assessment.” None of them tells you what decision their work will let you make, or how you will know if they were right.
This guide is for the operating partner, deal lead, or portfolio company executive who has the budget and the authority to commission this work, and who wants to buy a decision input rather than a bound PDF. I will walk through what the market due diligence consultant is actually being paid to resolve, how to scope it so the output is usable, and how to judge the quality of what you get back before it shapes your model.
1. Start with the decision, not the deliverable
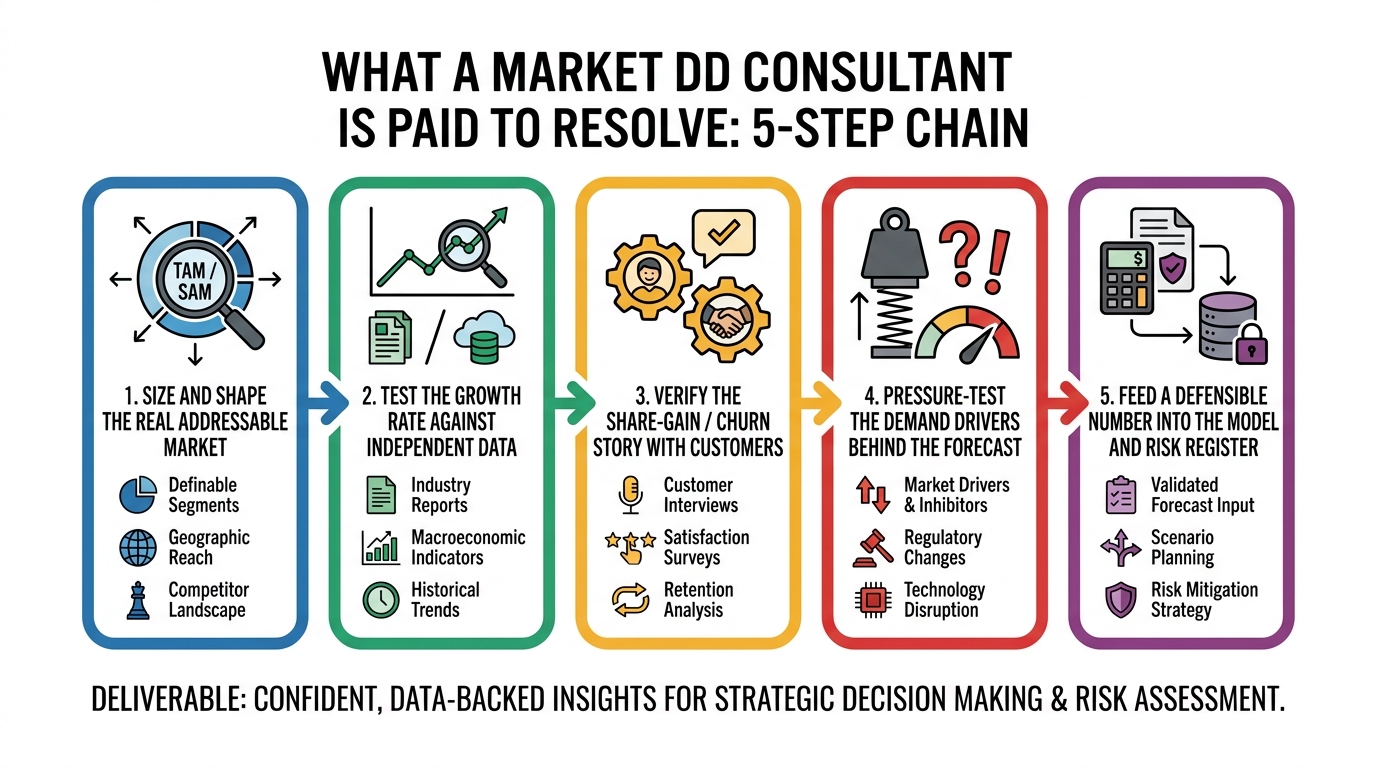
The most expensive mistake in commercial diligence is commissioning a market study before you have named the decision it informs. A market due diligence consultant can generate a hundred pages on segmentation, competitive dynamics, and pricing. Most of it will not touch your model. What touches your model is a small number of assumptions you are about to underwrite: the market growth rate, the company’s defensible share, the durability of its pricing, and the reliability of its forecast.
Before you send a single RFP, write down the two or three assumptions in the seller’s forecast that, if wrong by a meaningful margin, would change your entry price or kill the deal. Those are the questions the engagement exists to answer. Everything else is context. If a consultant cannot map their proposed scope directly onto those assumptions, they are selling you a report, not a decision input.
Bain’s annual work on private capital, published in its Global Private Equity Report, has consistently pointed to revenue and margin expansion, rather than multiple arbitrage, as the dominant source of returns in the current environment. That shifts the burden of commercial diligence. You are no longer just confirming the market exists. You are testing whether the growth the thesis depends on is real, and whether this company is positioned to capture it.
Write the question as a number you will put in the model
A weak scope asks “assess the market attractiveness.” A strong scope asks “give me a defensible range for market growth in the core segment over the hold period, and tell me the confidence level and what would move it.” The second version forces the consultant to commit to an output you can actually use, and it makes their work falsifiable. You want a number, a range, and the reasoning, not an adjective.
2. Separate market diligence from the three adjacent workstreams it keeps colliding with
Buyers routinely conflate market due diligence with commercial due diligence, GTM diligence, and quality of earnings. They overlap, but they answer different questions and they should be owned by different people.
- Market diligence asks whether the demand is there and growing, and whether this company can hold or gain a share of it.
- Commercial and GTM diligence asks whether the go-to-market engine can convert that demand into revenue at the cost and pace the plan assumes. Our companion piece on GTM value creation for portfolio companies covers what to decide there.
- Quality of earnings asks whether the historical revenue and margin the seller reports are real and repeatable. The AICPA’s guidance on financial due diligence, hosted at AICPA and CIMA, treats this as a distinct discipline for good reason.
When you hire a market due diligence consultant, be explicit about which of these you are buying and which you are not. The failure mode is a firm that quietly stretches a market scope to cover GTM execution, does neither well, and leaves you with a forecast you still cannot defend to your IC. If your bigger risk is data reliability rather than market size, our note on the five data problems that survive a QoE is a better starting point than a market study.
3. Judge the firm on its evidence base before its brand
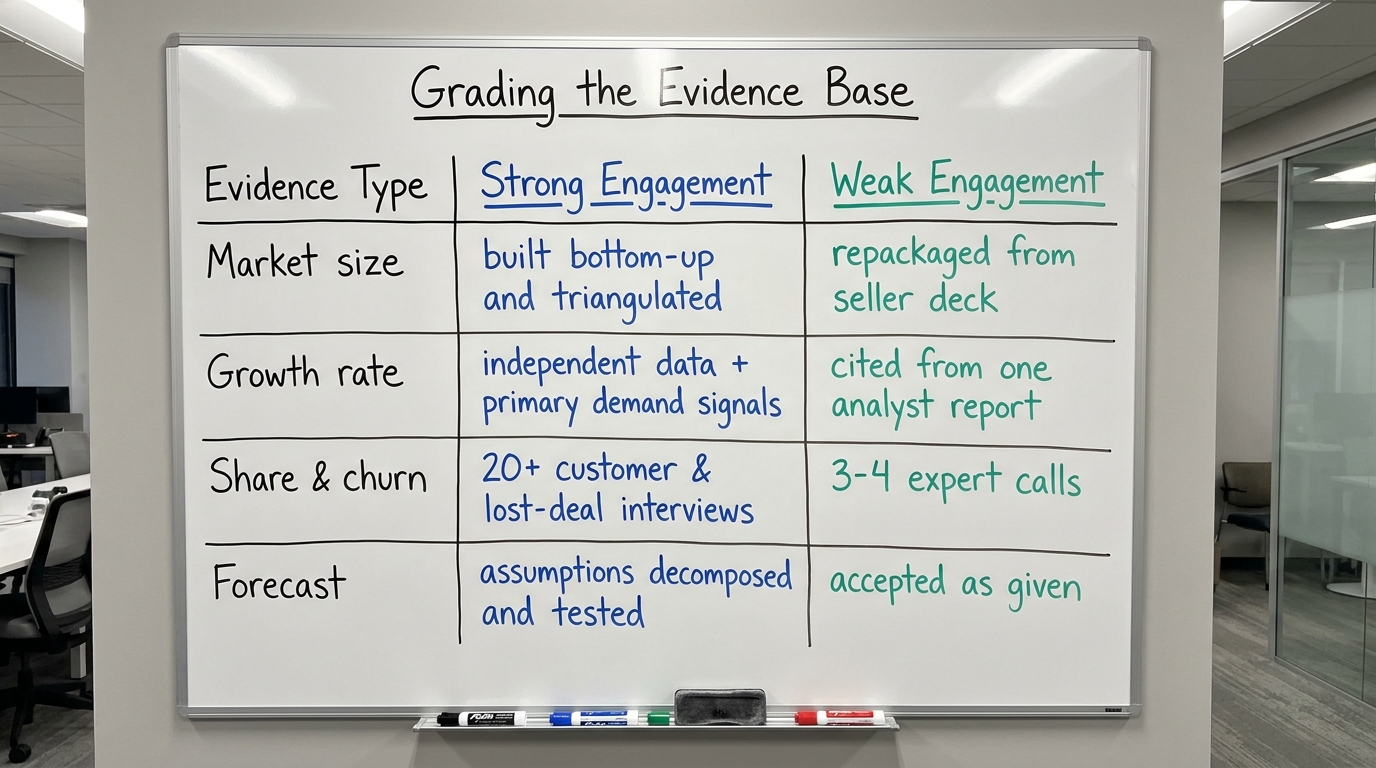
Two market studies can reach opposite conclusions and both look polished. The difference is the evidence underneath. A serious market due diligence consultant builds a conclusion from primary evidence, then triangulates it against independent secondary data. A weak one repackages the seller’s own market sizing with a new cover page.
Ask what percentage of the conclusion rests on primary interviews
The single most useful question in a vetting call is: how many customer, former customer, lost-deal, and channel interviews will you run, and how will you select them. Primary voice-of-customer work is what separates a defensible share and churn view from a desk exercise. If the answer is “we’ll do a handful of expert calls,” you are buying secondary research with a decoration of primary work.
Ask which independent data sources they will triangulate against
Credible market work cross-checks its own primary findings against independent sources. Depending on the sector, that can include PitchBook and Preqin for deal and funding activity, S&P Global Market Intelligence for industry and company data, and sector-specific analyst coverage. The point is not the brand of the source. The point is that the consultant does not let the seller’s numbers stand unchallenged, and they show you where their view diverges from the consensus and why.
4. Insist that the forecast gets decomposed, not accepted
The seller’s forecast is the single most consequential artifact in the data room, and it is the one most often taken at face value. A market due diligence consultant earns their fee by pulling the forecast apart into its drivers and testing each one against the market reality.
A forecast that assumes revenue growth of 20 percent is really a stack of assumptions: new logo volume, average deal size, expansion within the base, churn, and pricing. Some of those are market-driven and some are execution-driven. The market study should tell you which of the market-driven assumptions the outside evidence supports and which it contradicts. If the plan assumes the company captures share in a segment that independent data shows is consolidating around two incumbents, that is a finding that changes your model, and it will never surface if the consultant treats the forecast as a given.
Harvard Business Review’s ongoing coverage of mergers and acquisitions has repeatedly documented how deals underperform when acquirers accept a growth story without decomposing it. The market due diligence engagement is your best and cheapest chance to do that decomposition before the money moves.
5. Scope the deliverable so it survives into the hold, not just the deal
Here is a distinction that separates operators from spectators. Diligence output that only serves the go or no-go decision is worth a fraction of output that also seeds the value creation plan. The same customer interviews that confirm a share thesis can also surface the churn drivers you will attack in the first 100 days. The same competitive map that validates pricing power can also tell your GTM team where to expand.
When you scope the engagement, ask for two things the standard market report usually omits:
- A raw findings log, not just the synthesized narrative. The verbatim customer objections and win-loss reasons are often more valuable to the operating team than the executive summary.
- An explicit list of the two or three commercial levers the market evidence supports, framed as value creation hypotheses your operating partner can test on day one.
McKinsey’s private capital research, published across mckinsey.com, has argued for years that value creation planning should start during diligence rather than after close. A market due diligence consultant who understands that will structure their work so it hands off cleanly to the operating team. One who does not will hand you a PDF that gets filed after the deal closes.
6. Match the depth to the deal, and know when you are over- or under-buying
Not every deal justifies a full primary market study, and not every market study is deep enough for the risk. The calibration depends on where the risk actually sits.
When lighter diligence is enough
If you are doing an add-on into a market you already own a platform in, you may already hold most of the market view. In that case the marginal value of a fresh full study is low, and a targeted validation of the specific segment or geography is the right buy. The same logic applies to a well-understood, slow-moving market where the growth rate is not in serious dispute.
When you need to go deeper
The situations that demand full primary depth are the ones where the thesis depends on a claim you cannot verify from your seat: a new segment the company is entering, a disruption story, a pricing-power claim, or a share-gain narrative in a competitive market. These are also common in corporate carve-outs, where the division’s true standalone market position has never been measured because it lived inside a parent’s numbers.
The hold horizon matters too. A GP-led continuation vehicle that underwrites a longer hold is betting on market durability over a longer period, which raises the bar on how far out the market forecast needs to hold up. And whether you are running a growth equity or a buyout thesis changes which market questions carry the most weight, because a growth thesis lives or dies on the demand curve in a way a stable cash-flow buyout does not.
7. Vet the team you will actually get, not the pitch team
The proposal is delivered by partners. The interviews are run by juniors. This gap is where quality leaks out of market diligence engagements. The person who conducts a lost-deal interview needs enough domain fluency to hear what a churned customer is really saying, and enough judgment to push past the polite answer. That is not a skill you can staff from a bench of generalists overnight.
Ask who runs the primary work and what they know about your sector
Ask, by name, who will conduct the customer and channel interviews, and what sector context they bring. Ask for a redacted example of the interview guide they will use. A consultant confident in their process will show you the machinery. One who deflects to “our proprietary methodology” is protecting the fact that the machinery is thin.
Confirm who owns the analytical judgment
Gathering evidence and interpreting it are different jobs. You want to know who converts the interview transcripts and the data into the growth range and the share view, and whether that person has done it across enough deals to calibrate their own confidence. The Harvard Law School Forum on Corporate Governance, at corpgov.law.harvard.edu, regularly publishes on diligence governance, and a recurring theme is that judgment quality, not data volume, drives whether diligence prevents a bad decision.
8. Set the timeline and the checkpoints before the kickoff
Market diligence runs on a clock set by the deal, not by the consultant’s ideal process. If you have three weeks, you need to know at week one whether the early signal supports or challenges the thesis, so you can adjust your bid or your other workstreams. Do not accept a black box that goes quiet for a fortnight and reappears with a finished deck.
Structure the engagement with two hard checkpoints:
- An early read after the first tranche of interviews, where the consultant gives you their directional view and flags anything that looks like a red flag. This is the moment that can save you from spending the rest of the process defending a thesis the evidence is already undermining.
- A findings review before the final report is written, where you and the deal team can challenge the interpretation while it can still be adjusted, and where you can direct additional interviews at the questions that turned out to matter most.
The early read is the most underused mechanism in commercial diligence. It is also where a good market due diligence consultant proves they are working from evidence rather than assembling a predetermined conclusion.
9. Read the output for the tells of thin work
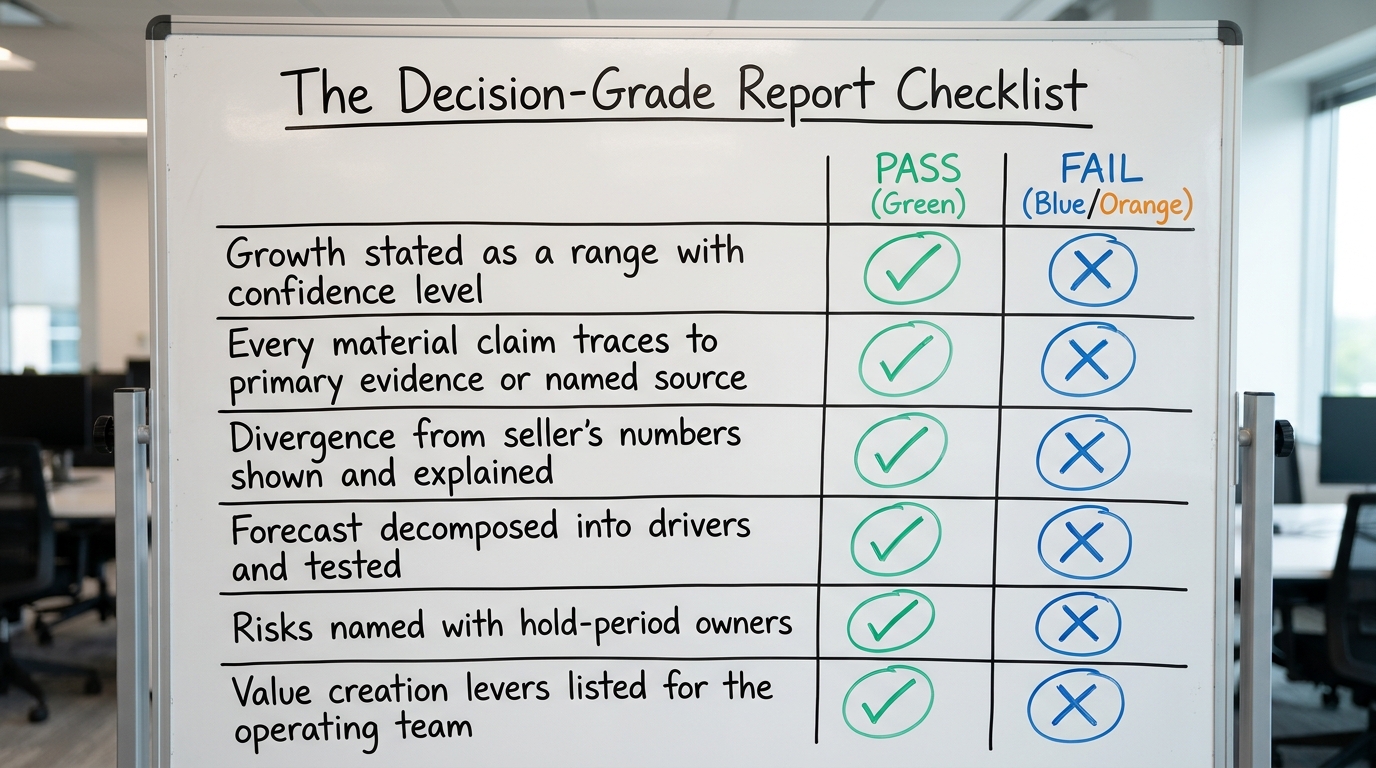
When the report lands, you have a short window to judge whether it is decision-grade before you build it into your model. A few tells separate real work from a repackaged desk study.
- Ranges, not points. A single-point market growth number with no confidence range is a guess dressed as a finding. Serious work gives you a range and tells you what would move it.
- Divergence from consensus, explained. If the report agrees with the seller’s deck on every number, either the seller was right about everything or the consultant did not do independent work. You want to see where the outside view differs and why.
- Traceable claims. Every material conclusion should trace back to primary evidence or a named source. Claims that hang in the air with no support are the ones that fail when your IC pushes on them.
- Named risks with owners. The best output does not just list risks, it flags which ones survive into the hold and who on the operating side should own them. That is the bridge from diligence to execution.
S&P Global and PitchBook both publish enough public market and sector data that you can spot-check a handful of the consultant’s headline claims yourself. If the numbers that you can verify hold up, that buys confidence in the ones you cannot.
10. Connect the market view to the operating and technology risks it implies
Market diligence rarely lives alone. A share-gain thesis that depends on a product roadmap the engineering team cannot deliver is a market finding and a technology finding at the same time. That is why the strongest diligence programs wire the market workstream into the others rather than running them in silos.
If the market view says the company must move upmarket to capture the growth, that has direct implications for the product and platform, which is where technology due diligence earns its place. If the growth depends on a more efficient sales motion, that is a RevOps question, and our guide on what to ask a RevOps consultant covers how to judge that work. If it depends on standardizing the commercial data across a buy-and-build, the market view needs to connect to CRM standardization and, where you are consolidating multiple systems, to CRM consolidation across the portfolio.
Ask your market due diligence consultant to name the operating dependencies their thesis rests on. A good one will already have them in the risk register. This is also where value-relevant risk gets separated from noise, the same discipline our piece on ESG in diligence applies to sustainability claims.
11. Price the engagement against the decision it protects
The cheapest market study is worthless if it misses the finding that would have changed your bid, and the most expensive one is a waste if the market view was never in real doubt. Price the engagement against the size of the decision it protects, not against a per-day rate.
The honest way to think about this: what is the swing in enterprise value if the growth assumption is wrong by five points over the hold, and how much of that swing does credible market diligence let you avoid mispricing. When you frame it that way, the debate stops being about the fee and starts being about whether the scope actually covers the assumptions that carry the risk. Regulators like the U.S. Securities and Exchange Commission have sharpened their expectations around how private fund managers substantiate the claims they make to LPs, which is one more reason a defensible, traceable market view is worth paying for rather than a plausible narrative.
What to negotiate, and what not to
Negotiate the number of primary interviews, the checkpoints, and the format and reuse rights of the raw findings. Do not negotiate away the early read or the traceability of claims to save budget. Those are the parts that make the output usable, and cutting them saves you a small amount of money in exchange for a report you cannot defend when it matters.
12. The buyer’s checklist for hiring a market due diligence consultant
Use this before you commit to a firm and again when their output lands.
Before you hire
- You have written down the two or three forecast assumptions the engagement exists to test.
- The consultant maps their scope directly onto those assumptions, not onto a generic market template.
- You know how much of the conclusion will rest on primary interviews and how the interviewees are selected.
- You know which independent data sources they triangulate against and how they handle divergence from the seller’s numbers.
- You know, by name, who runs the primary work and who owns the analytical judgment.
- The timeline includes an early read and a findings review before the final report is locked.
- The scope includes a raw findings log and named value creation levers for the operating team.
When the output lands
- Growth is stated as a range with a confidence level and the factors that would move it.
- Every material claim traces to primary evidence or a named source you could check.
- The forecast is decomposed into drivers, each tested against outside evidence.
- Divergence from the seller’s own numbers is shown and explained.
- Risks are named with owners for the hold period, not just listed.
- You can independently verify a handful of headline claims and they hold up.
If most of these are green, you have bought a decision input. If most are amber, you have bought a report, and you should push back before it shapes your model. The distinction between the two is the whole point of commissioning the work in the first place, and it is worth being uncompromising about.
Market diligence is only as valuable as the decisions and the value creation plan it feeds. If you want that view built to hand off cleanly into the hold, our commercial and GTM diligence work is designed to connect the market thesis to the operating plan and the risk register, so the evidence you pay for in diligence keeps working after close. See how the DevriX private equity practice structures commercial and GTM diligence for deal teams and operating partners, and bring us the two assumptions your thesis rests on.