
You have signed the LOI, confirmatory diligence starts in three weeks, and the deal team is asking you to name a commercial due diligence provider for a mid-market target. The wrong choice costs you twice: once in fees, and again when a thin market study fails to catch the customer concentration or the churn trend that later blows a hole in the forecast. If you are an operating partner scoping the workstream, or a portfolio company executive being asked to sponsor it, the decision in front of you is not “who is cheapest” or “who has the biggest logo.” It is whether the provider will produce evidence you can put in front of an investment committee, defend to a lender, and hand to the integration team on Day 1.
This guide is for a buyer with budget who already knows the terms. It walks through what the work has to deliver in the mid-market specifically, how to scope it, how to read the deliverable critically, and how to price and time it against your close. The goal is simple: spend the money once, on the right questions, and get answers that change a decision rather than decorate a deck.
1. What “good” actually has to prove in a mid-market deal
Large-cap commercial due diligence and mid-market commercial due diligence are not the same job at a smaller scale. In the mid-market, data rooms are thinner, management reporting is often improvised, and a single customer or a single rep can represent an outsized share of revenue. The provider is not there to write a market-sizing essay. It is there to answer the questions that move enterprise value: is the revenue real, is it durable, and can it grow under your ownership?
Concretely, a defensible commercial due diligence provider for the mid-market has to prove four things with evidence, not assertion:
- Revenue quality. How much of the revenue is recurring versus one-time, contracted versus at-will, and concentrated in a handful of accounts. A number in a spreadsheet is not proof; a cohort table tied to invoiced revenue is.
- Demand durability. Whether the market the target sells into is growing, flat, or quietly eroding, and whether the target is gaining or losing share within it.
- Win/loss reality. Why customers actually buy, why they leave, and what a competitor would have to do to take them. This comes from primary interviews, not desk research.
- Growth headroom under the thesis. Whether the plan’s growth assumptions survive contact with the pipeline, the sales capacity, and the pricing history.
If a proposal does not commit to producing those four with a stated evidence base, you are buying a market overview, not commercial due diligence. Bain’s annual private equity report has repeatedly documented how thin the margin for error has become as entry multiples stay elevated and returns lean more on operational improvement than on financial engineering, which you can track through the Bain & Company Global Private Equity Report. When the plan depends on operating gains, the commercial baseline has to be right.
2. Separate commercial due diligence from the studies that pretend to be it
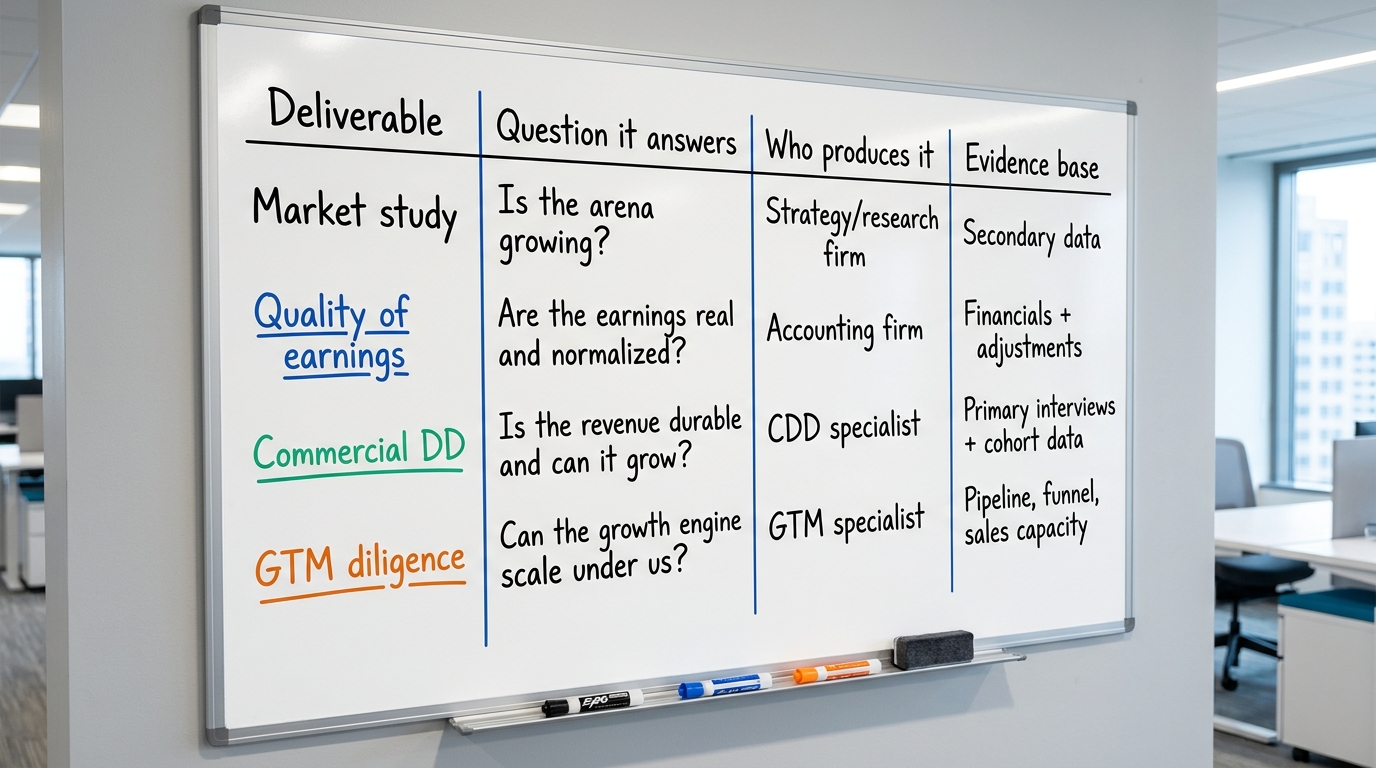
Three deliverables get sold under similar names, and they are not interchangeable. Knowing the difference is the fastest way to judge whether a provider understands your job.
Market study vs. commercial due diligence
A market study describes the arena: size, growth rate, segments, headwinds. It is useful context and it is cheap to produce, largely from secondary sources. It does not tell you whether this target will hit its plan. If the bulk of a proposal is TAM/SAM/SOM slides, you are being sold a market study with a commercial due diligence price tag.
Quality of earnings vs. commercial due diligence
A quality of earnings report, produced by an accounting firm, tests whether the reported earnings are real and normalized. Commercial due diligence tests whether those earnings are durable and repeatable going forward. The two overlap on revenue, and the best providers coordinate: several data problems that survive a QoE are exactly the ones commercial diligence should catch, a point worth reading in this breakdown of the five data problems that survive a QoE. For the accounting standards side, the AICPA & CIMA is the reference point.
Go-to-market diligence as the sharper cut
Commercial due diligence at its best includes a go-to-market view: how the company acquires, converts, retains, and expands customers, and whether that engine can scale under new ownership. This is where a generalist strategy firm often thins out and a specialist earns its fee. The distinction is spelled out well in this piece on go-to-market due diligence that actually changes your investment decision, and in the broader GTM due diligence guide for private equity.
3. Match the provider type to the deal, not the brand
The mid-market has three broad provider archetypes, and each has a failure mode you should price in.
The big-brand strategy houses
They bring rigor, bench depth, and a name your investment committee recognizes. On a lower-mid-market deal they can also bring a scoped-down junior team, a template that fights the specifics of a small company, and a fee that eats your diligence budget. Their own thinking is worth reading; both McKinsey’s private capital research and BCG’s principal investors and private equity practice publish useful frames on value creation. Whether that translates into a sharp deliverable for a $40M-revenue target depends entirely on who staffs it.
The boutique CDD specialists
Focused firms that do commercial due diligence all day, often in a sector. They tend to move faster, run more primary interviews per dollar, and write findings a deal team can actually use. The risk is variability: quality tracks the specific partner, and bench depth is shallow if your timeline slips. Judge the named team, not the firm.
The functional and technical specialists
For a software, data, or digital-heavy target, the commercial story is inseparable from the product and the tech. A commercial read that never looks under the hood misses risks that live in the code and the data model. This is where you pair commercial diligence with real technology due diligence, and where a source code review shows what a buyer’s team opens first. A firm that can carry both the commercial and technical thread, like the DevriX private equity practice, closes a gap that two disconnected vendors leave open.
The frameworks for judging these firms before you commit budget are laid out in detail in this guide to judging a commercial due diligence firm, which pairs well with the buy-side commercial due diligence decision guide.
4. Write the scope so the provider cannot hide behind a market overview
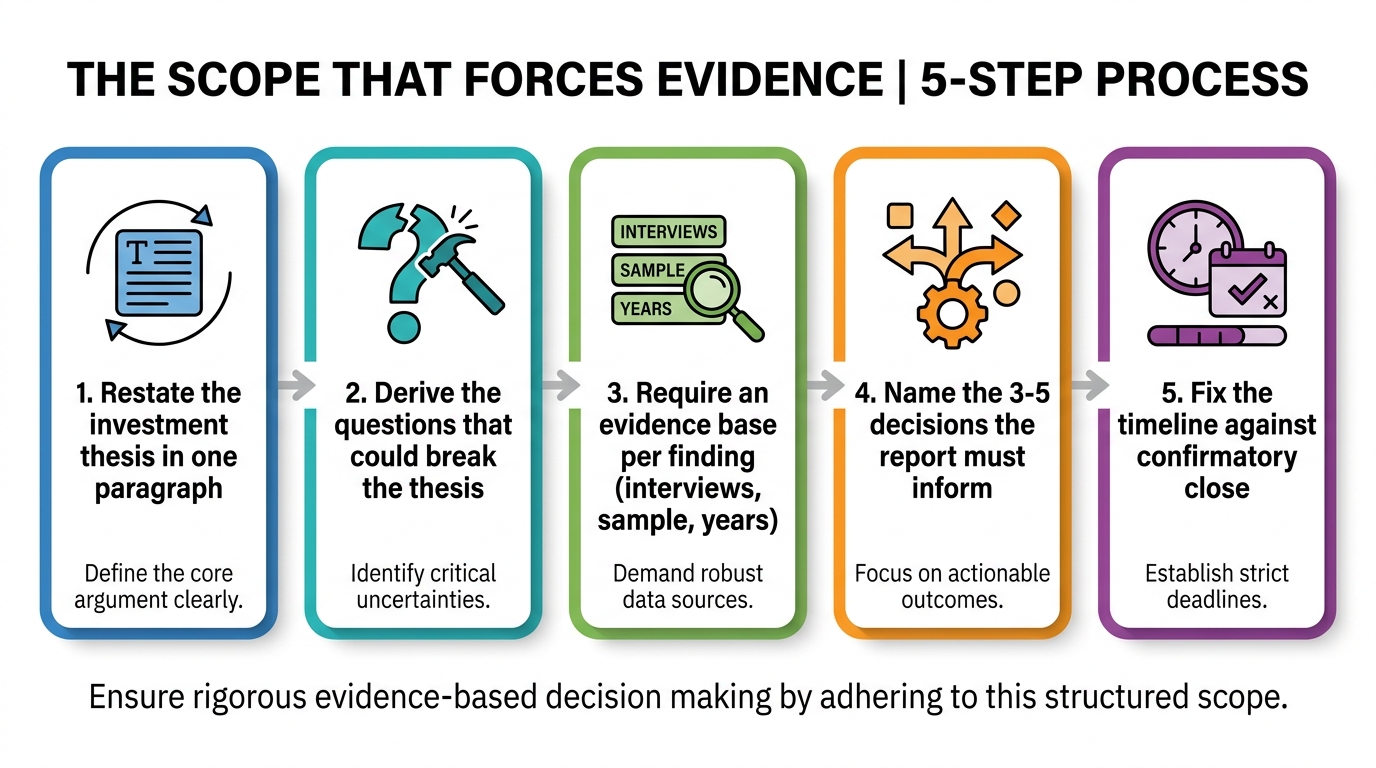
The scope document is where you win or lose this workstream. A vague scope produces a generic report. A precise scope forces the provider to commit to evidence. Before you sign an engagement, make the scope name the specific questions, the specific evidence, and the specific owner of each answer.
Anchor the scope to your investment thesis
Every question in the scope should trace back to a line in the deal thesis. If the thesis is “consolidate a fragmented market and cross-sell,” the scope must test whether cross-sell has ever worked in this business and whether the market is genuinely fragmented in the way the model assumes. Anything not tied to the thesis is padding.
Require a stated evidence base per finding
Insist that each major finding carry its source: number of customer interviews, share of revenue those customers represent, the years of data behind a churn figure, the sample behind a win rate. “Management indicated” is not evidence. A finding with no traceable source is an opinion you are paying consultant rates for.
Name the decisions the report has to inform
Write down, before the work starts, the three to five decisions this diligence exists to inform: the price you will pay, the covenants you can accept, the growth assumptions that survive into the model, the integration risks the first hundred days must address. A provider who understands those decisions writes a different report than one producing a generic assessment.
5. Read the deliverable like a skeptic, not a customer
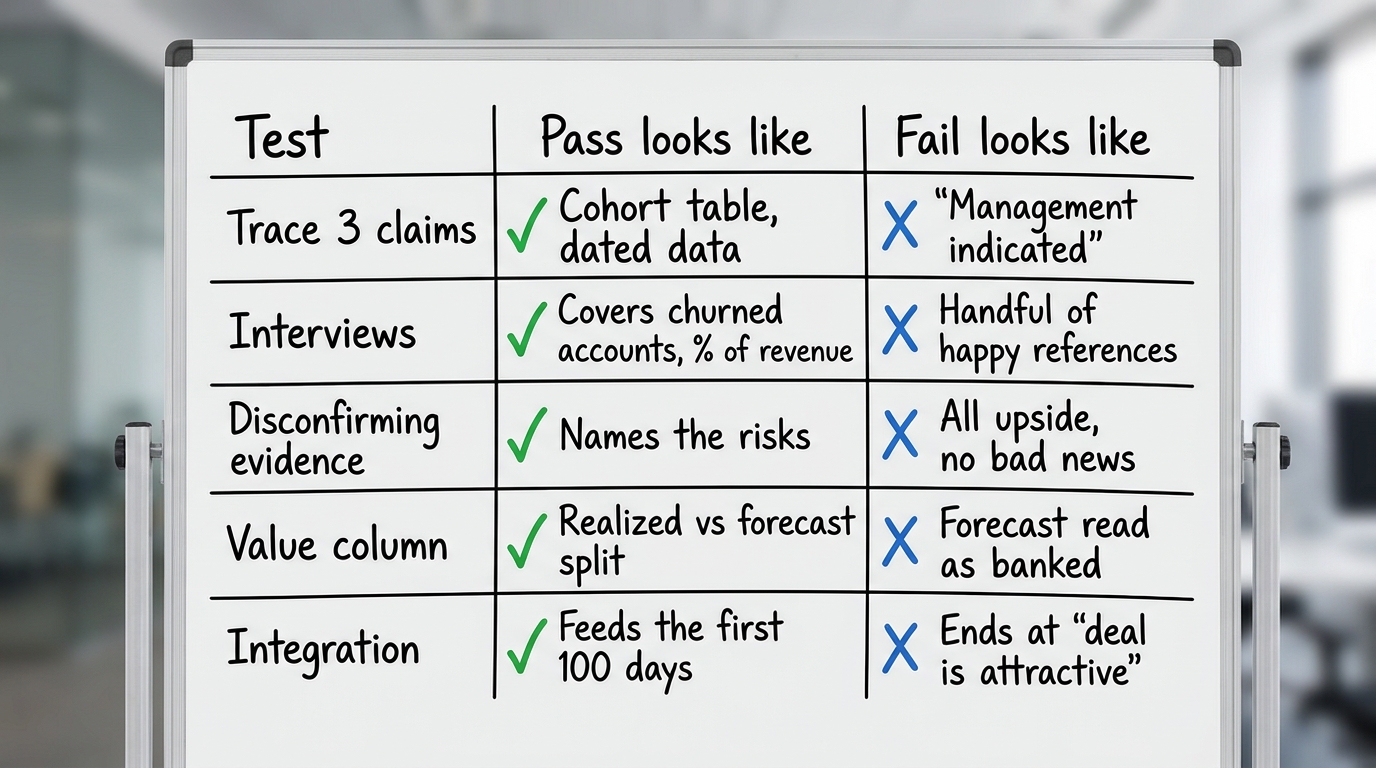
When the draft lands, resist the instinct to skim the executive summary and approve. The value is in whether the evidence holds. Here is how to pressure-test a commercial due diligence deliverable in one read.
Trace three claims back to their source
Pick the three findings most load-bearing for your decision and follow each to its base. If the report says churn is stable, find the cohort table. If it says the pipeline supports the plan, find the pipeline data and the assumptions applied to it. If a claim cannot be traced, treat it as unverified.
Check whether the interviews are real and representative
Primary customer and channel interviews are the spine of commercial diligence. Look for how many were done, whether they cover lost and churned accounts (not just happy references management supplied), and whether they represent a meaningful share of revenue. A dozen interviews weighted toward the target’s favorite accounts will flatter the numbers.
Look for the disconfirming evidence
A report that only supports the thesis is a sales document. A credible provider surfaces what argues against the deal: the eroding segment, the customer planning to leave, the pricing that cannot be repeated. If there is no bad news, either the target is flawless or the diligence is soft. The second is more likely.
Separate realized from forecast
Watch the language on value. What is realized and in the actuals belongs in one column. What is forecast, or merely enabled by an initiative that has not started, belongs in another. A report that lets forecast upside read as if it were already banked is setting up a forecast miss you will explain at a later board meeting.
6. Test the commercial read against the operating reality
Commercial diligence that never touches how the business actually runs will miss the risks that determine whether the plan is achievable. Two checks close that gap.
Does the growth plan match the capacity to deliver it?
A plan to double revenue in three years implies hiring, onboarding ramp, quota capacity, and often product investment. If the commercial report asserts growth without showing the operational path to it, the number is aspiration. Process discipline is where a lot of mid-market upside actually sits, a theme covered in this Kaizen guide for SME process savings.
Does the pricing story hold under new ownership?
Founder-run mid-market companies frequently price on relationship rather than value, and that pricing does not always survive a change of ownership or a professionalized sales motion. A serious provider tests whether pricing power is real. Where it is, that is durable margin; where it is not, the model has to reflect it. Building the pricing case deliberately is the subject of this piece on value proposition budgeting for SMEs.
7. Price the work against the value at risk, not against a rate card
Mid-market buyers often anchor on fee first, which is the wrong order. The right question is: what does it cost to be wrong about this revenue? On a mid-market deal, a diligence engagement is a small fraction of equity at stake, and a finding that adjusts the entry price or restructures a covenant pays for the work many times over.
That said, fee discipline matters, and the way to hold it is by scope, not by squeezing the day rate. Three moves keep pricing honest:
- Fixed scope, fixed fee, defined evidence. A time-and-materials engagement with a vague scope drifts. A fixed fee tied to a specific list of questions and a minimum interview count keeps both sides accountable.
- Tier the work. Buy a focused first phase on the highest-risk thesis questions, with a defined trigger to expand. You often learn enough in the first phase to know whether the fuller study is worth it.
- Price the specialist thread separately. If the deal needs a technical or data read alongside the commercial one, scope and price it as its own line rather than assuming a generalist covers it. It usually does not.
For context on where value creation now comes from and why buyers pay for operational conviction, the data hubs at PitchBook and Preqin track deal pricing and holding-period trends across the private markets, and S&P Global Market Intelligence covers the credit and covenant environment your lender cares about.
8. Insist on findings the integration team can actually use
Too many commercial diligence reports end at “the deal is attractive” and stop being useful the moment you close. The report you want is one that hands directly to the value-creation plan. That means the deliverable should flag the commercial risks and opportunities the first 100 days must address, in a form the operating team can act on without re-diligencing the business.
Ask the provider to include a short section that translates findings into the earliest operating priorities: which customer relationships need immediate attention, which pricing actions are defensible, which sales capacity gaps to fill, which reporting the company lacks and needs from Day 1. The connection between diligence and the value-creation plan is developed further in this guide to GTM value creation for portfolio companies.
9. Confirm the provider handles data and privacy responsibly
Commercial diligence involves customer lists, contract terms, and sometimes personal data pulled from CRM exports. In a regulated or consumer-facing target, how the provider handles that data is a risk in itself, and a sloppy provider can create exposure for the deal. Confirm data handling terms in the engagement, and if the target’s product touches personal data, make sure the difference between privacy by design and privacy by default is understood on both sides. Governance expectations for these matters are covered regularly by the Harvard Law School Forum on Corporate Governance, and disclosure standards by the U.S. Securities and Exchange Commission.
10. Time the work to the deal, and hold the provider to the calendar
A brilliant report that lands after the exclusivity window closes is worthless. In the mid-market, confirmatory diligence windows are tight, and primary interviews take real calendar time to schedule and complete. Build the timeline backward from your close date, and confirm the provider can hit the interview count within it before you sign, not after.
The triggers that should set your clock
- LOI signed. Scope the commercial workstream now; do not wait for confirmatory to start.
- Confirmatory diligence opens. Primary interviews should already be in motion. They are the long pole.
- Investment committee. The evidence base has to be defensible under questioning, not just a summary.
- Day 1 and the first board meeting. The findings should already be feeding the value-creation plan.
For the broader picture of how deal pace and diligence expectations are shifting, the trade coverage at Private Equity International, Buyouts, and PE Hub is worth following, and Harvard Business Review’s M&A coverage is useful on why so many deals underperform their thesis.
11. The provider selection checklist
Before you commit budget to a commercial due diligence provider in the mid-market, confirm each of these. If a provider cannot satisfy the first six, keep looking.
- Named team, not a pitch team. You know exactly who will do the work and their sector track record.
- Evidence base committed in writing. Minimum interview count, cohort data, years of history behind key claims.
- Scope tied to your thesis. Every question traces to a line in the deal rationale.
- Primary interviews include the unhappy accounts. Lost deals and churned customers, not just references.
- Findings separate realized from forecast. No forecast or enabled upside dressed as banked value.
- Disconfirming evidence present. The report tells you what argues against the deal.
- Technical thread covered where relevant. Software or data-heavy targets get a real technology read.
- Fixed scope and fee. Priced against value at risk, tiered where sensible.
- Integration-ready output. Findings hand directly to the first 100 days.
- Timeline confirmed against close. The provider can hit the interview count inside your window.
- Data handling and privacy terms in the engagement. Especially for regulated or consumer targets.
12. What this decision is really about
Choosing a commercial due diligence provider in the mid-market is a decision about evidence discipline. The market is full of firms that will produce a credible-looking deck. Far fewer will tell you what argues against the deal, trace every load-bearing claim to a source, separate what is real from what is hoped for, and hand you findings the operating team can act on from Day 1. That gap is what you are actually buying against.
Scope tightly, tie every question to the thesis, price against the value at risk rather than the rate card, and read the deliverable like a skeptic. Do that, and the diligence pays for itself the first time it changes a number in your model or a risk in your integration plan. Skip it, and you find out what the report missed at a board meeting, when it is expensive to fix.
If you are scoping commercial and go-to-market due diligence for a mid-market target and want a provider that carries both the commercial and technical thread with an evidence base you can defend, review the DevriX private equity commercial and GTM diligence offer and bring us the specific thesis questions that could break your deal.